Business
Why China now dominates Africa’s business landscape

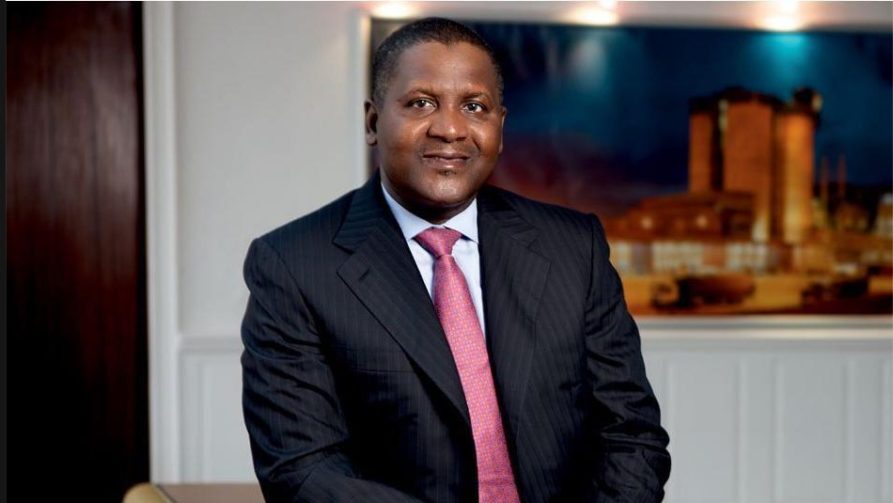





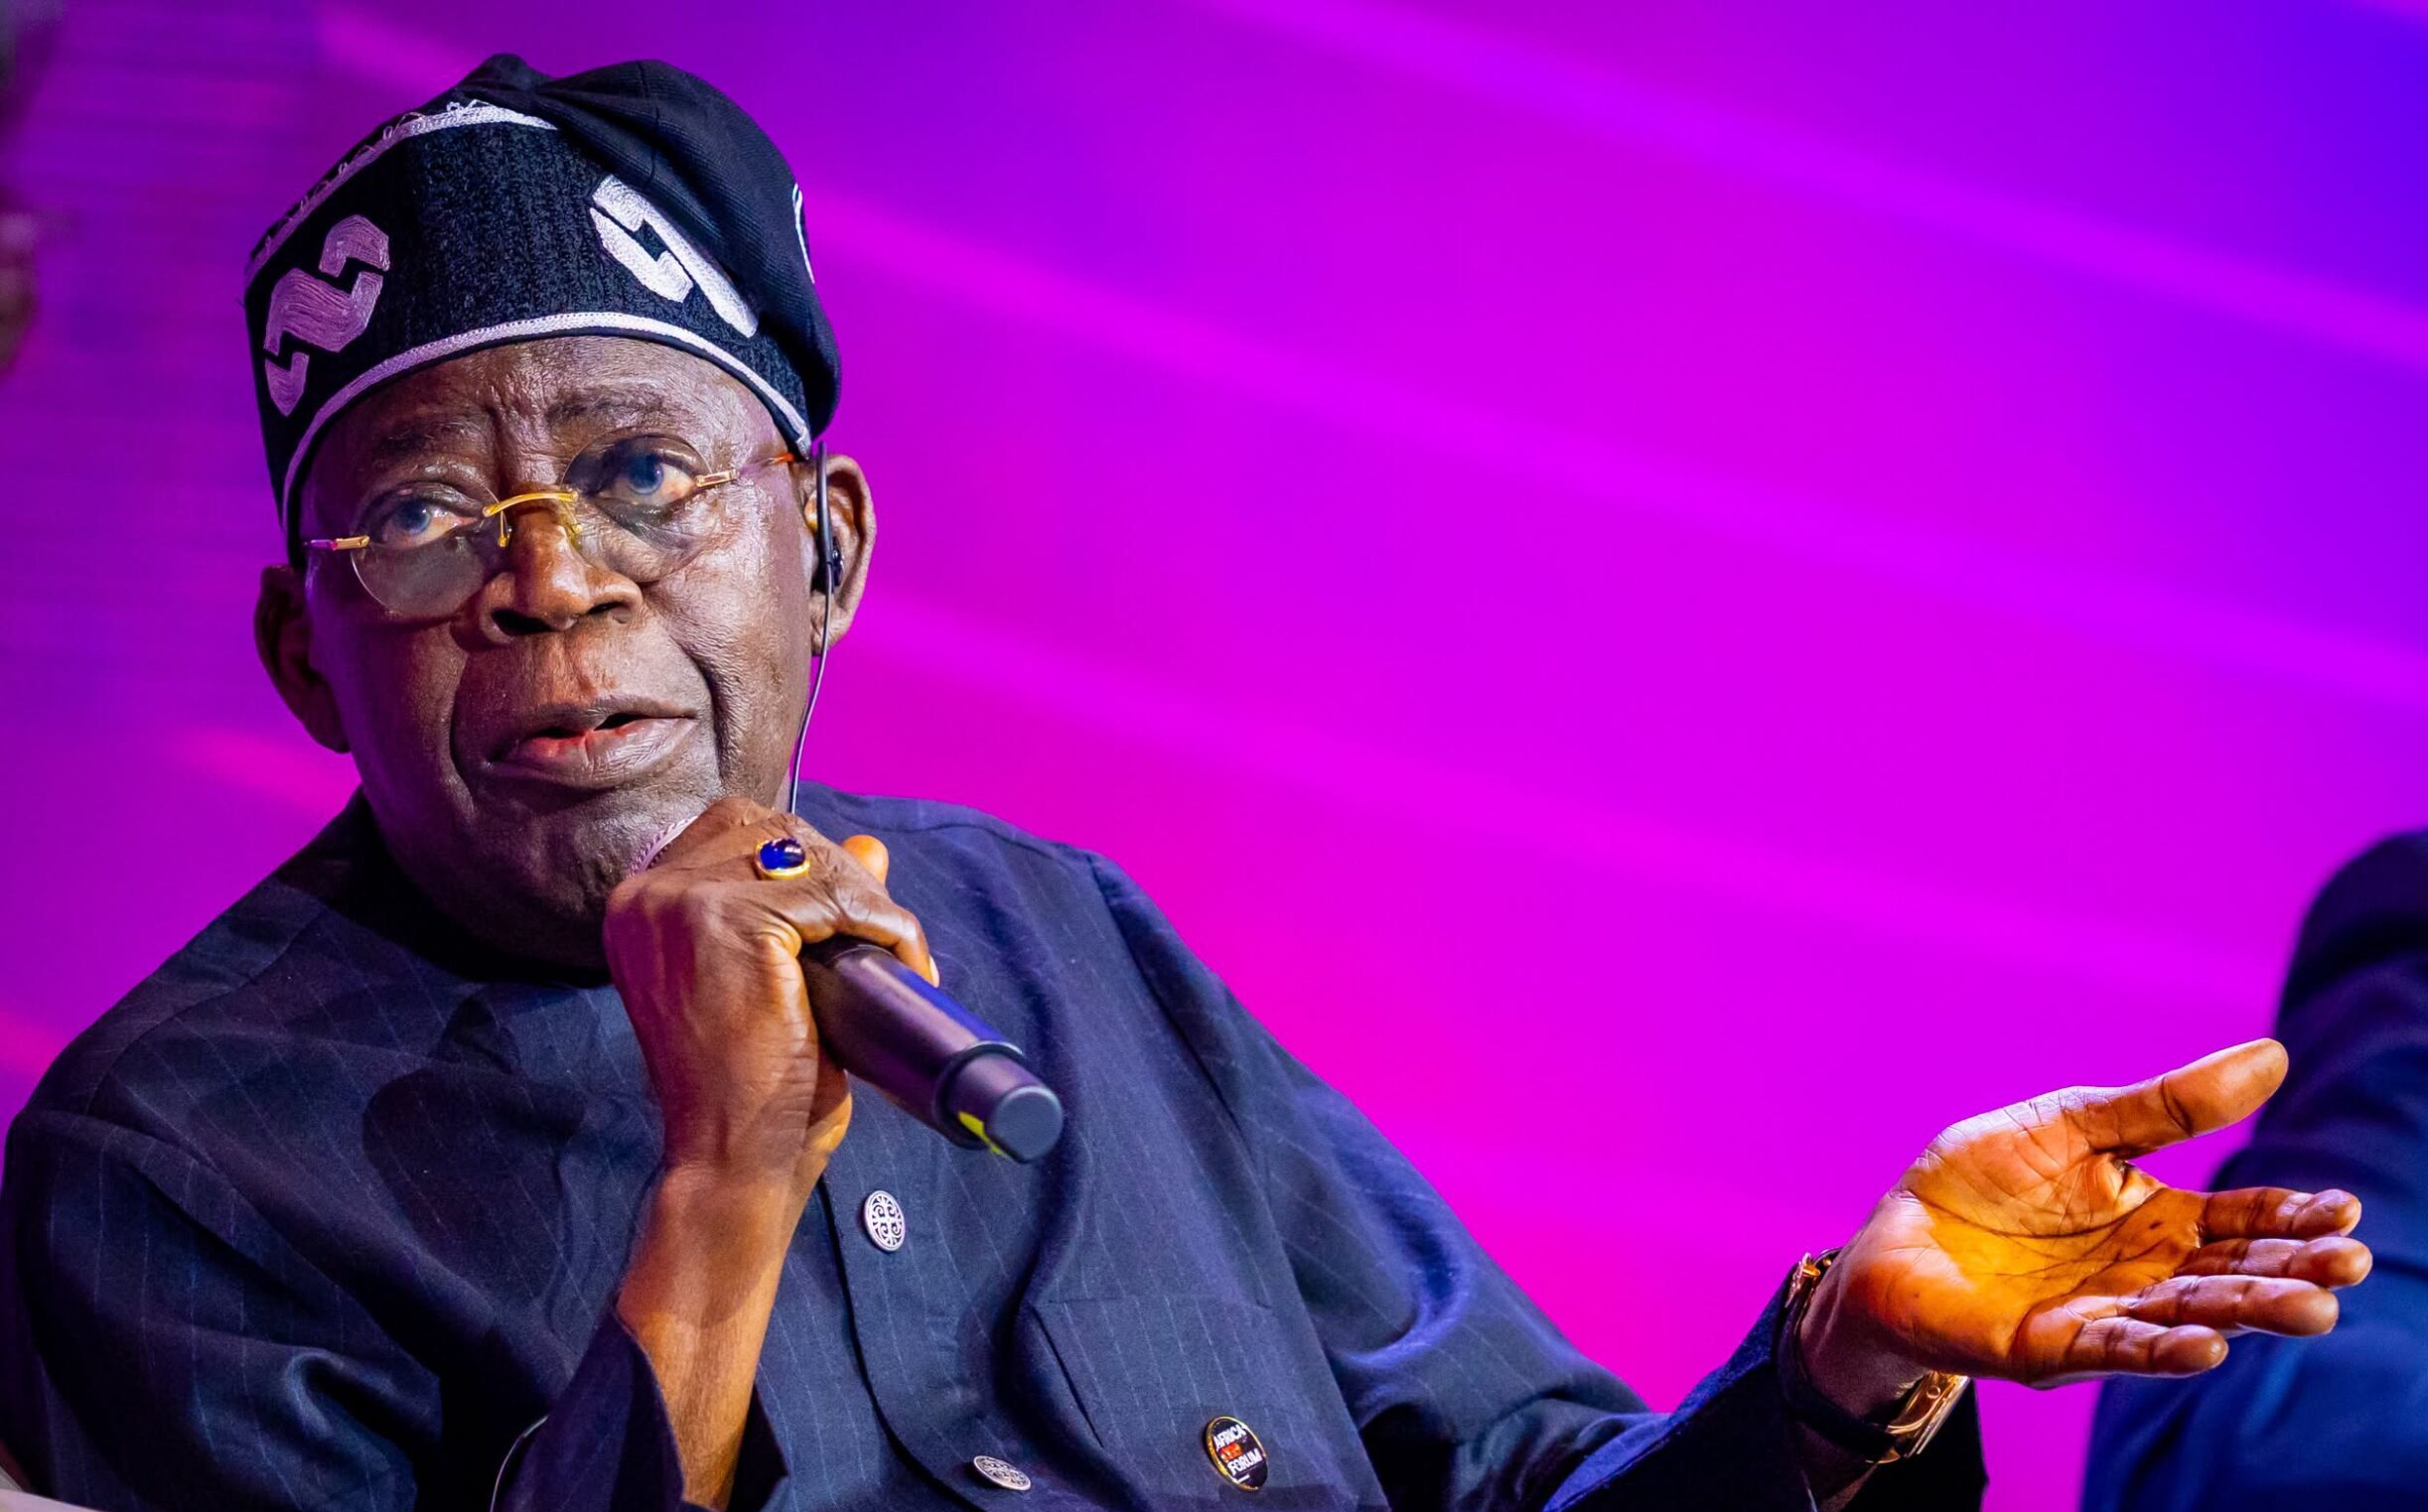
President Bola Tinubu says Nigeria has significantly reduced its reliance on oil revenue as his administration pushes to diversify the economy and attract more investment into other sectors.
He said the government would continue to develop the petroleum industry but use its resources to support broader economic activity rather than depend on crude oil as the main driver of growth.
The President, represented by Vice President Kashim Shettima, spoke on Tuesday in Abuja at the fifth anniversary of the Nigerian Upstream Petroleum Regulatory Commission (NUPRC).
“We have already reduced our dependence on oil revenue, and we intend to go further,” President Tinubu said.
He said the government’s diversification strategy was focused on agriculture, manufacturing, digital and creative industries, while the oil and gas sector would continue to provide energy, foreign exchange and revenue for the country.
The claim comes as the administration continues to pursue reforms aimed at increasing oil production, improving revenue remittances and attracting fresh investment into the petroleum sector.

In February, President Tinubu issued an executive order directing oil and gas revenues due to the Federation to be paid directly into the Federation Account.
The order also ended certain deductions previously retained by NNPC Limited, including a 30 per cent management fee on profit oil and profit gas.
Oil remains important to Nigeria’s finances
Despite the government’s push to reduce dependence on oil, petroleum remains an important source of public revenue and foreign exchange.
The sector has, however, faced challenges including fluctuations in crude production and oil prices, as well as security and operational problems.
PREMIUM TIMES reported in March that oil and gas revenue remittances had fallen significantly below projections in the first two months of 2026. While N937.10 billion was budgeted as oil and gas revenue for the period, actual remittances stood at N137.41 billion.
President Tinubu said improved security and cooperation among oil producers, host communities, security agencies and the NUPRC had helped stabilise production.
He said the government’s efforts had also helped attract investors who previously left Nigeria, adding that the country had ranked first among Africa’s leading destinations for upstream investment for two consecutive years.
Push for more oil and gas investment
The Minister of State for Petroleum Resources, Oil, Heineken Lokpobiri, said Nigeria currently produces about 1.7 million barrels of crude oil per day and has more than 37 billion barrels of oil reserves.
Mr Lokpobiri said more investment, additional licensing rounds and increased exploration were needed to unlock the country’s petroleum resources.
The NUPRC has also reported increased investment activity in the upstream sector.
In August, the regulator said it had approved more than $57 billion in Field Development Plans since 2024, with 22 major offshore projects expected to come on stream between 2026 and 2030. The projects are estimated to attract between $30 billion and $50 billion in investment.
Nigeria’s oil and condensate reserves stood at 37.01 billion barrels as of January 2026, while gas reserves increased to 215.19 trillion cubic feet, according to NUPRC data.
Tinubu declares decade of gas
President Tinubu said gas would be central to the government’s energy strategy, describing the period ahead as a decade of gas.
“With the largest gas reserves in Africa, we will expand gas supply for power, industry and clean cooking, reduce flaring and methane emissions, and grow renewable energy alongside it,” he said.
READ ALSO: PBAT Door-to-Door Movement mourns officers in crash, suspends campaign activities
He added that the government would pursue an energy transition suited to Nigeria’s circumstances, arguing that the country should meet its climate commitments without compromising energy access and economic development.
He also noted that a stronger upstream industry could create jobs for Nigerian engineers, fabricators and oilfield service companies.
President Tinubu said the Petroleum Industry Act had provided a foundation for reforms in the sector but noted that legislation alone could not guarantee investment.
According to him, investors had raised concerns about high costs, lengthy contracting processes and uncertainty around fiscal terms for complex projects.
He urged the NUPRC to maintain clear regulatory processes, provide reliable timelines and work with other government agencies to reduce overlapping requirements.
The President also said operators benefiting from government incentives must meet their obligations on work programmes, local content, environmental protection and host communities.
He urged the commission to remain independent and accountable in its regulatory decisions.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.
-

 News4 days ago
Troops rescue 15 kidnap victims, nab two suspects in nationwide operations
-
 Business4 days ago
Nigeria’s business activity expands as household confidence weakens
-
News3 days ago
Nigerians warned as AI creates new sextortion threat – Technology Times
-
News2 days ago
2027: El-Rufai’s detention could hurt APC, generate sympathy – SEDSAC director, other analysts express views