Business
PenCom Deploys Digital Platform to Boost Pension Verification Exercise

BY NKECHI NAECHE-ESEZOBOR—The Federal Government has intensified efforts to boost participation in the ongoing mandatory verification and enrollment exercise for civil servants with accrued pension rights, following a low turnout despite the significance of the programme.
The National Pension Commission (PenCom) is conducting a one-time nationwide online verification and enrollment exercise for all active employees of treasury-funded Ministries, Departments and Agencies (MDAs) who were employed before June 30, 2004.
The exercise, which began on February 2, 2026, and is scheduled to end on July 31, 2026, is designed to capture accurate and complete data on eligible workers. This is expected to support the timely payment of their accrued pension rights under the Contributory Pension Scheme.
The initiative forms part of the Federal Government’s broader effort to address pension obligations carried over from the old Defined Benefit Scheme, which was replaced by the Contributory Pension Scheme in 2004.
Under Section 15(1) of the Pension Reform Act 2014, employees who transitioned to the new scheme are entitled to accrued pension rights representing benefits earned under the previous system. To fund these liabilities, the law provides for a Retirement Benefits Bond Redemption Fund domiciled with the Central Bank of Nigeria.
In a circular dated April 27, 2026, the Head of the Civil Service of the Federation, Didi Esther Walson-Jack, directed all treasury-funded MDAs to support the exercise. The directive stressed that verification is critical for determining the Federal Government’s outstanding pension liabilities and making appropriate budgetary provisions.
PenCom said the current exercise reflects a shift from earlier manual processes that were often hindered by incomplete records and delays. The commission has deployed a digital platform known as the Contributions and Bond Redemption Application (COBRA), designed to enable real-time data capture, validation and processing.
The platform incorporates multiple layers of verification, including biometric capture and cross-checking of employment records, aimed at improving data accuracy and reducing errors that could delay pension payments.
To ensure efficiency, the exercise is being implemented in phases. The first phase, which ran from February 2 to March 31, 2026, covered employees expected to retire between January 2027 and December 2029.
The second phase, currently underway from April 1 to July 31, 2026, targets employees scheduled to retire from January 2030 onwards.
PenCom said the phased approach is intended to enhance coordination, improve monitoring and ensure all eligible employees are captured within the timeline.
However, participation has remained below expectations, prompting a directive mandating full compliance by all treasury-funded MDAs.
Under the directive, MDAs are required to upload details of eligible employees on the COBRA platform, after which affected staff are to visit their respective Pension Fund Administrators with the necessary documents to complete the process.
Pension Desk Officers trained by PenCom have been assigned to coordinate the exercise within their organisations and guide employees through the process.
PenCom assured workers that participation would enable the proper computation of their accrued pension rights and help the Federal Government make adequate provisions for payment, ensuring seamless access to benefits upon retirement.
With the July 31 deadline approaching, the Federal Government has urged Permanent Secretaries and heads of MDAs to publicise the directive widely and ensure full participation.
Officials warned that failure to participate could complicate the processing of accrued pension rights and lead to delays in accessing retirement benefits.
The post PenCom Deploys Digital Platform to Boost Pension Verification Exercise appeared first on Business Today NG.
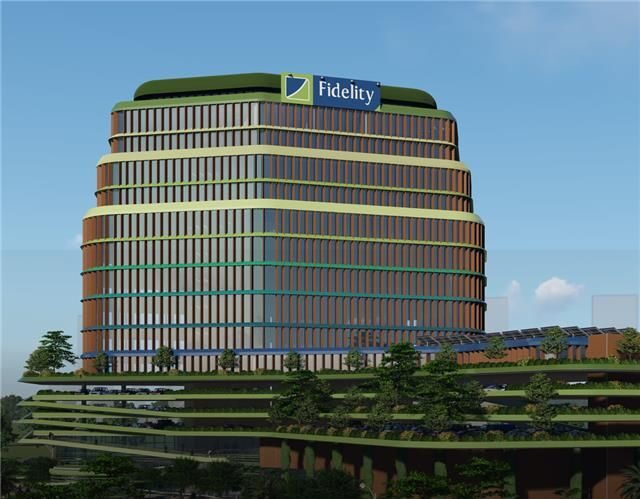
Fidelity Bank Plc has redeemed its 5-year $400 million Senior Unsecured Notes at maturity, reaffirming its commitment to meeting investor obligations and reinforcing its track record in the international debt capital markets.
Issued on 28 October 2021, the 5-year Eurobond matured on 28 October 2026 and carried an annual coupon of 7.625 per cent, payable semi-annually. Fidelity Bank met all scheduled coupon payments throughout the life of the instrument and has now fulfilled its final repayment obligation in full, covering both principal and accrued interest.
The redemption was funded from internally generated liquidity as part of the bank’s forward-looking liquidity management strategy. Through a dedicated sinking fund, Fidelity Bank progressively provided for the maturing obligation, enabling the bank to meet its commitment while maintaining business-as-usual operations and compliance with applicable regulatory liquidity requirements.
Commenting on the development, Fidelity Bank Plc’s Managing Director and Chief Executive Officer, Nneka Onyeali-Ikpe, said the successful redemption reflected the bank’s disciplined approach to financial management and its commitment to delivering on its obligations.
“This successful redemption demonstrates the strength of our franchise, the discipline of our balance sheet management and our commitment to honouring our obligations to investors and other stakeholders. We anticipated this maturity from the outset and planned accordingly, which reflects our commitment to responsible financial management,” Mrs Onyeali-Ikpe said.
The redemption further strengthens Fidelity Bank’s record in the international debt capital markets. The 2021 issuance marked the bank’s third Eurobond transaction, following earlier issuances in 2013 and 2017, in which the bank raised $300 million and $400 million, respectively. The 2021 offer attracted investor orders exceeding US$700 million, reflecting strong demand for the bank’s international debt offering.

READ ALSO: World Bank projects 23% rise in global commodity prices in 2026
The successful Eurobond redemption follows the completion of Fidelity Bank’s recapitalisation programme ahead of the regulatory deadline. The bank’s capital-raising efforts increased its eligible regulatory capital to approximately N533 billion, exceeding the N500 billion minimum capital requirement for banks with international authorisation.
The completion of these milestones underscores Fidelity Bank’s strong capital position, prudent liquidity management and disciplined approach to financial execution. It also reinforces the Bank’s capacity to meet its financial obligations while pursuing its strategic growth objectives across domestic and international markets.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.
-

 Business4 days ago
CBD COP17: Nigeria, France Push for Faster Action on 30×30 Biodiversity Target
-
News3 days ago
Poor AI data pipelines could fuel cyber exploitation in Nigeria, regulator warns – Technology Times
-
Health2 days ago
Ebola: ₦100,000 weekly allowance for quarantined contacts was unplanned
-
Health4 days ago
UPDATED: Ebola: Nigeria identifies 53 contacts linked to confirmed case