News
MTN Group service revenue hits ₦9.68tn as Nigeria contributes 30.6% – Technology Times

MTN Nigeria has emerged as the largest single contributor to MTN Group’s service revenue in the first half of 2026, accounting for 30.6% of the telecoms group’s ₦9.68 trillion service revenue, while also delivering faster revenue and earnings growth than its South African parent market.
The South African telecoms group also disclosed that it is accepting Nigeria’s competition regulator’s condition that it must sell 30% of the Nigerian component of IHS Towers “business at market prices over time” before it can approve MTN’s planned takeover of the tower company.
MTN Group reported today that service revenue of R115.3 billion, equivalent to approximately ₦9.68 trillion using the CBN exchange rate of R1 = ₦83.9728, for the six months ended June 30, 2026.
MTN Nigeria, the local business unit which is also the nation’s largest mobile network operator by subscriber base generated about ₦2.97 trillion, representing 30.6% of the MTN Group service revenue. MTN Nigeria’s contribution was also significant to the group profitability, with its R19.87 billion EBITDA, equivalent to approximately ₦1.67 trillion, accounting for 35.5% of Group EBITDA.
The performance reinforces Nigeria’s position as a critical growth engine for Africa’s largest mobile operator, despite temporary disruption to airtime advance services during the reporting period.
MTN Group said its overall service revenue increased 9.7% on a reported basis and 17.5% in constant currency, while EBITDA before once-off items rose 20% reported and 24.4% in constant currency to R56 billion, or approximately ₦4.70 trillion.
The Group’s EBITDA margin also improved from 42.7% to 47.1% on a reported basis and reached 47.6% in constant currency.
Nigeria delivers strongest major-market contribution
MTN Nigeria’s service revenue increased 25.7% in constant currency during H1 2026, compared with the Group’s 17.5% constant-currency growth.
The Nigerian business also expanded its EBITDA by 38.7%, significantly ahead of the Group’s 24.4% growth, while EBITDA margin rose by 5.3 percentage points to 55.9%.
This made Nigeria the largest contributor to Group EBITDA among the major reported operating markets, ahead of Ghana’s 24.5% contribution and South Africa’s 15.2%.
| MTN Group H1 2026 key financial highlights | H1 2026 | Approx. Naira equivalent | Growth |
| Group service revenue | R115.3bn | ₦9.68tn | 9.7% reported; 17.5% CC |
| MTN Nigeria service revenue | R35.33bn | ₦2.97tn | 25.7% CC |
| MTN Ghana service revenue | R22.13bn | ₦1.86tn | 32.3% CC |
| MTN South Africa service revenue | R21.94bn | ₦1.84tn | 1.5% CC |
| Group EBITDA before once-off items | R55.99bn | ₦4.70tn | 20.0% reported; 24.4% CC |
| MTN Nigeria EBITDA | R19.87bn | ₦1.67tn | 38.7% CC |
| MTN Ghana EBITDA | R13.74bn | ₦1.15tn | 40.0% CC |
| Group capex, ex-leases | R19.75bn | ₦1.66tn | — |
| MTN Nigeria capex, ex-leases | R7.30bn | ₦613.0bn | 1.2% increase |
| Group operating free cash flow | R25.1bn | ₦2.11tn | 27.5% |
| Group free cash flow | R11.1bn | ₦932.1bn | — |
| Group equity free cash flow | R7.0bn | ₦587.8bn | 32.7% |
MTN Nigeria’s contribution is particularly notable because its H1 service revenue was equivalent to nearly one-third of the Group’s total service revenue, while its EBITDA contribution was even higher at 35.5%.
The Nigerian operation also approved an interim dividend of ₦26 per share, underlining the improvement in its earnings and cash-generation capacity.
Data remains Nigeria’s biggest growth engine
Data was central to MTN Nigeria’s performance, with data revenue increasing 38.2% in constant currency.
MTN Nigeria added 7.5 million subscribers, taking its customer base to 92.2 million, an 8.9% increase. Active data users grew 9.3% to 55.7 million, while smartphone penetration reached 66.4%.
Network data traffic increased 25.8%, while average data usage per subscriber rose 15.1% to 14.8GB.
The figures point to continued migration of Nigerian consumers towards data-intensive digital services and strengthen the case for further investment in mobile broadband capacity.
The Group reported similar trends across its footprint. Active data subscribers rose 9.1% to 179.3 million, while data traffic increased 22.8% to 14.3 petabytes.
Group data revenue increased 21% on a reported basis to R57.6 billion, equivalent to approximately ₦4.84 trillion, and 29.2% in constant currency.
Data accounted for 49.9% of Group service revenue, making it the single largest revenue stream.
| MTN Group revenue streams, H1 2026 | Rand | Approx. Naira | Reported growth | Constant-currency growth |
| Data revenue | R57.6bn | ₦4.84tn | 21.0% | 29.2% |
| Fintech revenue | R14.9bn | ₦1.25tn | 1.4% | 13.3% |
| Voice revenue | R30.4bn | ₦2.55tn | -3.8% | 2.4% |
| Wholesale revenue | R5.2bn | ₦436.7bn | 10.3% | 15.5% |
MTN Nigeria’s voice business also remained resilient, growing 11.8% in constant currency, despite the broader structural shift from traditional voice towards data and over-the-top communication platforms.
Digital revenue in Nigeria increased 20.9%, further supporting the Group’s strategy of diversifying beyond conventional telecommunications services.
Fintech hit by airtime advance suspension
Fintech was one area where Nigeria temporarily weighed on MTN Group performance.
MTN Nigeria’s fintech revenue declined 8% in constant currency, mainly because of the temporary suspension of airtime and data credit services, which had been a significant contributor to the segment, according to the telecoms group.
MTN said the suspension reduced the eligible customer base by approximately one-quarter and accounted for 3 percentage points of MTN Nigeria’s service revenue growth during the first half.
Without the disruption, Nigeria’s service revenue growth would have been 28.7%, according to the company.
The underlying mobile money business, however, continued to expand strongly. MTN Nigeria’s mobile money revenue increased approximately 131.1%, while active wallets increased by 1.3 million to 5 million during H1.
MTN began phased reactivation of airtime advance services in July through multiple approved vendors. The Group expects the eligible customer base to rebuild progressively during the second half.
Across the Group, fintech revenue increased 13.3% in constant currency, while transaction value climbed 33.8% to US$330.5 billion. Monthly active MoMo users increased 12.1% to 70.8 million, transaction volumes rose 17.2% to 13 billion, active agents reached 1.4 million and active merchants increased 18.1% to 2.3 million.
Advanced fintech services were particularly strong, growing 31.8%, while lending transaction value rose 78.3% to US$2.7 billion.
Nigeria strengthens MTN Group profitability
MTN Nigeria’s earnings contribution becomes clearer when measured against Group profitability.
Group EBITDA before once-off items reached R55.99 billion, or approximately ₦4.70 trillion, while Nigeria contributed R19.87 billion, equivalent to about ₦1.67 trillion.
Nigeria therefore generated more than one-third of Group EBITDA despite contributing 30.6% of service revenue.
| EBITDA contribution, H1 2026 | EBITDA | Approx. Naira | Contribution to Group | Margin |
| Group | R55.99bn | ₦4.70tn | 100% | 47.1% reported |
| Nigeria | R19.87bn | ₦1.67tn | 35.5% | 55.9% CC |
| Ghana | R13.74bn | ₦1.15tn | 24.5% | 61.9% reported |
| South Africa | R8.51bn | ₦714.6bn | 15.2% | 34.3% reported |
Nigeria’s 55.9% constant-currency EBITDA margin was also substantially above the Group’s reported 47.1% margin.
MTN attributed the Nigerian margin performance to strong revenue growth, operating leverage, a stable naira and VAT input claims, although rising energy and tower-related costs remain a risk for the second half.
The company said H1 diesel costs averaged around ₦1,100 per litre, while the Q2 diesel price governing Q3 costs was below ₦1,800 per litre, although prices had subsequently eased. MTN Nigeria warned that a diesel price of ₦2,000 per litre could reduce its full-year EBITDA margin by approximately 1.8 to 2 percentage points.
Investment follows rising data demand
MTN Group invested R19.75 billion, approximately ₦1.66 trillion, in capital expenditure excluding leases during H1 2026.
The Group’s capex intensity was 16.6%, within its medium-term target range of 15% to 18%.
MTN Nigeria invested R7.3 billion, or approximately ₦613 billion, excluding leases. Its capex intensity stood at 20.6%, reflecting investment in network capacity, coverage and home broadband.
The Nigerian business said it expects capex intensity to moderate during the second half.
The investment is being driven by rising network usage. With data traffic increasing 25.8% and average usage reaching 14.8GB per active data subscriber, additional capacity will be required to sustain service quality and support future subscriber growth.
MTN Nigeria is also expanding home broadband, while the Group reported that its overall active home customer base grew 58.2% year-on-year. MTN Nigeria was identified as the Group’s leading market for fibre momentum, with rollout and customer connections materially ahead of plan.
Group cash generation remains strong
MTN Group’s operating free cash flow increased 27.5% to R25.1 billion, equivalent to approximately ₦2.11 trillion.
Free cash flow increased to R11.1 billion, or about ₦932.1 billion, with a conversion ratio of 92.5%.
Equity free cash flow, the measure used in MTN’s shareholder remuneration framework, rose 32.7% to R7 billion, approximately ₦587.8 billion.
The Group said the difference between free cash flow and equity free cash flow reflected R4.1 billion, or approximately ₦344.3 billion, in dividends paid to non-controlling interests, largely as MTN Nigeria and MTN Ghana normalised distributions following strong performances.
Nigeria also helped strengthen Group liquidity. MTN said its operating companies upstreamed R13.9 billion, approximately ₦1.17 trillion, in cash during H1, including R2.7 billion, or about ₦226.7 billion, from MTN Nigeria.
Group net debt-to-EBITDA remained low at 0.3 times, while liquidity headroom stood at R39.1 billion, approximately ₦3.28 trillion.
Profit rises despite accounting and currency pressures
Group profit after tax increased 9.5% in constant currency to R12.1 billion, equivalent to approximately ₦1.02 trillion, although it declined 4.1% on a reported basis.
Reported headline earnings per share fell 5.8% to 615 cents, while adjusted HEPS, which MTN considers a better measure of underlying operating performance, increased 21.3% to 793 cents.
Adjusted HEPS excluding Irancell increased 23.7% to 767 cents.
The difference between reported and adjusted earnings was largely linked to foreign-exchange losses, hyperinflation accounting and other non-operational items. MTN said foreign-exchange losses amounted to approximately R2.3 billion, or ₦193.1 billion.
The Group also recorded an effective tax rate of 48.9%, compared with 41.7% in the restated prior-year period. Cash tax paid rose 38.9% to R8 billion, approximately ₦671.8 billion.
Nigeria set to remain key growth driver
MTN expects Group service revenue growth to re-accelerate in H2 2026, helped by the normalisation of airtime lending in Nigeria and the annualisation of the 2025 Nigerian price adjustments.
The Group maintained its medium-term guidance for service revenue growth of at least high-teens, return on capital employed in the high-20s to low-30s and leverage at or below 1.0 times.
For Nigeria, MTN continues to target service revenue growth of at least the low-20% range and an EBITDA margin in the mid-to-high 50% range.
The Group also expects fintech growth to improve as airtime advance services are restored in Nigeria.
Beyond connectivity and fintech, MTN is advancing its digital infrastructure strategy, with Nigeria and South Africa identified as initial markets for an AI-enabled data-centre platform. The Group is also progressing its proposed acquisition of remaining shares in IHS, with conditional approval from Nigeria’s Federal Competition and Consumer Protection Commission requiring MTN Group to sell down up to 30% of the Nigerian component of the IHS business at market prices over time.
“Our priorities for the remainder of 2026 are unchanged: sustaining commercial momentum across the Group, accelerating the recovery of MTN South Africa’s prepaid business, completing the fintech structural separations underway in key markets, and progressing the IHS transaction, which continues through the required approval processes and is expected to be accretive to revenue, earnings and FCF over time.”
According to the telecoms group, “The remaining conditions are principally regulatory, with approvals received from the Nigerian Federal Competition and Consumer Protection Commission (FCCPC), and several others, with further approvals underway or imminent. With regards to the FCCPC in Nigeria, conditional approval of the transaction has been received. This is conditional on MTN Group selling down up to 30% of the Nigerian component of the IHS business at market prices over time. MTN is comfortable with the conditions as set out.”
For Nigerian customers and the wider digital economy, the H1 results point to a business increasingly driven by mobile data, broadband, digital services and fintech rather than traditional voice.
For MTN Group, Nigeria’s ₦2.97 trillion service revenue contribution and ₦1.67 trillion EBITDA contribution underline the strategic importance of the Nigerian operation to the Group’s next phase of growth under its Ambition 2030 strategy.





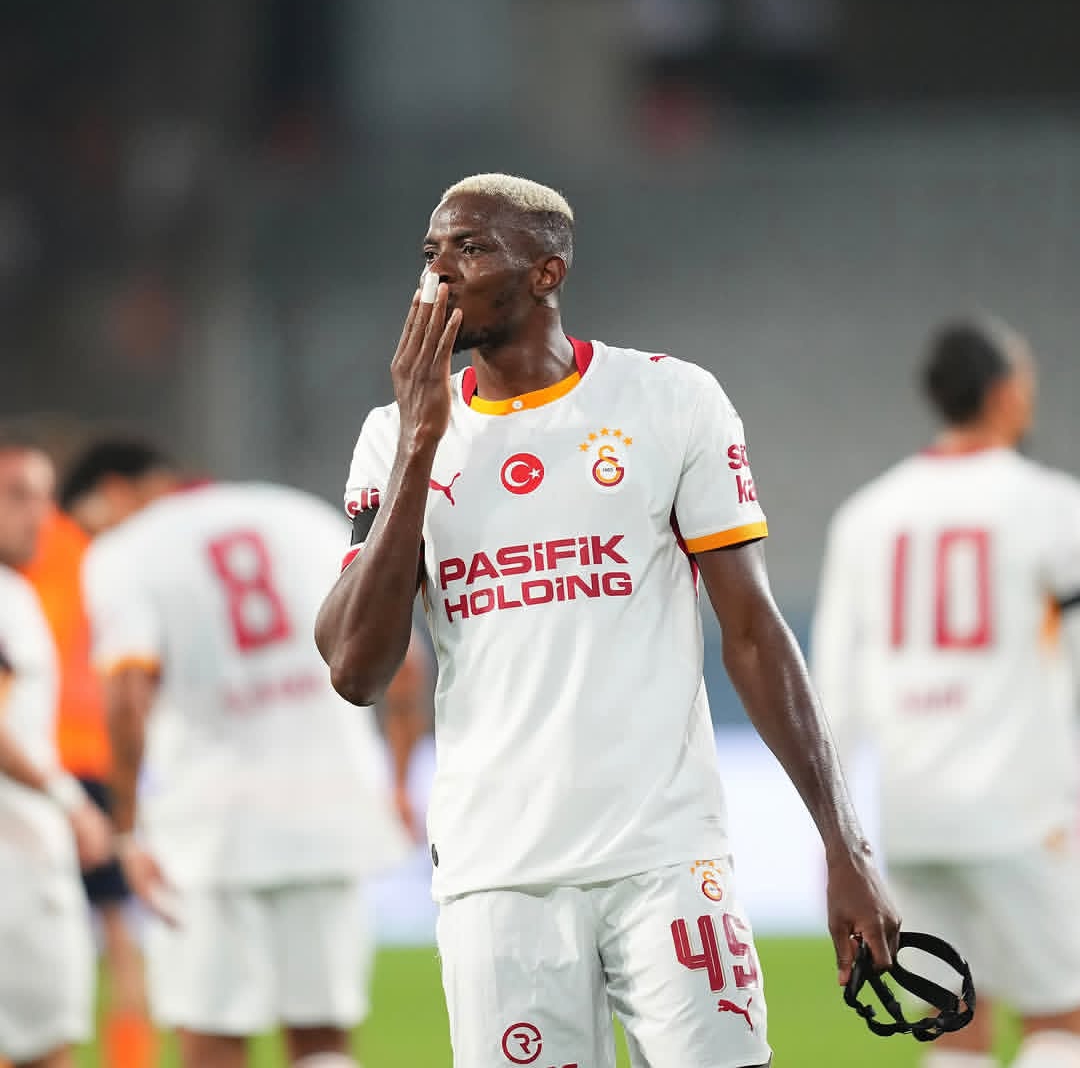
Super Eagles striker Victor Osimhen produced a mixed night for Galatasaray on Friday, scoring against İstanbul Başakşehir before being forced off with an injury that could raise concerns over his availability for Nigeria’s upcoming 2027 Africa Cup of Nations qualifiers.
Osimhen opened the scoring in the 17th minute with a stunning effort to put Galatasaray ahead.
Read Also: “My Injury Changed Everything” — Aiyegbeni Reveals How Achilles Blow Ruined Chelsea Move
However, his night was cut short after he appeared to suffer a problem following a challenge with Christopher Operi in the 23rd minute. The Nigerian striker continued briefly but later felt the problem again after making a run behind the defence and signalled that he could not continue.
Osimhen was eventually substituted in the 33rd minute, with Barış Alper Yılmaz coming on as his replacement.
Initial reports describe the problem as a suspected muscle/groin injury, but there is currently no confirmed diagnosis or recovery timeline. Osimhen himself reportedly admitted after the incident that he did not yet know whether the injury was serious.
The timing could be significant for Nigeria.
The Super Eagles are scheduled to begin their 2027 AFCON qualifying campaign against Madagascar on September 23, before travelling to face Guinea-Bissau on September 27.
That leaves Nigeria with just under three weeks before the Madagascar encounter, meaning Osimhen could still have time to recover if the injury proves minor. However, a significant muscle strain or tear could put his participation in doubt.
For now, Osimhen has not been ruled out of the Super Eagles’ upcoming matches, and his availability will depend on further medical examinations and his recovery over the coming days.
The immediate concern for Nigeria will therefore be the results of those assessments.
He scored a spectacular goal, but the biggest question tonight is whether Osimhen will be fit when Nigeria need him most.
-

 Business3 days ago
PLACCIMA Nominates Bolcit Barshep-Amakiri as Vice President, Commerce
-
Business1 day ago
IPMAN Urges FG to Intervene in Dangote Refinery Pricing to Reduce Petrol Cost
-
News4 days ago
Honest Ahanor’s Move To Crystal Palace, On Loan From Chelsea, Raises Eyebrows In Italy
-
Health4 days ago
Diphtheria outbreak kills 15, infects 117 in Plateau