Business
Lawmakers worry as Senate approves sale of third-largest cement producer

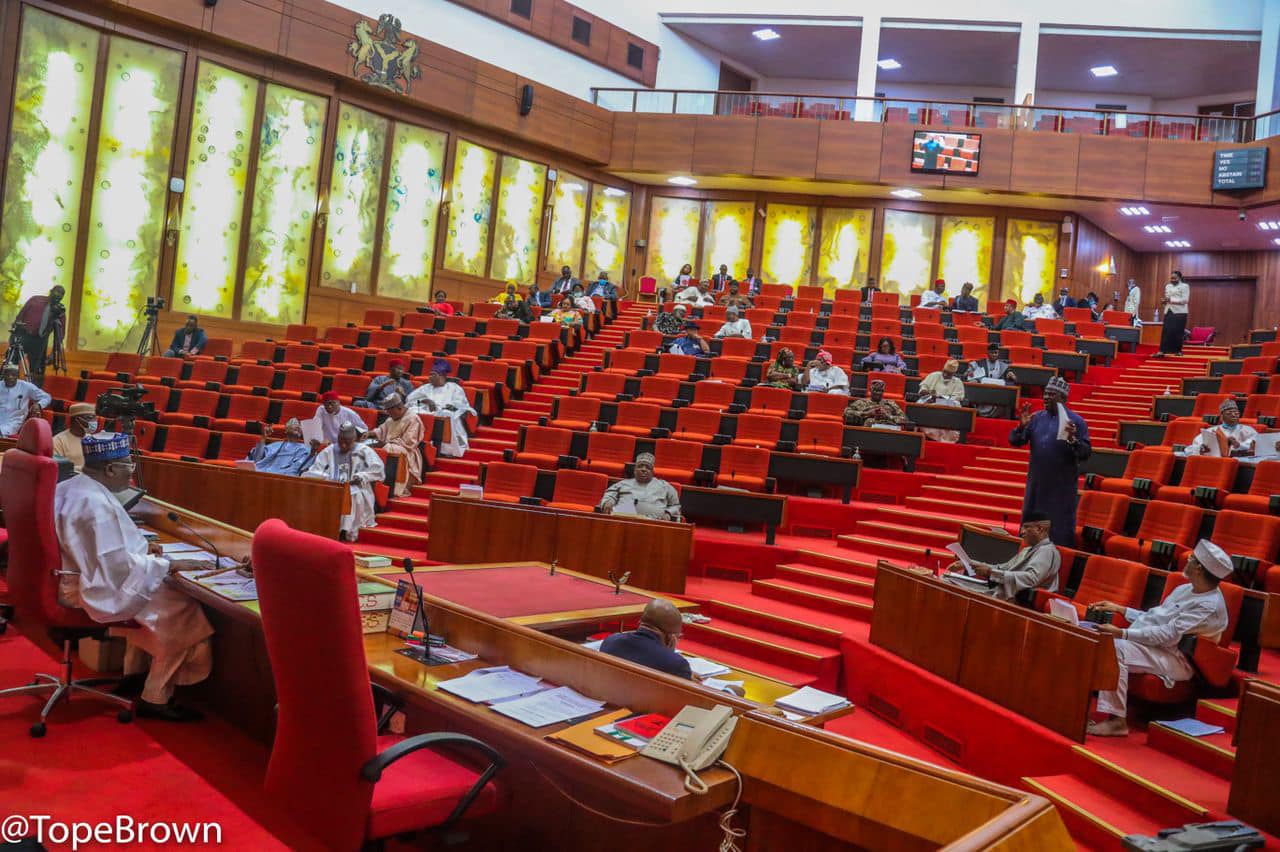
Some senators on Thursday expressed reservations over the sale of Lafarge Africa Plc, Nigeria’s third-largest cement producer, to a Chinese company.
The lawmakers expressed concerns about the transfer of ownership to Hainan Huaxin Pan-African Investment Company Plc, noting that the identities of major shareholders in the proposed ownership structure were not fully disclosed.
The ownership structure, according to the Senate ad hoc committee that reviewed the transaction, showed that Lafarge Africa is proposing to sell its 18 per cent market share to Huaxin, while Nigerian public investors currently hold a combined 16.19 per cent stake in the company.
The committee chairman, Abba Moro, while presenting the report during the plenary, recommended that the transaction be allowed to proceed and that all relevant regulatory authorities continue to monitor compliance with Nigerian laws and regulations.
However, the report did not provide details of the remaining shareholding structure, either under the current arrangement or after the completion of the proposed acquisition.

The senators who opposed the sale said that a transaction involving one of Nigeria’s major cement producers should be conducted with greater transparency, including full disclosure of the company’s ownership structure.
The senator representing Bauchi Central, Abdul Ningi, was the first to question the proposed sale, describing the transaction as insufficiently transparent. Mr Ningi, a member of the Peoples Democratic Party (PDP), criticised the committee’s report for failing to disclose the complete shareholding structure of the company.
“I would have imagined that the report of the committee should specifically give us shareholding. Sixteen per cent Nigerians, 18 per cent Lafarge, what about the remaining? Who owns that? So, we need to understand where we are coming from. It is when you know who owns the rest that you’ll understand whether Nigerians are benefiting from these sales,” he stated.
Similarly, the senator representing Gombe Central, Danjuma Goje, expressed concerns about Lafarge’s operations in Gombe State, arguing that the company had not sufficiently benefited its host communities. Mr Goje, a former governor of Gombe State, urged the committee to recommend stricter conditions that would compel the company to comply with regulatory requirements and existing agreements with host communities.
Also, the senator representing Kebbi North Senatorial District, Yahaya Abdullahi, called for stronger safeguards to ensure that Nigerians, particularly residents of host communities, derive greater benefits from the transaction.
The Deputy Senate President, Barau Jibrin, who presided over the session, maintained that the chamber could only act on the recommendations contained in the committee’s report. Mr Jibrin, who represents Kano North Senatorial District, added that anyone seeking additional details about the transaction could obtain them through the Freedom of Information (FOI) Act.
“Anybody can write an FOI to the appropriate body to ask whatever information they wanted to ask,” he said. The Deputy Senate President subsequently put the committee’s recommendations to a voice vote, with the majority of senators supporting them. The Senate thereafter approved the transaction.
Lafarge Africa, a major player in Nigeria’s cement industry, is a subsidiary of Holcim AG, a multinational building materials company listed on the Swiss stock exchange. Lafarge Africa itself is listed on the Nigerian Exchange (NGX).
Holcim AG is reportedly finalising plans to sell its 83.8 per cent stake in Lafarge Africa to China’s Huaxin Cement Co. in a deal valued at about $1 billion, subject to regulatory approvals.
The proposed sale was first debated on the floor of the Nigerian Senate in March 2025, when the senator representing Ogun Central, Shuaib Salisu, sponsored a motion to address issues such as lack of transparency in the divestment process and limited access to the deal for Nigerian investors.
During the debate, senators were divided. While some cautioned against interfering in legitimate private-sector transactions and foreign investment, the majority stressed the need for regulatory oversight.
The Senate subsequently directed the Bureau of Public Enterprises (BPE) and Securities and Exchange Commission (SEC) to ensure the sale aligns with Nigeria’s economic and national security interests, and mandated its Capital Market Committee to liaise with all relevant agencies for proper scrutiny.
READ ALSO: Lafarge unveils new corporate identity, changes name to HBM Nigeria Plc
After the Capital Market Committee submitted its report recommending approval of the transaction, some senators remained dissatisfied, prompting the Senate to establish an ad hoc committee chaired by Mr Moro, the Minority Leader, to conduct a further review.
Lafarge Africa has many factories in Nigeria with cement operations in the South-west (Ewekoro and Sagamu in Ogun State), North-east (Ashaka, in Gombe State), and South-south (Mfamosing, Cross Rivers State). It also has Ready-Mix operations in Lagos, Abuja and Port Harcourt. Lafarge Africa has a current installed cement production capacity of 10.5 metric tonnes per annum.




The International Monetary Fund (IMF) said targeted, temporary income support is the most effective and cost-efficient way for governments to protect vulnerable households during cost-of-living crises.
IMF disclosed this in its latest World Economic Outlook, noting that broad-based subsidies can impose higher costs on public finances.
The IMF report examined the economic consequences of cost-of-living crises and the effectiveness of government interventions across 76 countries over three decades.
The financial institution said consumer subsidies could require three to six times more fiscal resources than targeted cash transfers to provide the same level of protection to lower-income households. In contrast, producer subsidies could cost 14 to 22 times more.
According to the lender’s report, disruptions to global commodity markets, including those following Russia’s invasion of Ukraine in 2022 and conflicts in the Middle East, have driven up prices for essential goods and services such as food and energy.
The IMF said these episodes often have lasting consequences beyond the initial price surge. It said this makes essentials more expensive relative to other goods, weakens household purchasing power, and complicates central banks’ efforts to control inflation.
“Inflation expectations also rise and stay above pre-crisis levels for years, suggesting that these episodes may complicate efforts by central banks to control inflation,” the report said.
It added that real wages could fall and remain below their previous levels for an extended period.
The Fund explained that poorer households bear a disproportionate share of the burden because food and energy make up a larger share of their spending than they do for wealthier families.
It noted that the effects on poverty and inequality were severe in lower-income countries, where necessities account for an even larger share of poor households’ expenditure.
Subsidies carry higher fiscal costs
The IMF said governments often responded to cost-of-living pressures with broad-based measures to suppress price increases, including tax reductions, producer subsidies, lower customs duties, and price controls.
According to the report, advanced economies had relied more heavily on reductions in value-added and excise taxes on food and energy.
Emerging markets and low-income countries also more often used measures targeting production costs and supply chains.
Governments also provided income support, with advanced economies using more targeted transfers and poorer countries more often introducing broad-based wage and pension increases.
However, the IMF said these interventions differed in their effectiveness and the financial burden they placed on governments.
It identified targeted, temporary transfers as the preferred approach because they direct assistance to households most in need, preserve limited government resources, and allow market prices to reflect scarcity.
On the other hand, the financial institution said price-suppressing measures can be expensive because much of the support may benefit households that do not need it.
The report cited Europe’s 2022–2023 energy crisis, during which less than 20 cents of every euro spent suppressing electricity, natural gas and gasoline prices reached the poorest fifth of households.
“Subsidising producers can cost 14 to 22 times more than targeted income support,” the IMF said.
It also warned that keeping prices artificially low could weaken incentives to conserve scarce resources.
When several countries adopt such measures at the same time, they can drive up global prices and worsen economic pressures on lower-income countries, the Fund said.
“Producer subsidies are even less efficient. Because they lower production costs rather than directly supporting households, foreign consumers benefit through lower export prices of downstream products.
“As a result, taxpayers pay more to benefit people and businesses in other countries rather than vulnerable families at home,” the lender stated.
Temporary, targeted interventions
The Fund recommended that governments make assistance temporary and deliver it through targeted income-support programmes.
It said the measure could be implemented by expanding existing social protection systems that can be scaled up quickly during crises.
“Assistance, when warranted, should be temporary and delivered through targeted income-support measures, ideally using existing social protection systems that can be scaled up quickly,” it said.
READ ALSO: IMF warns rising stablecoin use could weaken Naira demands
It said broader interventions might be necessary in exceptional circumstances, including acute food insecurity, heightened risks of social unrest or serious difficulties in identifying and reaching eligible beneficiaries.
However, such support should be designed around the temporary component of a price shock rather than permanently higher prices, with clear deadlines for ending the measures.
Where price controls or subsidies are unavoidable, the IMF advised governments to focus narrowly on goods and services consumed disproportionately by vulnerable households while preserving market signals as much as possible.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.
-

 News4 days ago
Mirror Particle is building a ‘world model’ of human behavior
-
News4 days ago
FCCPC reviews rules for Nigeria’s online sales promotions, giveaways – Technology Times
-
News3 days ago
Robot data startup Mecka AI nabs $60M from Sequoia
-
Business4 days ago
Nigeria has reduced reliance on oil revenue