News
Govt pegs 1.5% stamp duty on cryptocurrency conversions in Nigeria, new tax rules reshape digital asset market – Technology Times

The Nigeria Revenue Service (NRS) has introduced a 1.5% stamp duty on cryptocurrency conversions, requiring taxes to be collected whenever fiat currency is exchanged for virtual assets or virtual assets are converted into fiat currency, in a move that brings greater tax certainty to Nigeria’s rapidly expanding digital asset market.
The measure is contained in the Guidelines on the Taxation of Virtual Assets, issued on July 31, 2026, which establishes Nigeria’s most comprehensive tax framework yet for virtual asset transactions involving taxpayers, Virtual Asset Service Providers (VASPs), peer-to-peer (P2P) marketplace operators, financial institutions and other participants in the country’s digital asset ecosystem.
The guidelines clarify tax obligations, reporting requirements, valuation methods, collection mechanisms and enforcement procedures governing cryptocurrency and other virtual asset transactions.

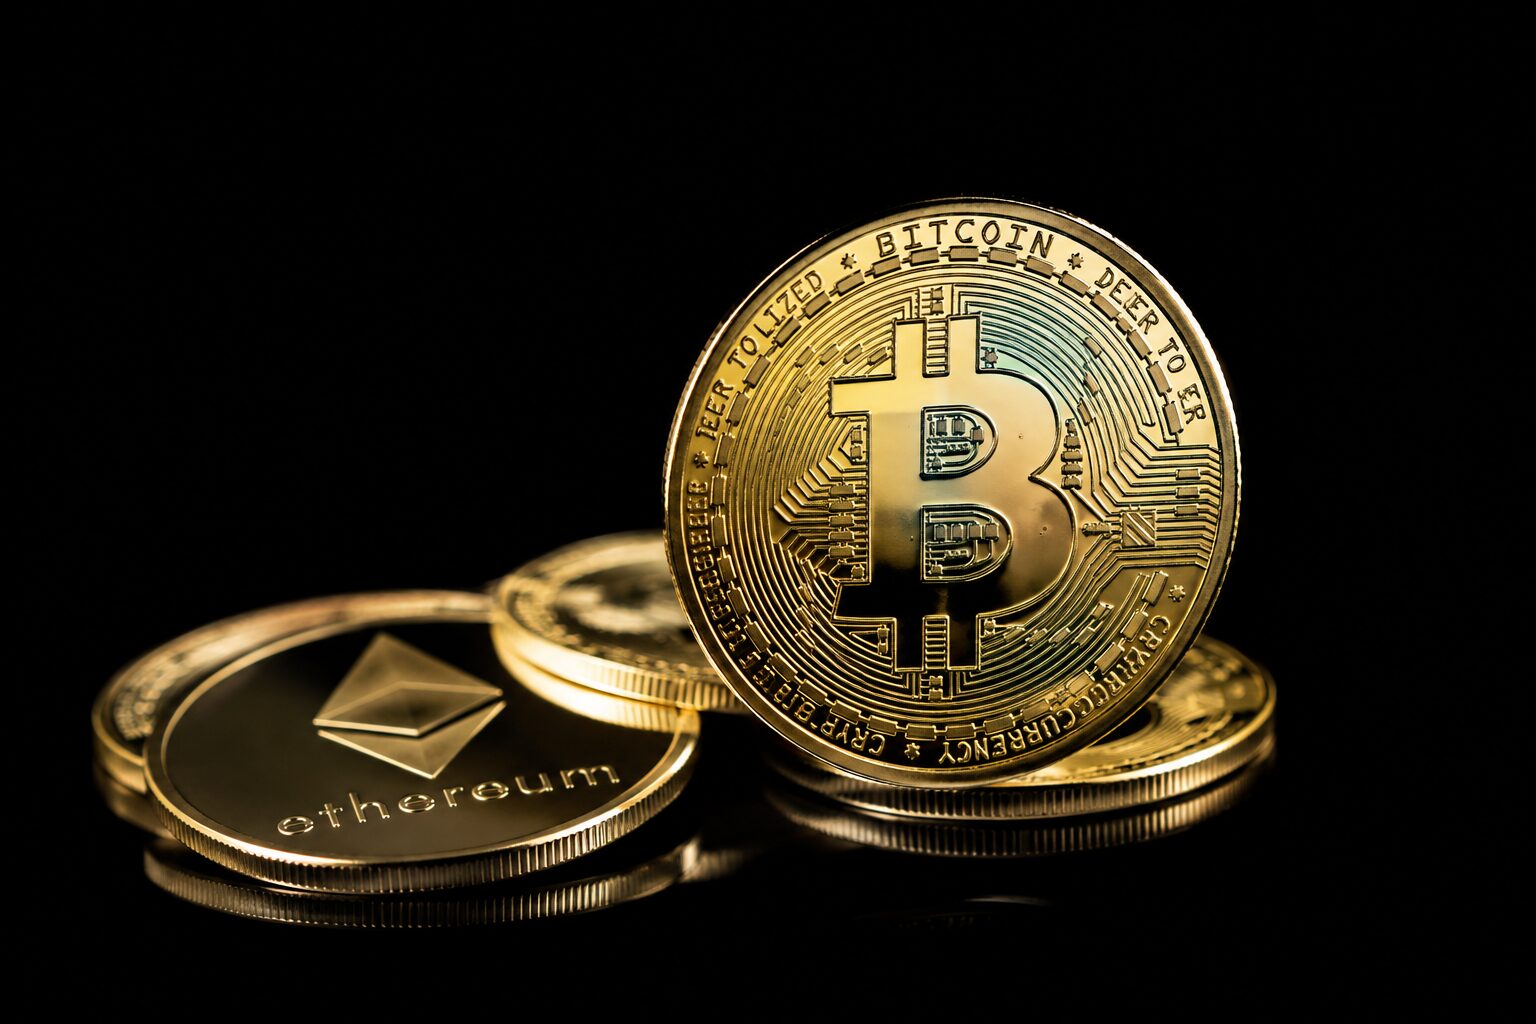
According to the guidelines, the tax obligation arises immediately a cryptocurrency is converted to or from fiat currency within Nigeria, irrespective of what subsequently happens to the digital asset.
Cryptocurrency: NRS applies stamp duty to crypto-to-fiat, fiat-to-crypto conversions
Under the guidelines, stamp duty applies specifically to FIAT-to-TOKEN and TOKEN-to-FIAT transactions under Item 33 of the Ninth Schedule to the Nigeria Tax Act, 2025.
Where a cryptocurrency conversion is processed through a VASP or another recognised intermediary, the operator is responsible for deducting and remitting the applicable stamp duty in accordance with procedures prescribed by the Nigeria Revenue Service.
The NRS further clarified that where a virtual asset is used to settle a transaction that independently attracts stamp duty under the Nigeria Tax Act, the applicable duty on the underlying instrument remains payable.
This means that both the stamp duty arising from the cryptocurrency conversion and any other applicable stamp duty under the Act may apply to the same transaction where separate taxable events occur.
According to the guidelines, the tax obligation arises immediately a cryptocurrency is converted to or from fiat currency within Nigeria, irrespective of what subsequently happens to the digital asset.
“The stamp duty obligation crystallises at the point of the TOKEN to FIAT or FIAT to TOKEN conversion in Nigeria and is not affected by the subsequent transmission of the token to an offshore recipient,” the guidelines state.
Buyers to bear 1.5% crypto stamp duty
The NRS guidelines provide that the recipient of the virtual asset bears the stamp duty in every dutiable transaction.
Rather than deducting the levy from the fiat amount paid, Virtual Asset Service Providers are required to withhold the equivalent of the 1.5% duty in cryptocurrency units from the digital asset credited to the buyer.
Under this arrangement, the seller receives the full fiat consideration, while the buyer receives the cryptocurrency after the applicable stamp duty has been deducted.
The guidelines illustrate the mechanism using a transaction in which a buyer pays ₦1 million to acquire one Bitcoin. A stamp duty equivalent to 1.5% of the Bitcoin is deducted before the cryptocurrency is credited to the purchaser, while the seller receives the entire ₦1 million.
If the cryptocurrency is subsequently sold, the next purchaser will similarly receive the asset net of the applicable stamp duty deduction.
P2P crypto platforms brought under tax framework
The new framework extends beyond conventional cryptocurrency exchanges to include peer-to-peer (P2P) transactions facilitated through supervised intermediaries.
P2P platforms operating escrow services will assume the same tax collection responsibilities as cryptocurrency exchanges.
The guidelines further state that platforms facilitating virtual asset transactions without taking custody of customer assets may still be required to register, report transactions and collect taxes where they qualify as Virtual Asset Service Providers under Nigerian law.
Only genuine wallet-to-wallet transactions conducted entirely outside intermediary platforms will not have taxes deducted at source. In such cases, taxpayers will be required to declare the transactions and pay applicable taxes through annual self-assessment.
Stamp duty separate from VAT, income tax
The Nigeria Revenue Service emphasised that the new stamp duty is separate from other tax obligations that may arise from virtual asset transactions.
According to the guidelines, the transfer of ownership of a virtual asset does not, by itself, constitute a taxable supply for Value Added Tax (VAT).
However, VAT remains applicable to taxable services associated with digital asset transactions, including:
Similarly, where virtual assets are used as payment for taxable goods or services, VAT applies to the underlying supply just as it would if payment had been made in fiat currency.
The guidelines further note that taxpayers who realise gains from disposing of virtual assets may also be liable to income tax under the Nigeria Tax Act.
As a result, a single cryptocurrency transaction could trigger multiple tax obligations where different taxable events occur.
VASPs required to collect and remit taxes
The guidelines fix the applicable stamp duty rate at 1.5% on both FIAT-to-TOKEN and TOKEN-to-FIAT transactions.
Virtual Asset Service Providers and VASP-operated P2P marketplaces are required to collect the duty from the cryptocurrency credited to the transferee, while leaving the fiat value of the transaction unchanged.
Collected stamp duties must be remitted to the Nigeria Revenue Service not later than the 15th and 30th of the month in which the transaction occurred.
New compliance obligations for crypto platforms
Beyond collecting stamp duty, the guidelines introduce broader compliance obligations for participants in Nigeria’s digital asset ecosystem.
Every person engaged in virtual asset activities must register for tax purposes and obtain a Tax Identification Number (Tax ID).
VASPs and P2P marketplace operators are required to make a valid Tax ID a mandatory requirement for opening customer accounts.
They must also deduct applicable taxes, collect stamp duties, account for VAT where applicable, file statutory tax returns and maintain proper transaction records in accordance with the Nigeria Tax Administration Act.
The guidelines prescribe stiff penalties for non-compliance.
VASPs and P2P marketplace operators that fail to comply face a penalty of ₦10 million for the first month of default and ₦1 million for each subsequent month of continued non-compliance.
Additional sanctions apply for failure to register, file tax returns, deduct or remit taxes, maintain statutory records or pay taxes as required.
Nigeria deepens regulation of digital assets
The new guidelines represent one of Nigeria’s most comprehensive efforts to establish a clear tax regime for virtual assets.
By defining how cryptocurrency conversion transactions are taxed and imposing new compliance obligations on digital asset platforms, the framework is expected to strengthen regulatory certainty, improve tax administration and support the continued development of Nigeria’s digital asset ecosystem as cryptocurrency adoption continues to expand.
Stay ahead with real-time reports, breaking news, and exclusive insights delivered directly to your phone. Don’t settle for outdated information. Join TECHNOLOGYTIMES NEWS on WhatsApp for 24/7 updates.
Join Our Whatsapp Channel




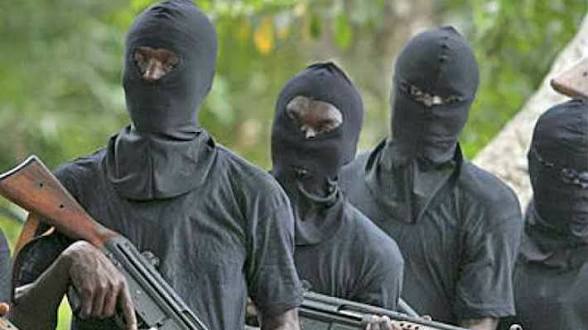
Gunmen on Tuesday attacked vigilantes on duty in Tudun-Mazat village, Barkin Ladi Local Government Area of Plateau State, killing two and injuring another.
Kefas Mallai, a youth leader and the chairman of the Community Peace Observers in Bokkos told Peoples Gazette on Wednesday that the gunmen attacked the security men at about 10:00 p.m.
“At about 10:00 p.m. yesterday, some terrorists attacked the local vigilante on duty at Tudun-Mazat village also known as NTV of Barkin Ladi LGA, Plateau State leading to the death of two local vigilantes and one injured”, he told The Gazette.
According to him, the attacked village is along Bokkos road in the state.
Alfred Alabo, the state police spokesperson, was not available for comment. Text and WhatsApp messages sent to him remained unanswered as of press time.
On August 18, The Gazette reported that gunmen invaded Bin-Per community in Kombum district of Mangu council and killed 23 persons including women and children.
Similarly on June 16, diver miners were killed at a mining site in Gero village, Gyel district of Jos South local council of the state.

-

 News13 hours ago
Nigeria Takes on the World! Chess Stars Begin 2026 Olympiad Battle in Samarkand
-
News1 day ago
Felix Arome Assumes Office as Director-General of Front Line Alliance Network
-
Business3 days ago
CPPE warns against return to petrol subsidy, proposes targeted relief
-
News3 days ago
iPhone Duo vs Galaxy Z Fold8: Inside Apple and Samsung’s different foldable strategies – Technology Times