Business
Cement maker Lafarge Africa renamed HBM Nigeria Plc

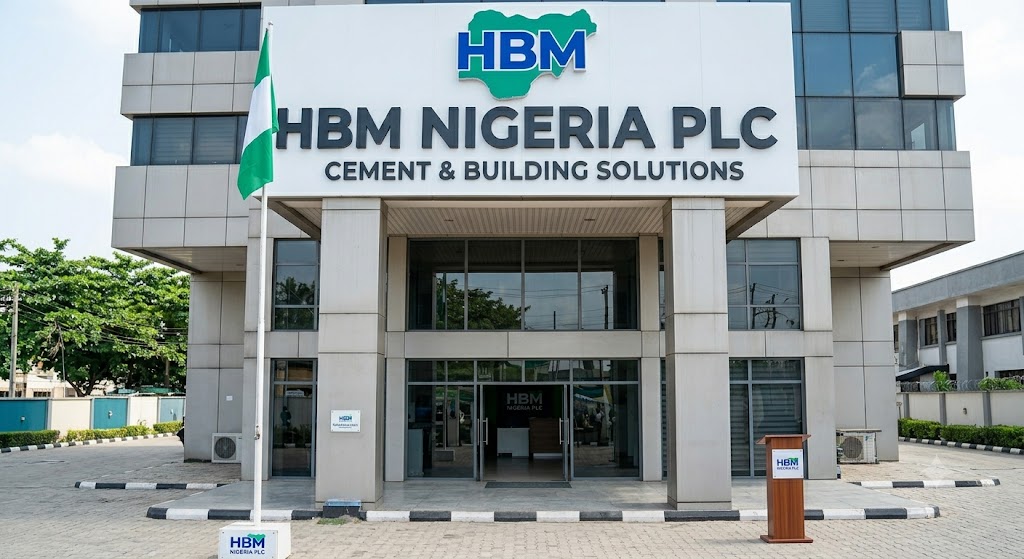

Lafarge Africa, acquired by Chinese investors from the Swiss-based Holcim Group last year, has adopted HBM Nigeria Plc as its new name.
According to a regulatory filing sighted on Tuesday, the cement maker’s new name tallies with the company’s long-term goals and its resolve to better serve stakeholders.
“The name change received full shareholder approval at the Annual General Meeting (AGM) held on the 30th of April 2026,” the company stated in the Nigerian Exchange filing.
“The Corporate Affairs Commission (CAC) has officially approved and issued the Certificate of Incorporation reflecting the name change,” it added.
In December 2024, Lafarge Africa disclosed that the Holcim Group had entered into a share purchase agreement with Huaxin Cement, headquartered in Wuhan, China, to acquire an 83.1 per cent stake in the company.

Until it divested its interest in Lafarge Africa, the Holcim Group held the controlling stake through Caricement BV and Associated International Cement Limited.
Regulatory hurdles, including a Senate directive ordering the Bureau of Public Procurement to halt the transaction last March, meant it was not closed until nine months after it was first made public.
READ ALSO: Champion Breweries appoints new managing director
“We cannot afford to wake up one day and realise that our cement industry, one of the backbones of our economy, is entirely in foreign hands,” said Shuaib Salisu, the senator representing Ogun Central, who raised the motion at the upper legislative body at the time.
The acquisition was valued at $1 billion (approximately ₦1.6 trillion) when the deal closed last August.
The first major expansion project under the new majority owner—a planned capacity increase of the Ashaka Cement plant in Gombe to 2MT and the Shagamu plant to 3.5MT—was announced early this year.
HBM Nigeria assured shareholders in the statement that their current share certificates and electronic holdings remain valid, despite the name change. They will be updated automatically by the registrars, it said.




A new report by Enhancing Financial Inclusion and Advancement (EFInA) has found that Nigeria’s financial exclusion rate has fallen to 21 per cent. However, the remaining gap is increasingly concentrated among people with fewer economic resources.
The finding is contained in the 2026 Access to Financial Services in Nigeria (A2F) Survey launched by EFInA in Abuja on Wednesday.
According to the report, 53 per cent of adults in the poorest wealth quintile remained financially excluded, compared with just 1 per cent in the richest quintile.
It said almost half of financially excluded Nigerians were in the poorest 20 per cent of the population, highlighting the growing link between poverty and exclusion from formal financial services.
EFInA said the findings showed that although more Nigerians were entering and using the formal financial system, greater participation was not translating into improved financial outcomes at the same pace.
The 2026 survey examined financial inclusion beyond access, focusing on financial health, resilience, consumer experience, economic activity and Nigerians’ ability to manage financial shocks.
The A2F Survey has been conducted biennially since 2008 and is one of Nigeria’s major sources of demand-side data on financial inclusion. It tracks how Nigerians use formal and informal financial services to meet daily needs, plan for emergencies, protect their futures and cope with financial pressures.
According to EFInA, the 2026 edition follows previous rounds conducted in 2008, 2010, 2012, 2014, 2016, 2018, 2020 and 2023, providing more than 17 years of longitudinal data.
The organisation said the survey captures financial and non-financial data that have served as a source of information for financial service providers, development organisations, policymakers, and regulators, including the Central Bank of Nigeria (CBN), the National Insurance Commission (NAICOM), and the National Pension Commission.
Methodology
During her presentation of the report findings on Wednesday, Foyinsolami Akinjayeju, Chief Executive Officer of EFInA, said that for the 2026 survey, they had the support of the National Bureau of Statistics in designing it.
She explained that, for the most part, the sampling of respondents was based on equal representation across states.
“Most states have the same sample size, for the most part. In some cases, we adjusted it slightly to account for design effects. This allows for headline indicators to be available at the state, regional and national levels,” she said
Mrs Akinjayeju said they surveyed adults aged 18 years and above and achieved a 98 per cent response rate.
“Our target was 18,950 respondents, and we were able to interview 18,679. So, that’s about a 98 per cent response rate,” she noted, explaining that the results show what is currently obtainable because the listing and data collection were done between April and June, with supervision from the National Bureau of Statistics.
She said the questionnaire was in English but had been translated into the major languages in Nigeria and into Pidgin English.
Digital finance expands
The survey found a significant increase in the use of digital financial services, with digital finance usage rising from about 47 per cent in 2023 to 64 per cent in 2026.
Mobile money use also more than tripled, rising from 12 per cent in 2023 to 38 per cent in 2026.
EFInA said Nigerians were increasingly using mobile money for everyday transactions, including bill payments, purchases and receiving money, in addition to transfers.
However, cash and financial agents remained important, while access to smartphones, connectivity and digital skills continued to vary across population groups.
For instance, 92 per cent of agricultural workers reported that they still received their payments in cash.
EFInA said the findings suggested that a completely digital-only approach to financial inclusion would be premature.
Savings rise, but credit and insurance lag
The survey also showed that formal savings increased from 38 per cent in 2023 to 53 per cent in 2026.
However, formal credit remained at 10 per cent, while insurance penetration stood at five per cent and pension participation at about nine per cent.
EFInA said the figures pointed to a financial system that was helping Nigerians move and store money more effectively than it was helping them finance livelihoods or transfer risks.
“This matters because financial inclusion is increasingly about what people can achieve with financial services, not simply whether they have access to them,” EFInA said.
The survey also highlighted persistent weaknesses in financial resilience. According to the findings, 61 per cent of Nigerian adults remained in severe liquidity distress, while debt stress increased.
Among adults who experienced financial shocks, 71.6 per cent relied on fragile or erosive coping mechanisms, compared with only 13.8 per cent who used protective or adaptive coping mechanisms.
EFInA said fragile coping mechanisms could include responses that help households survive immediate emergencies but weaken their ability to withstand future shocks.
The findings, therefore, raise questions about whether financial services are helping Nigerians recover from shocks without leaving them more vulnerable.
Farmers face financial vulnerability
The survey found that 51.2 per cent of farmers experienced a financial or economic shock.
Among farmers who experienced shocks, 52.2 per cent relied on erosive coping mechanisms, while 76 per cent experienced residual distress.
EFInA said the findings connected agricultural finance more directly with savings, credit, insurance, climate adaptation and the protection of livelihoods.
The survey also examined financial inclusion among women, business owners and young Nigerians.
Formal financial inclusion among women business owners increased from 67.5 per cent to 76.3 per cent, while inclusion among women farmers rose from 42.7 per cent to 53.6 per cent.
However, exclusion among dependent women increased to 52.2 per cent.
EFInA said the findings demonstrated why women should not be treated as a single homogeneous group when designing financial inclusion policies and products.
Consumer experience remains a concern
The survey also examined the quality of consumers’ experiences with financial service providers, including communication, customer support, service timeliness and fraud education.
According to EFInA, the findings showed that greater financial participation did not automatically guarantee an equitable customer experience.
EFInA’s boss said demand-side evidence was critical to understanding how Nigerians interact with the financial system.
“Demand-side evidence at this scale is national economic infrastructure. Nine rounds have given Nigeria a continuous record of how households behave through reform, shock and recovery,” Ms Akinjayeju said.
She said the latest survey went further by examining what financial inclusion was delivering in economic terms.
“I expect regulators, providers and partners to hold their own targets against what it shows,” she said.
EFInA said the A2F 2026 Survey was intended to shift the financial inclusion conversation from simply measuring access to examining what access enables Nigerians to achieve.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.
-

 News22 hours ago
Nigeria Takes on the World! Chess Stars Begin 2026 Olympiad Battle in Samarkand
-
News2 days ago
Felix Arome Assumes Office as Director-General of Front Line Alliance Network
-
Health2 days ago
97% of PHCs in 16 states fail national staffing standards – Report
-
Business4 days ago
CPPE warns against return to petrol subsidy, proposes targeted relief