Connect with us

News

Pile-ins, payouts, and pacing pressure: the investors behind the VCs open up

info

Published

on

Beezer and Amit.jpg

The limited partners who provide the capital to venture firms — the “money behind the money” — are feeling great right now. They’re in uncharted territory in many ways, but also potentially exceedingly lucrative territory.

Normally, LPs typically spread their bets across many firms to diversify their own portfolios. They write checks to emerging managers and established ones, to generalist firms and specialists. The goal is a strong return, but also to minimize risk.

That’s the typical playbook. But typical is out the window. OpenAI and Anthropic’s valuations have shot up so quickly that nearly everyone has piled into the same two companies on the way up, often inside the same venture firm, despite the longstanding venture convention of avoiding investments that conflict with one another. No one is complaining, either. The LPs I speak with seem unbothered by this big gamble, given the potential returns; they’re expecting a bonanza.

But they do see danger ahead, even if they describe this as a “yellow light” situation, and they’re uneasy about how quickly VCs are coming back to raise new funds.

I talked about all of it recently with Beezer Clarkson of LGT Capital Partners, a Zurich-based diversified asset manager, and Amit Bhatti of TrueBridge, a Chapel Hill firm that focuses solely on venture. This conversation has been edited for length.

These are strange days — exciting but also scary. How are you feeling about your roles right now, and your place in this startup ecosystem?

Beezer Clarkson: It’s very busy, but I wouldn’t say it’s scary. There’s a lot of change and a lot of variables at play. I love venture, so I find the chaos fun. I’ve been doing this for a couple of decades, so seeing the cycles makes it less scary. You appreciate that these things happen, and that we should enjoy the upside, because sometimes there’s downside, and the up is a lot more fun than the down.

Amit Bhatti: If anything, it’s exciting. Venture is sometimes looked at as a niche, and now that AI is all-consuming, all the attention is on venture. This feels like our moment more than it is like, “Oh gosh, what’s going to happen?” The pace of investing and the valuations may be different, but really meaningful stuff is happening, and all the attention is focused on this corner of private equity.

Your funds all hold the same brands now, OpenAI and Anthropic, multiplied across however many funds you back, and your job is to keep your institutions diversified. How do you think about that? Obviously it’s great right now, but if things turned, it would be less great.

Amit Bhatti: Venture has always been a power law business, so I actually view the concentration as a good thing. If we were getting to the maturity of one of our funds and there were still lots of tiny positions, something’s gone wrong. Our funds that are 10-plus years old are starting to consolidate into a few names. There’s a lot of Databricks, a lot of SpaceX, a lot of Stripe. In this generation of funds, I would hope there’s a lot of Anthropic and a lot of OpenAI. That’s a feature, not a bug. Not every one of these companies is going to work out, but that consolidation is typical. What’s different is how quickly it’s happened. I don’t view it as an immediate panic signal.

Beezer Clarkson: At the early stage, you still see quite a diversity of opportunity sets, and the dollars are smaller. It aggregates up into the same companies, but early-stage funds obviously aren’t doing the big late-stage stuff, so you have more diversity there, if that’s what you’re looking for.

Funds that invested on four-year cycles have shrunk that to three, then two, then 18 months. Is the pacing okay, or is it concerning?

Beezer Clarkson: We’re seeing funds come back on one-year pacing, which is fast. The norm was probably two to two and a half years. Some funds are deploying much faster because they’re taking concentrated, big-check positions. That could be a worrisome sign. It could work out, we don’t know, but it’s typically harder to do a one-year vintage and get it right.

Amit Bhatti: Similar for us. I would have said 24 to 36 months was roughly normal. Now 12 to 18 is not crazy for some of the funds going really quickly. A lot of funds are bumping up their fund sizes mid-cycle, which is definitely unusual. That’s partly because rounds have gotten so large. If Anthropic is raising a giant quantum of capital and you put 20% of the fund into it, you’re obviously going to be ahead of pace. Seed round sizes have gone up almost 2x, too, so if you want to lead, you’re writing 2x the check. It’s definitely a yellow light. It gives us a little bit of heartburn.

But when we look at what these managers actually bought, the numbers are different. The last time we had accelerated pacing, there was a lot of investing in zero-revenue crypto moonshots. Now we’re seeing a lot of companies go from zero to $100 million in revenue, which was totally unheard of before.

If you’ve got a great manager who comes back every year but the returns are still on paper, can you say “call me next time,” or do you lose your seat at the table?

Beezer Clarkson: It’s very hard to leave a manager and then come back. It happens, but it’s more typical to downsize your check. In 2021, a lot of LPs said, “If I was going to give you $10 million, I’ll do $5 million, because $10 million was for two years.” In our portfolios, the pacing gets pulled through, so we think about our pacing as well as yours.

Amit Bhatti: Same here. We’re building out a calendar of when we expect to make commitments, so if someone goes way off that map, we need to make sure the capital is there. You see people downsize or communicate it up front. It’s hard to say you’re sitting it out altogether, because then you’re not reliable capital. That’s also why you’re seeing upsizes; managers don’t want to come back and say they’re raising a whole new fund, so they bump up the old one.

Beezer Clarkson: People also rotate out of venture sometimes because capital calls keep running with no distributions coming back, and they still have to meet operating commitments, whether it’s the endowment, the hospital, or the foundation. That puts a lot of strain on those situations.

LPs like time diversification, yet a lot of funds were raised in recent years, including that backed startups at high valuations during the pandemic. How are those funds doing, and how would you describe 2026 so far?

Beezer Clarkson: The 2021 vintages are still early, five years in, but they argue against doing one-year funds. Some will catch a piece of an AI company and look excellent, but your odds of getting it right in one year are just tougher, and the valuations were extreme.

Amit Bhatti: If I look at the last 15 years of our portfolio, I wouldn’t bet on the COVID vintage being the best one. But a couple of breakouts will come from it. OpenAI was around in that era, and Cursor started pretty far back, so they’re in some of those funds. And liquidity has started flowing. The past two years were definitely slower, but SpaceX is the headline, Cerebras was a big exit this year, there have been a couple of other IPOs, and a lot of M&A. We’re seeing $10 billion-plus M&A exits, a $60 billion one [with Cursor]. Liquidity is going beyond just IPOs.

How are your venture fund managers thinking about secondaries? If I were a VC, I’d have been tempted to take money off the table in OpenAI or Anthropic.

Beezer Clarkson: Secondaries have become much more sophisticated in venture over the last, call it, five years. It’s localized in the top handful of companies, but it’s much more prevalent than before, which I think is good, because the ecosystem needs liquidity options. Venture is predicated on that, and if you wait 20 years for an IPO, that is not what structurally we all thought it could be. They’re also happening at multiple levels now. LPs sell stakes of their GPs, a strip of their portfolio, and the taboo around it is less.

Amit Bhatti: It’s the third leg of liquidity now: IPOs, M&A, secondaries. Private equity has always had a well-developed secondaries market, and venture didn’t. It was kind of a dirty word. You were only selling if you were distressed. Then people were holding the bag in 2021 and thought, “I should have sold.” Now more managers use it as a tool, and more judiciously. If you still believe it’s the power law company, you’re probably not exiting the whole position. But if you can sell 20% of your position and return your fund, you should probably do it.

There’s a lot of founder selling and employee tenders — often very early into the company’s “journey.” How do you feel about that?

Amit Bhatti: We were talking before about the analogy to crypto, where things got very difficult in part because employees were paid in tokens that were liquid immediately. What’s your motivation to stick around when things get hard? So I think it’s great that there are employee tenders, especially for companies that have been around a long time, like Stripe and Databricks, with a very clear financial picture. For them to offer partial liquidity to employees is totally reasonable. But a lot of the enforcement falls on the lead investors. Investors we back have told companies, “We don’t want you to do an employee tender right now.” Those conversations are happening behind the scenes, and people have learned some lessons from last time. It’s all based on leverage, though. If the founder has incredible leverage . . .

Forget it.

Amit Bhatti: Yeah.

When these companies go public and employees get liquid, will they become partners or competitors to your venture managers? These employees have amazing networks.

Beezer Clarkson: We’ve seen it multiple times: when a company becomes very productive, employees can become LPs or GPs themselves. It’s entirely possible there’ll be a whole new raft of emerging managers backed by people coming out of OpenAI and Anthropic. It happened in the Google days. But being an LP means signing up for many millions of dollars and a multi-decade business.

Amit Bhatti: The real estate part [given the soaring cost of home prices in San Francisco] is going to be tough. But those people stay in the ecosystem, investing in others, building new companies, starting new firms. That’s why no other place is taking SF’s place anytime soon.

Housing costs here in San Francisco have shot up so fast. Do we price out the next generation of founders, and does the next hub end up in New York or somewhere else?

Beezer Clarkson: History would argue that the density effect in the Bay Area is a great pull. Maybe it moves out of San Francisco and back into the suburbs. Back in the day, YC was in Mountain View. New York obviously has its own very deep tech scene, but there’s such a density here that it’s been really hard to push back against.

A handful of venture funds now lock down most of the committed capital from limited partners. Is there a wedge in for emerging managers?

Beezer Clarkson: There are still first-time and emerging managers, funds one through three, being raised this year, last year, the year before. You still need a differentiated point of view, a reason for being. Fundraising has gotten harder, but we see them being funded, and the fund sizes are just smaller. Fifty percent of the money might go to the big funds, but if your average first fund is $25 million to $50 million, there can still be enough of those to add up to $1 billion.

Amit Bhatti: There are people raising $5 million or $10 million right here in SF, maybe formalizing their angel investing. A lot of really well-known funds started with a $5 million fund. It’s much better for an emerging manager to build the track record, prove out the thesis, your access and your judgment with whatever capital you have, and then fund two will be easier to raise. If you try to raise $50 million or $100 million on day one, you’re creating a giant hill to climb.

Beezer Clarkson: If you’ve only angel invested, that’s a different story from spinning out of a platform where you have an installed base of LPs who know you. Those managers typically raise more.

Can you talk about specific kinds of emerging managers you’ve backed, and what made you write the check?

Amit Bhatti: People define “emerging” very differently. We’ve backed founders who are still running their companies and investing on the side. We’ve backed people leaving a bigger firm for something earlier. And we’ve backed extremely young GPs, 22 and 23 years old, who have really close access to the next generation of AI-native founders. They started an accelerator program at MIT, Harvard, and Stanford, and the first couple of batches had Cursor and Mercor in them. They’re young, but they’re around an incredible density of talent. The VC job is sourcing, picking, winning, and they did a pretty decent job of picking when there was no money involved. Success begets success in venture, so we were happy to give them a shot.

Beezer Clarkson: There’s much more flexibility now. I remember a time when an LP wouldn’t fund somebody who had a job and was also investing, and people are open to that now. I’ve been investing in emerging managers, along with established ones, for 14 years, and they run the whole gamut, from an operator-turned-investor raising $10 million, to a spinout raising a few hundred million [dollars]. It’s interesting when they’re still operating, because it gives them insights. The trick is whether they’re doing what they need to do to win the right to be on the best cap tables.

Amit Bhatti: Especially early stage, there’s no one-size-fits-all. You can be part-time, you can be diversified, you can be concentrated. There are more outs in the deck, if you will, for returning something that’s small and experimental.

What’s the smallest check you’ll write to a fund, and how much of a fund will you take?

Beezer Clarkson: Given our program, it’s hard to do less than $5 million. I’ve generally taken the view that if you’re [representing] too much of a fund, there are challenges for the GP going forward, so I’d want to be no more than 20%. There are situations where I’d consider more.

Amit Bhatti: Three to five million for us, and on occasion smaller in very specific scenarios. We don’t really care about concentration if it’s the right scenario. We’ll do half or all of it. But Beezer’s right that it’s not ideal for the GP, and we tell them up front to diversify their LP base. We’ve done a fund where we were half the capital, and the next fund we were closer to 20%, because they did well.

When you purchase through links in our articles, we may earn a small commission. This doesn’t affect our editorial independence.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

News

Plateau Igbo Community Ends Leadership Crisis, Elects Johnson Nwosu as Eze Igbo IV

info

Published

on

IMG 20261101 WA0008

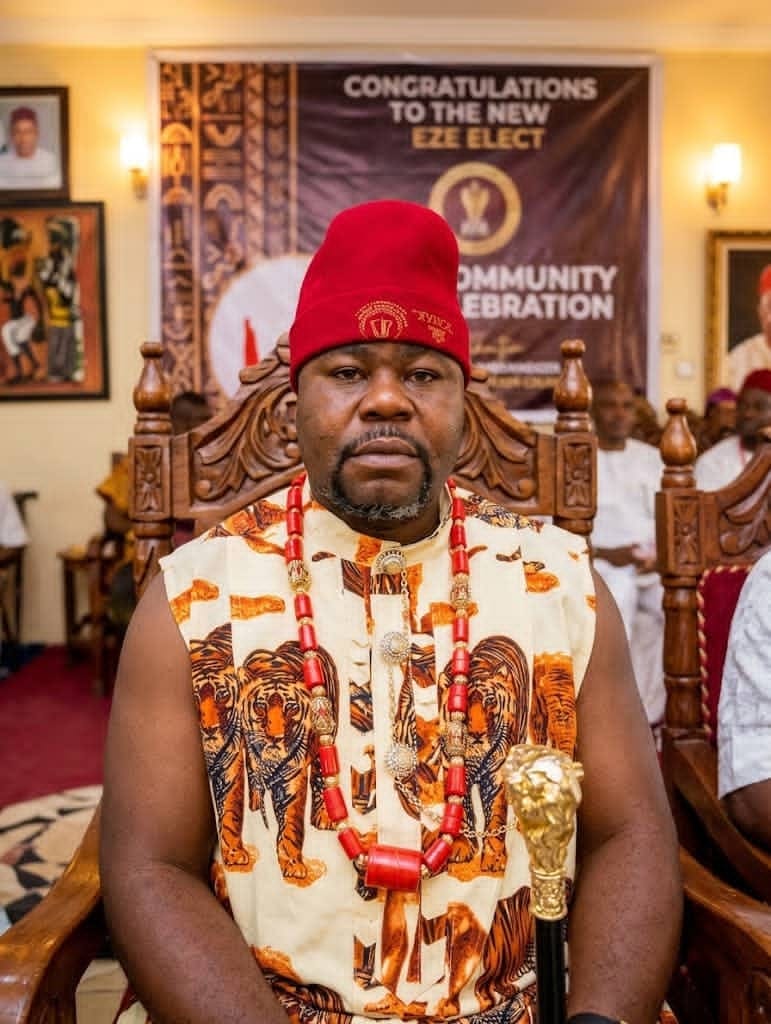
Chief Johnson Nwosu has emerged as the new Oche Ndi Igbo IV of Jos, Plateau State, after winning the Igbo Community Association (ICA) election held on Saturday, October 31, 2026.

New Eze Igbo Jos, HRH Johnson Nwosu Emerges New Oche Ndi Igbo IV Jos in Plateau

Nwosu secured a landslide victory with 210 votes, defeating Dr. Friday Uche Obiora, who scored 3 votes, and Okonkwo, who polled 1 vote.

The peaceful election is expected to bring an end to years of internal leadership crisis within the Igbo community.

The new leader has pledged to unite the community, promote peaceful coexistence and strengthen its contribution to Plateau State’s development.

The official coronation and presentation of the staff of office will hold today, Sunday, November 1, at Jossy Royal Hotel, Jos, amid celebrations.

New Eze Igbo Jos, HRH Johnson Nwosu Emerges New Oche Ndi Igbo IV Jos in PlateauIMG 20261101 WA0004  IMG 20261101 WA0005 New Eze Igbo Jos, HRH Johnson Nwosu Emerges New Oche Ndi Igbo IV Jos in Plateau IMG 20261101 WA0009

Continue Reading

Health

EXCLUSIVE: Ebola: 34-year-old pilot, wife identified as suspected cases who tested negative in North-east Nigeria
info

Published

on

Doctors handling an Ebola case 1.jpg

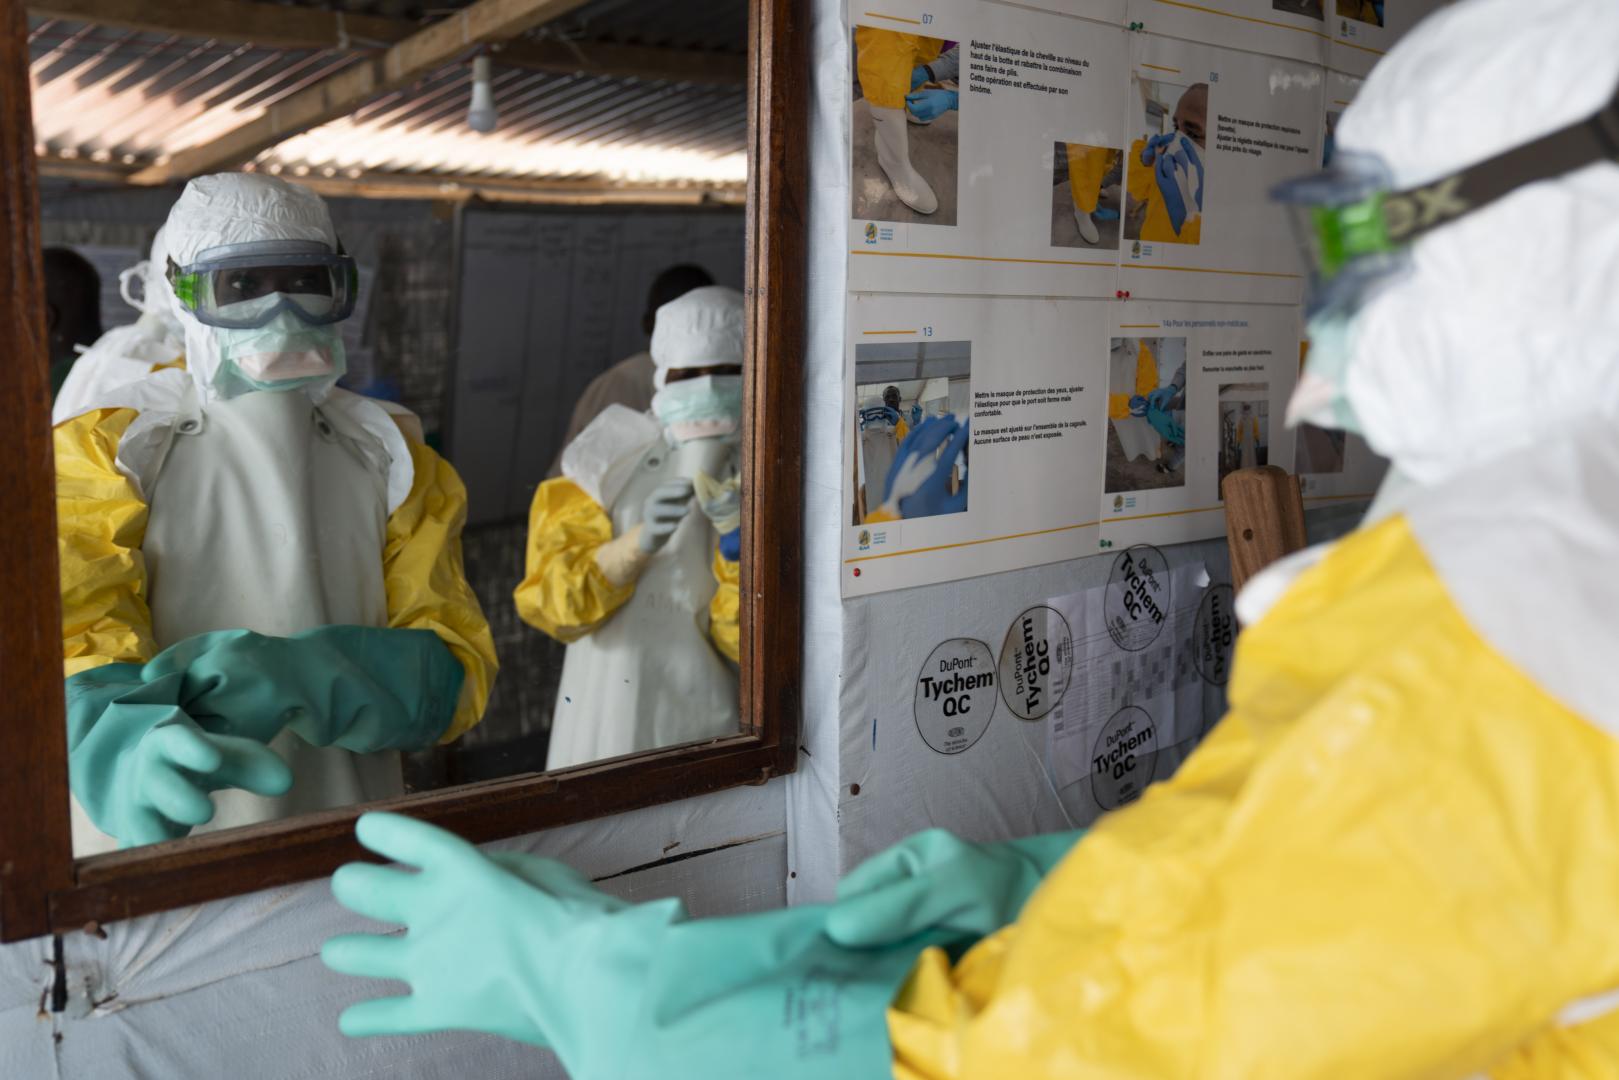
A 34-year-old pilot and his wife, a medical doctor, were the two people investigated for suspected Ebola Virus Disease (EVD) in Adamawa State after developing symptoms including fever, vomiting, fatigue, headache, cough, bleeding gums and nosebleeds.

Although Nigerian officials said two suspected Ebola cases were being investigated in the state and eventually turned negative, their identities were not disclosed. PREMIUM TIMES can now disclose the officials’ identities, though we are redacting their names.

An internal memo from the Adamawa State Ministry of Health and Human Services, obtained exclusively by PREMIUM TIMES, said the couple were admitted to the isolation centre of the Modibbo Adama University Teaching Hospital (MAUTH), Yola, on 29 October.

The memo, dated 30 October 2026 and signed by the State Epidemiologist, Jones Kadabiyu, said the Adamawa State Public Health Emergency Operations Centre (PHEOC) received the report at 6:45 a.m. following a clinician’s report from MAUTH.

The development came as health authorities intensified surveillance following Nigeria’s confirmation of its first Ebola case in the current outbreak.

The Nigeria Centre for Disease Control and Prevention (NCDC) had on Saturday announced that two suspected Ebola cases had been identified in the North-east, but did not initially disclose the state where the cases were detected.

PT WHATSAPP CHANNEL
Dangote Refinery AD

However, the agency later confirmed that the two suspected cases were in Adamawa, noting that the laboratory tests on samples from both individuals were negative for Ebola after two rounds of testing.

In a statement signed by its Director-General, Jide Idris, the NCDC said it was working with the Adamawa State government to investigate the suspected cases.

The agency said it isolated the two individuals and immediately activated public health measures while collecting samples for laboratory testing.

“Fortunately, the samples turned out negative for EBV after two rounds of testing,” Mr Idris said.

The NCDC said there is currently no laboratory-confirmed Ebola case in Adamawa State, adding that the previously confirmed case in the Federal Capital Territory (FCT) remains the only confirmed case in Nigeria.

What PREMIUM TIMES learnt

According to the memo, the pilot developed symptoms on 13 October, while his wife developed similar symptoms on 25 October.

The names of the two patients are contained in the documents seen by PREMIUM TIMES. However, this newspaper is withholding their identities to protect their privacy.

A preliminary report dated 31 October from Yola North Local Government Area (LGA), Adamawa State, said the pilot travelled to Kenya “for personal reasons” on 14 October and returned to Nigeria on 25 October. It said he had developed a fever before his trip and was treated for malaria.

“Prior to his departure, he reportedly developed a fever on 13 October 2026 and was treated for malaria. He reportedly remained well while in Kenya,” it noted.

However, upon returning to Yola, he developed symptoms including fever, nausea and vomiting, fatigue, headache, cough, bleeding gums and nosebleeds. His wife subsequently developed similar symptoms after caring for him at home.

They were both admitted at the MAUTH isolation centre.

The state health authorities collected samples from both patients on 30 October and transported them to the National Reference Laboratory for testing, according to the report.

Contacts traced

The memo report said 18 contacts had been identified, traced and line-listed, while the preliminary report dated 31 October put the number at 17.

The PHEOC also notified the State Rapid Response Team, the State NCDC office, Local Government Disease Surveillance and Notification Officers, the World Health Organisation (WHO) and UNICEF.

The state health authorities recommended continued contact tracing, infection prevention and control measures, enhanced surveillance and coordination with relevant authorities.

The NCDC has urged Nigerians to remain calm and avoid spreading unverified information.

It also advised people who develop symptoms such as fever, severe weakness, headache, muscle pain, vomiting, diarrhoea or unexplained bleeding, particularly after a relevant exposure, to seek immediate medical attention.

READ ALSO: Ebola: Saudi Arabia suspends travel to Kenya, halts visa issuance

Ebola outbreak

Nigeria is one of five countries that have detected Bundibugyo virus disease during the current outbreak, which began in the Democratic Republic of the Congo (DRC) in May.

The outbreak has remained concentrated in the DRC but has spread beyond the country.

Nigeria’s first confirmed case of Ebola in 2026 was a woman who travelled from Uganda to Abuja and tested positive on 20 October. She was subsequently medically evacuated to Switzerland for continued treatment.

The NCDC’s latest situation report said 62 contacts linked to Nigeria’s confirmed case had been identified and were being monitored.

The Coordinating Minister of Health and Social Welfare, Muhammad Pate, had said genomic analysis showed that the virus detected in the Nigerian patient was closely related to the strain identified in Kenya’s first imported case. He, however, said the finding did not establish that the Nigerian patient was infected in Kenya.

WHO’s latest update reported 10,274 confirmed cases and 4,992 deaths in the DRC as of 28 October. Kenya had recorded nine confirmed cases and two deaths, while Nigeria had one confirmed case at the time of the update.

Ebola is a viral disease that can cause severe illness and spreads mainly through direct contact with the blood or other body fluids of an infected person.


Discover more from Premium Times Nigeria

Subscribe to get the latest posts sent to your email.

Continue Reading

Trending