Connect with us

News

Insight Partners’ Deven Parekh on why the firm is diversifying while everyone else bets the farm on OpenAI and Anthropic

info

Published

on

Deven Parekh.jpg

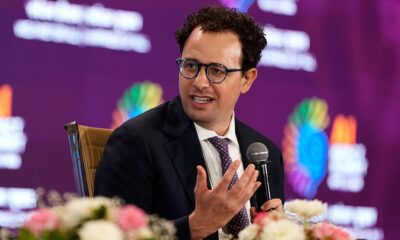
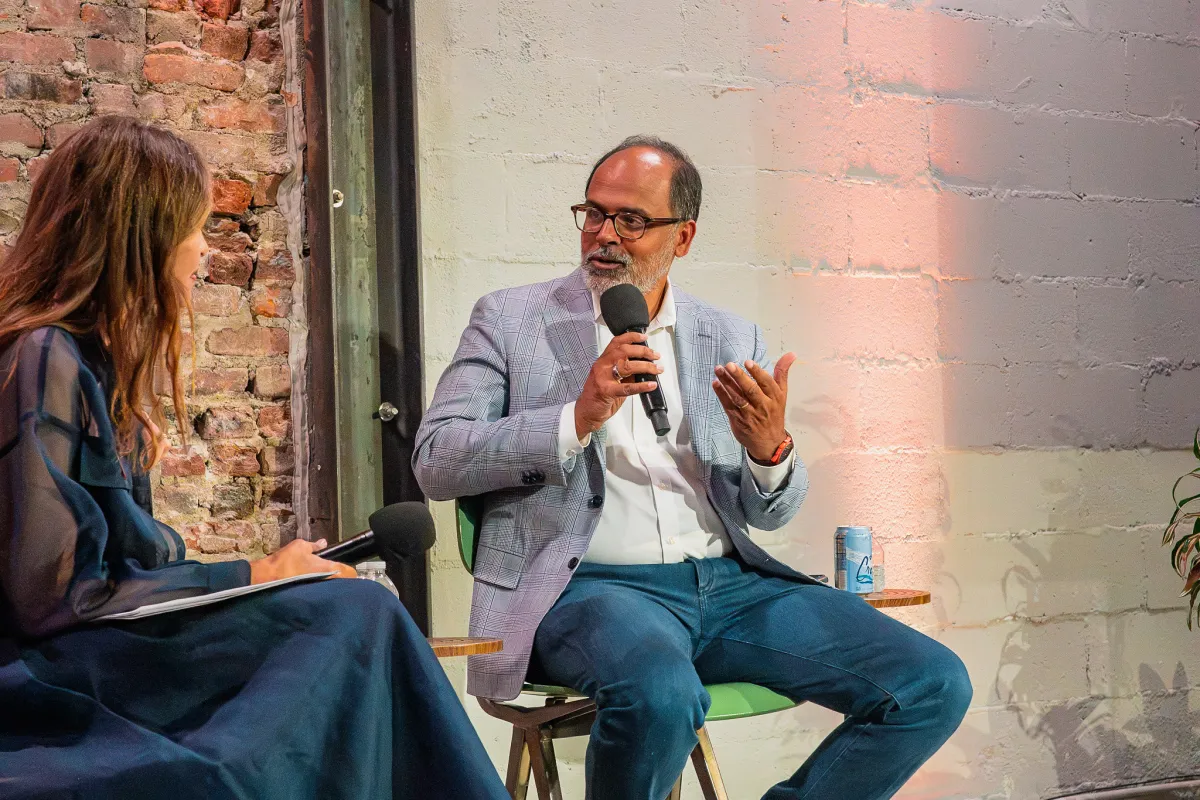
Deven Parekh has co-run the heavyweight investment firm Insight Partners for 26 years. Unlike many VCs who are loud on X and seem to live on podcasts, Parekh and Insight Partners tend to lay low.

In this sit-down with TechCrunch at its StrictlyVC event on Thursday night in New York, Parekh was refreshingly candid about some of the firm’s wins (it has led and co-led numerous rounds in Databricks, for example, and owns stakes in OpenAI and Anthropic); the deals it hasn’t won, including buzzy AI legal-tech company Legora; conflicts of interest in venture investing; and why Insight has stuck to a diversified strategy even as VCs have piled into the frontier AI labs.

This interview has been edited for length and clarity.

There’s a researcher who’s become the big story of the week — do you think that concerns about AI risk amount to hysteria, or do you have real concerns?

Sure, there’s a risk some non-state actor gets access to an open-source model and creates a biological weapon. But there’s an even higher probability we get a massive decrease in the time it takes to develop new drugs and cure diseases. I’ll take that bet.

I’m on the board of NYU Langone — what AI is already doing with patient data is amazing. We can look at 50 million patient records and tell someone walking in for something unrelated that they have a 25% chance of a heart attack. Net-net, I think this is highly positive.

There are risks, sure, just like there are risks with next-generation drone warfare. Every generation has new risks, and somehow, over time, the world still raises living standards. We’re going to need AI to scale healthcare — the population is aging and there aren’t enough medical professionals to go around.

Insight has $90 billion in assets under management but seems comparatively quiet compared to firms of similar size. Is that purposeful?

Every venture capitalist thinks they’re an expert on everything now — epidemiology during COVID, geopolitics during the Iran war. I’m not sure we’re all experts on everything. Our attitude has been: Let the portfolio do the talking. We’re investing in founders and companies. We have to communicate enough that people know who we are, but our performance should speak for itself — and that’s driven by the portfolio, not by us being loud.

You do early-stage, growth, buyouts, and presumably secondaries. What’s the split?

It’s temporal, not fixed — we invest globally, so there’s no set geographic or strategy allocation. Look at our last seven funds and you’d see different percentages of early-stage, growth, and buyout in each. Buyouts aren’t great right now — rates are high, debt markets aren’t receptive to software, exit multiples have come down. We haven’t done a major buyout since 2024.

On the venture side, valuations are rising at a pace we saw before, in 2021 — and that didn’t end well. Normally, a follow-on round means more data, so you pay a higher price for lower risk. Right now, rounds move so fast there’s almost no incremental data, so you’re paying more without reducing risk. The logical response is to go earlier. With a scale fund, you can make smaller bets — write a $20–25 million check instead of $500 million — and double down on the winners. That’s where our returns have disproportionately come from. With Wiz, we wrote a Series A and kept writing checks, so our gain was much larger than if we’d stopped at the first check. And if Wiz hadn’t worked out, it would have barely dented a fund our size.

As a global investor, what percentage of your deals are regional versus concentrated somewhere like the Bay Area?

Talent has gone flat globally. We competed for Legora — my partner Jeff Horing flew to [Stockholm] to pitch the company, because that’s where the founder was. We lost that one to General Catalyst.

That said, AI infrastructure talent is genuinely concentrated in San Francisco — my 23-year-old son, also a VC, is moving there because he says you can’t invest in AI without being there. But talent density varies by vertical: Ramp is financial services, and that talent is concentrated in New York. So vertical AI investing can be more geographically diverse than pure AI infrastructure.

Why did you lose Legora to General Catalyst?

I don’t know the specific reason, but I think they sold their value proposition better than we sold ours that time. There are plenty of examples where it went the other way. It’s a big world; we don’t need to win every deal.

You’re invested in rival companies — OpenAI and Anthropic. That was once taboo in VC. Did that cause any anguish inside the firm? Did you worry about what founders would take away from this?

The internal debate was more about whether we should have gotten into earlier rounds. It’s very stage-dependent. Khosla did OpenAI’s Series A, and there’s no way they could have then invested in Anthropic, and if we’d done Anthropic’s Series A, we likely couldn’t have done OpenAI either. Once you’re at a later stage, off the board, not driving governance, you’re just buying a great stock.

We saw OpenAI as the dominant consumer play and Anthropic as having a clear enterprise strategy; that’s shifting in real time. As these companies needed to raise $30–$100 billion, they stopped being able to dictate exclusivity. That said, at the Series A/B stage, we do have information-sharing restrictions and we don’t invest in directly competing companies, though some founders are sensitive even to 2% revenue overlap.

Are you getting more aggressive on physical AI?

Physical intelligence companies are still largely science projects. It’s not that they won’t become real businesses, but you’re making a bet on when robotics adoption happens, layered on top of a bet on whether it happens at all. We’re watching, but we’re not there yet. My son thinks it’s the hottest space around and that I’m crazy to ignore it, which is exactly what I’d expect from a 23-year-old.

OpenAI and Anthropic raised roughly half of all VC dollars in the first half of this year. Do you think LPs worry about concentration risk?

We’re not overly concentrated, so it’s not an issue for us. But I’m an LP in other funds, and I know two funds right now — raising their entire fund in a month — whose pitch is literally “35–40% of this fund is going into one of those two companies.” I’m not saying OpenAI and Anthropic won’t do well. But this business has always rewarded diversification over a long horizon. We’re on fund 13, so we have to think in terms of ten funds, not one.

In this particular moment, if 25% of our fund were in Anthropic, our returns would look better. But data over time doesn’t support excessive concentration, and most LPs don’t want that exposure either — though firms like Founders Fund and Thrive have done very well running concentrated strategies. There are always going to be exceptions who execute that well.

Secondaries are attractive right now, given how much capital was raised in 2021–2023. How are you thinking about these?

The bigger issue is a lot of funds raised a lot of money and haven’t returned any of it to LPs. Many first- and second-time funds won’t raise a next fund because they didn’t prioritize liquidity. I tell fund managers I advise: if Anthropic’s going to triple from here, fine — take your basis out anyway. LPs want to know you can turn positions into cash; that’s the job.

We were guilty of this early on, too. As one of the biggest LPs in most of our own funds, we’d think, “Why sell if it could double again?” But LPs don’t get paid that way. Over the last two years we’ve returned more than $20 billion to LPs through strategic sales and IPOs, with a few billion more coming. DPI matters, even on fund 13. Secondaries are really a liquidity mechanism, often for early venture investors more than employees. Nobody complains about a 10x that stays a 10x, but if it drops to 5x, people ask why you didn’t sell.

VC Elad Gill has argued there’s a narrow window — maybe 6 to 12 months — where a company’s valuation will never be higher, and founders should sell into it. Do you have that conversation with your founders?

We’re always having that conversation, though founders listen to me about as much as my kids do. It’s case by case, but when a founder gets an offer at a frothy valuation, I ask them what happens when the market corrects, because it will, even if I can’t tell you when. If I could time it, I’d be on an island managing my portfolio, not talking to you. You don’t have to sell everything; de-risk 10 or 20%.

Right now valuations are rising so fast people assume the trend continues, but you can’t compound $40 billion at 50% every two months for two years without becoming the world economy. That math doesn’t work.

Anthropic will likely file to go public soon, with OpenAI presumably behind it. What does that IPO mean for the industry?

Anthropic is already larger than Salesforce and it’s four years old — the fact that they can go public doesn’t necessarily mean much for everyone else. You’ll have three companies — SpaceX, Anthropic, OpenAI — going public within six to eight months, each north of a trillion dollars in market cap, and the market absorbed SpaceX just fine. The real question is when the next tier of companies goes public, and what bar that sets. If you’re a public-market investor watching something go from zero to $65 billion in four years, “double, double, triple, triple” no longer looks that exciting by comparison. But that 10x growth rate can’t continue forever. Eventually even these companies become normal-growth companies, and you need public markets for that. I think we’ll see more of these IPOs over the next 18 months.

With so much capital locked up, will all this LP money finally flowing back sustain the frenzy?

We all do this in our personal lives — stay out of an expensive market until we can’t stand it anymore, and pile in right when we should be pulling back. LPs do the same thing at a macro level; everyone wanted in before 2021, pulled back after, and now the same LPs are piling back in. That boom-bust cycle is hard to avoid. Venture-growth funds of $6 to $10 billion used to be rare; now they’re common.

How long do you give a company with a bad cap structure before deciding whether to double down or walk away?

It varies enormously. Wonderful [an enterprise AI agent platform] was created less than two years ago; we did two rounds and it’s now at a $5 billion valuation — a very fast double-down. On the other hand, some 2021 investments went nowhere for three or four years before finding product-market fit. That’s part of why we do portfolio reviews — we recently went through 300 portfolio companies over three days, checking not just on the big positions but looking for the ones showing an inflection point worth doubling down on, buying secondary in, or in some cases pulling back from.

Our best example is Armis, a security company. We lost the initial deal to Sequoia, but my partner kept the relationship alive with a $5 million check out of an $11 billion fund. Eighteen months later, we bought out the entire cap table, including Sequoia, for a nine-figure check, and sold it to ServiceNow this year for $7 billion. Sometimes you make money with small checks, sometimes with big ones. The goal is finding the best founders in the best markets.

When you purchase through links in our articles, we may earn a small commission. This doesn’t affect our editorial independence.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

News

RHYE EMPOWER PLATEAU STUDENTS WITH LAPTOPS AS SEYI TINUBU VISITS JOS

info

Published

on

67f5364d 3caf 4662 87e7 339d75969075.jpeg


Views: 37

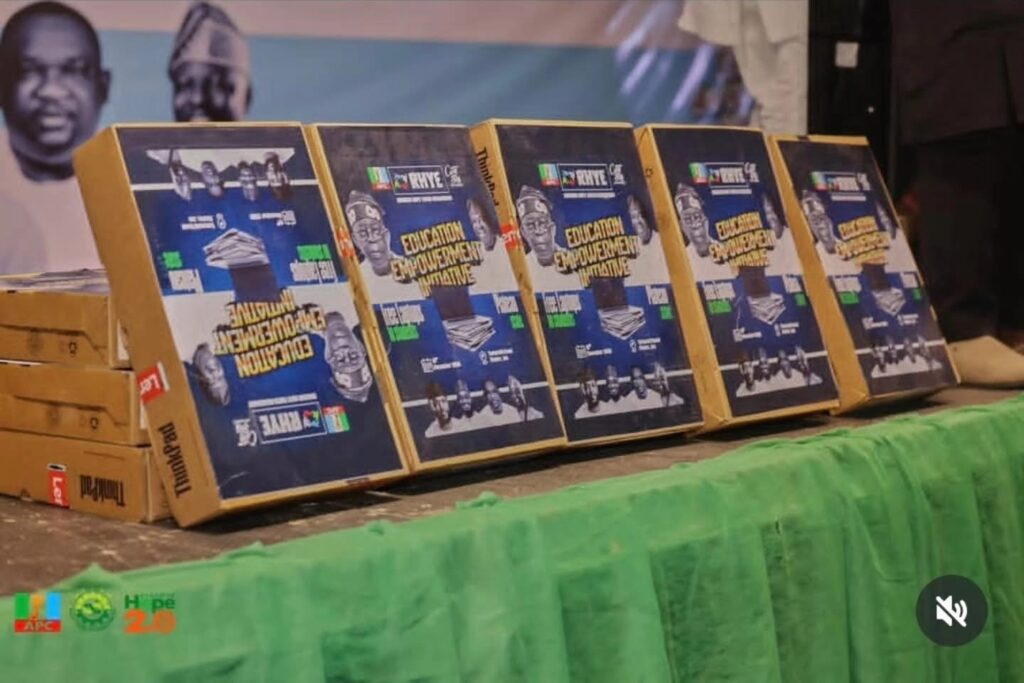
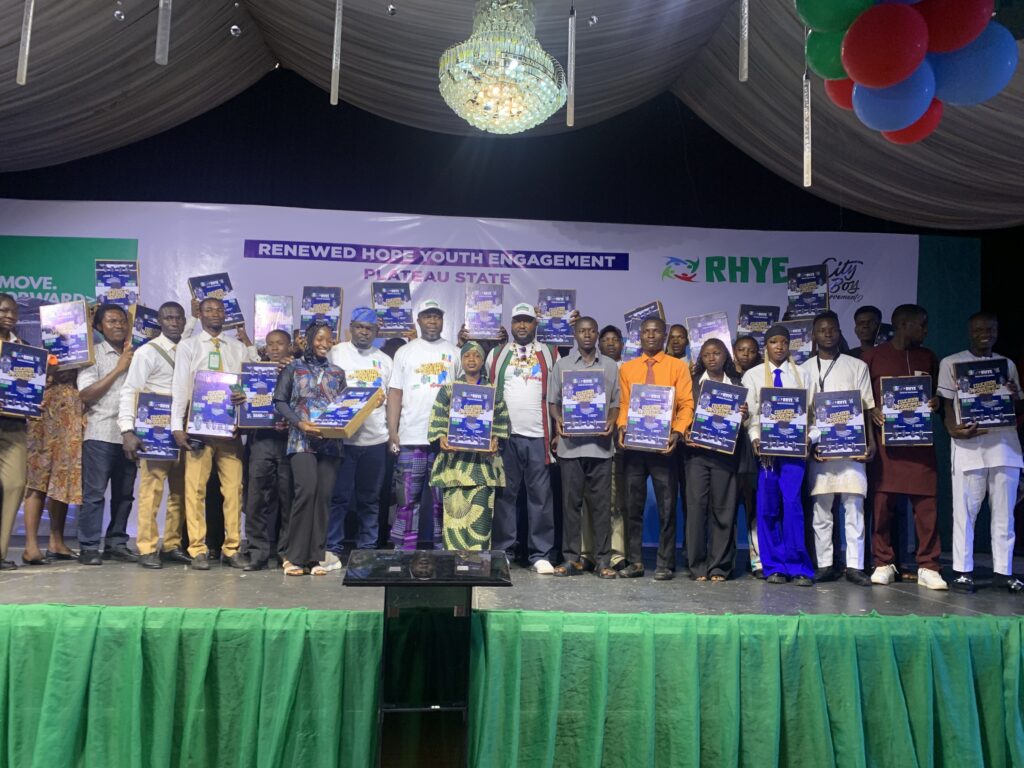
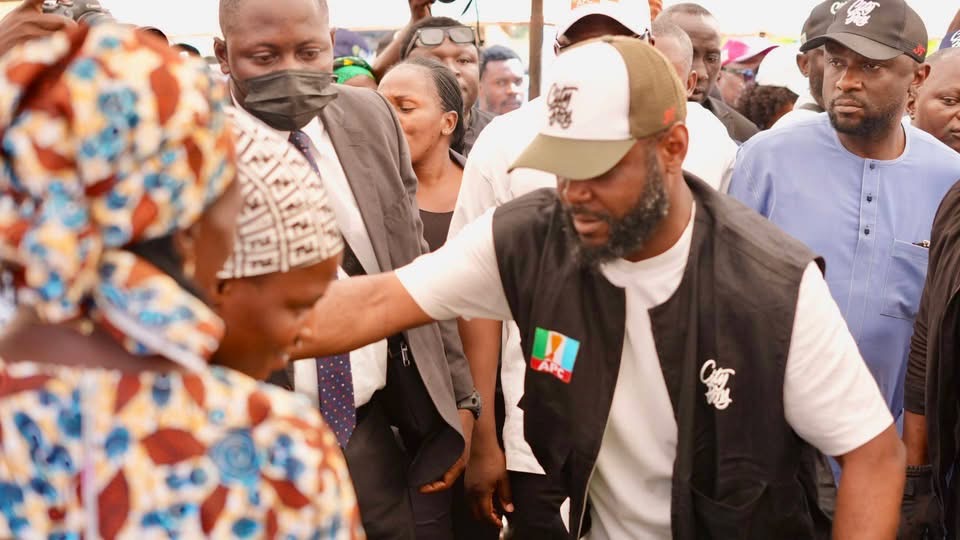
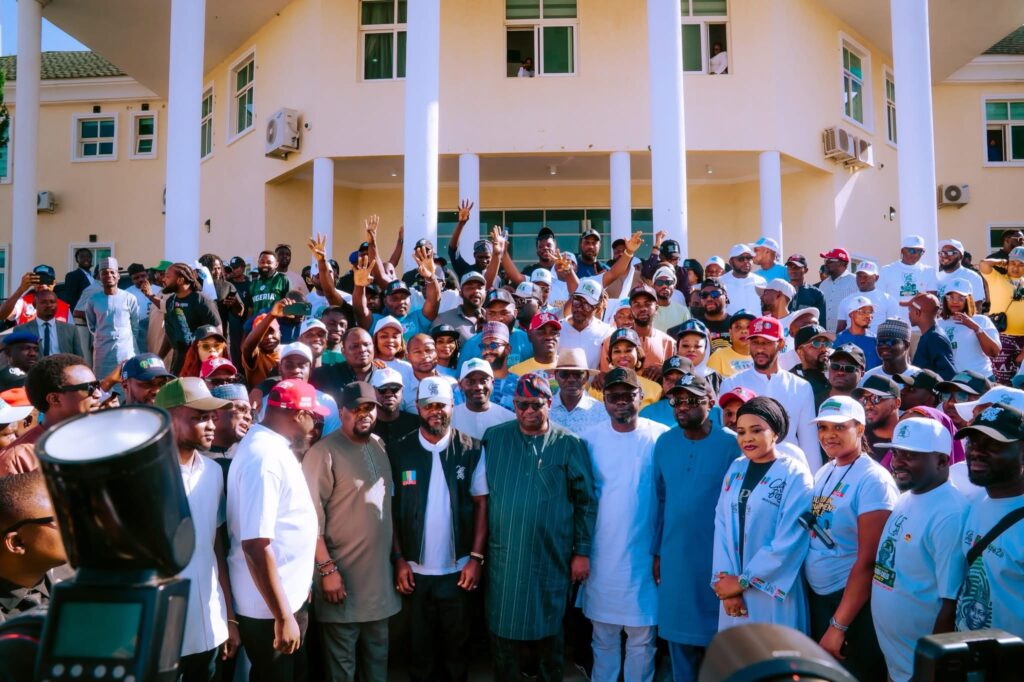
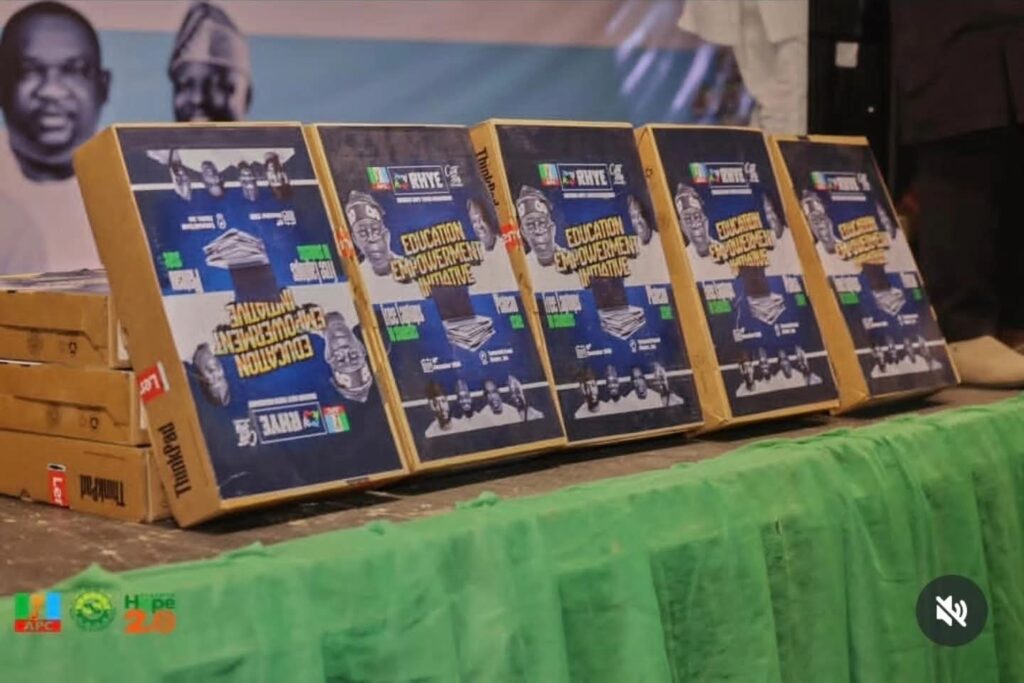
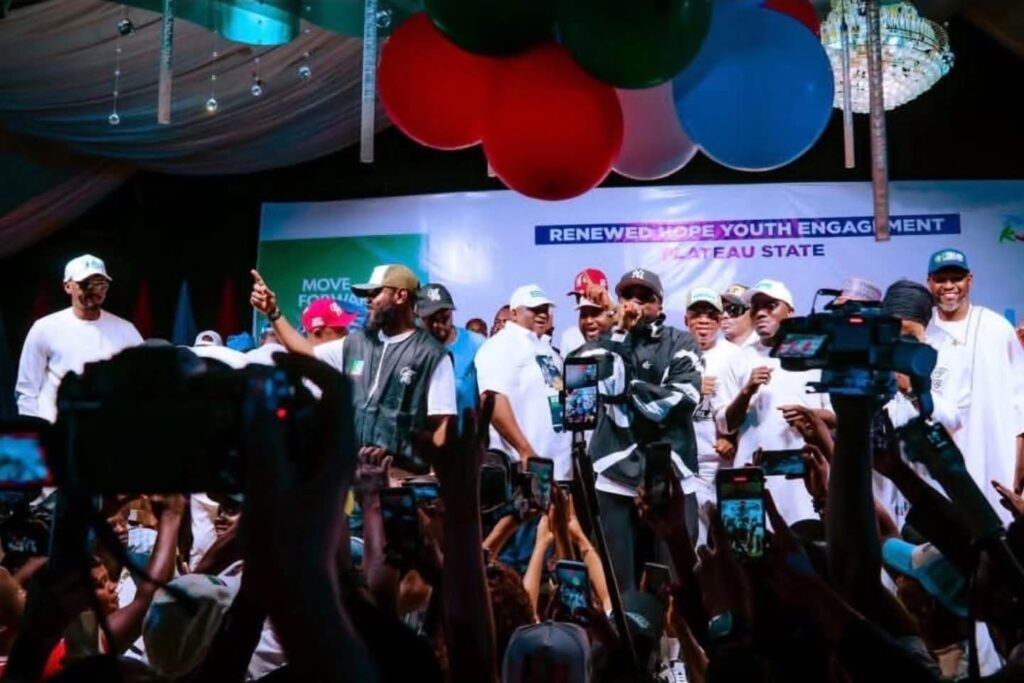
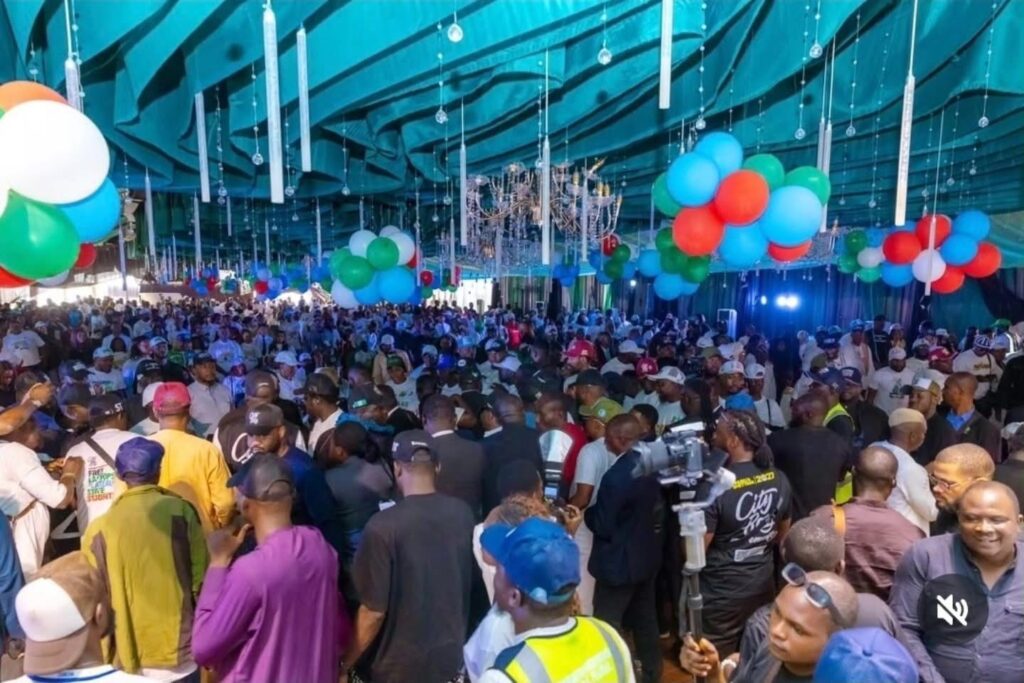
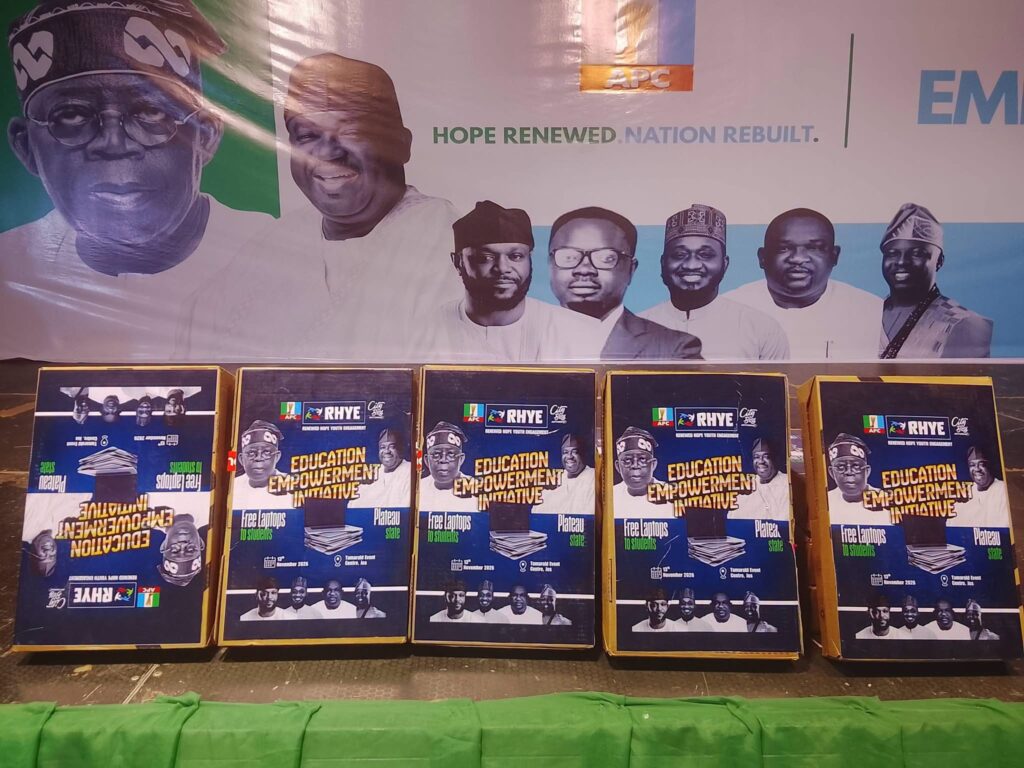
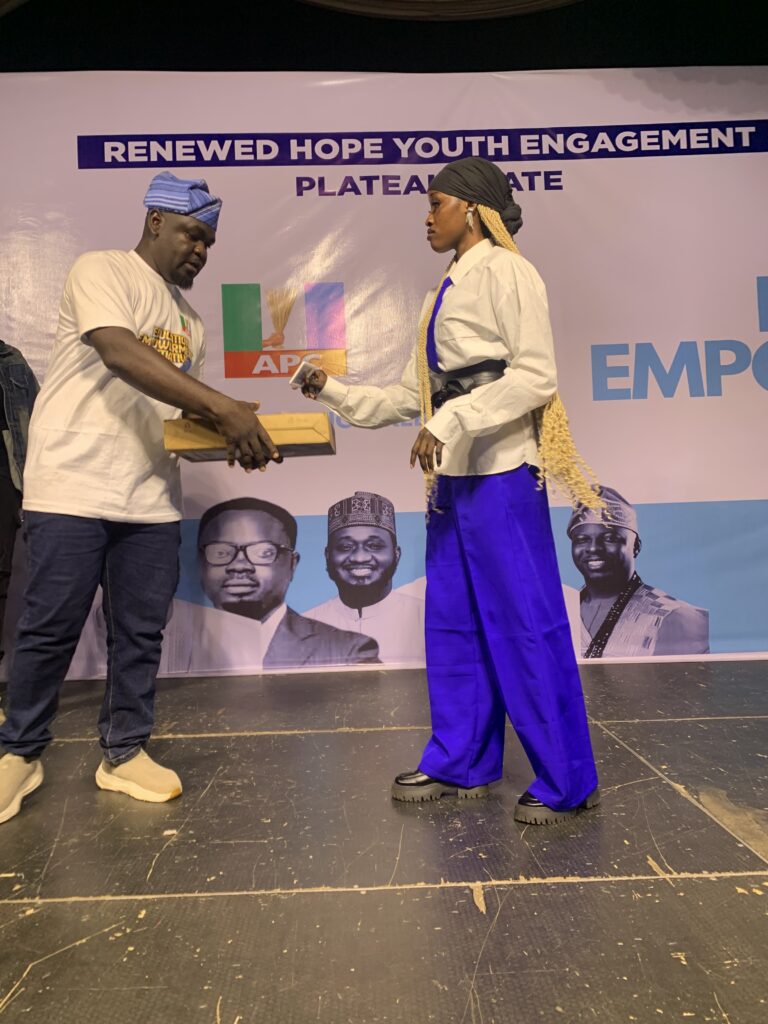
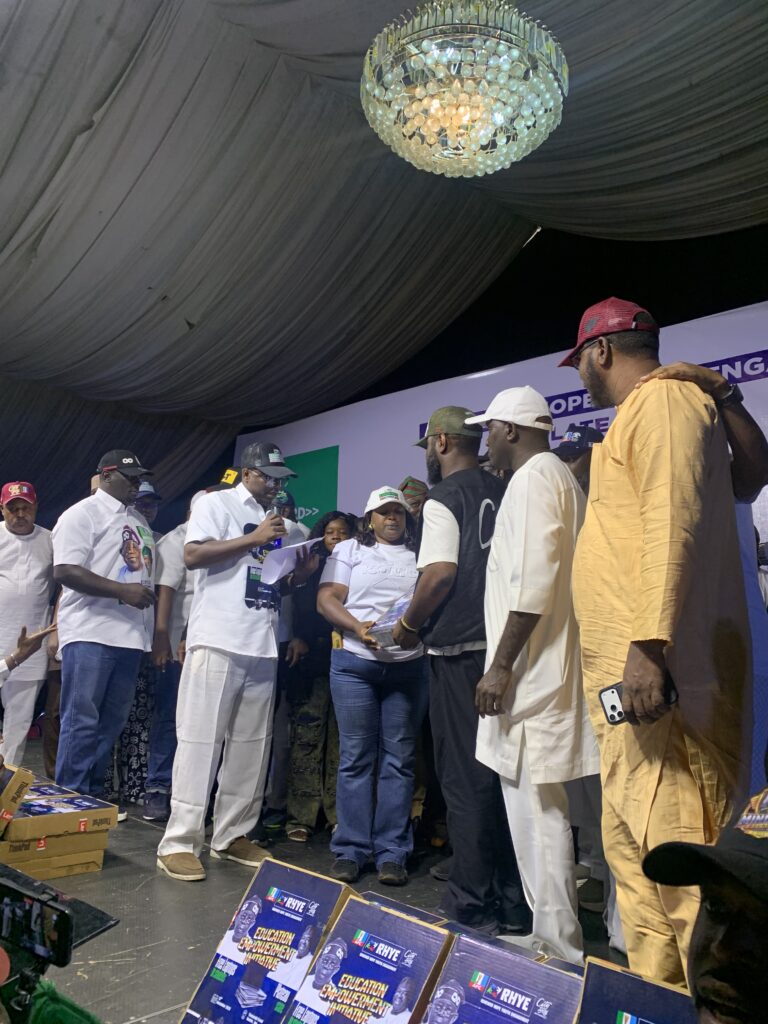
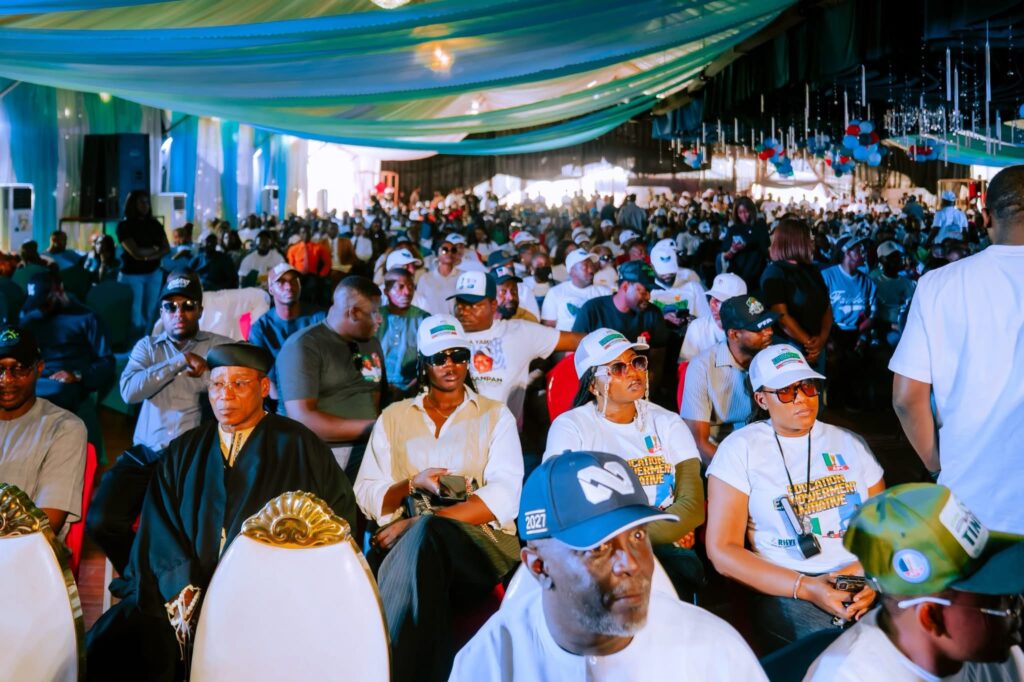
The Renewed Hope Youth Engagement (RHYE), Plateau State Chapter, on Friday, November 13, 2026, held an educational empowerment programme in Jos, Plateau State, with the distribution of free laptops to deserving students across tertiary institutions in the state.

The initiative, held at Tamarald Event Centre, Jos, was organised in line with the Renewed Hope Agenda of President Bola Ahmed Tinubu and the vision of Renewed Hope Youth Movement . It is aimed at promoting digital inclusion, strengthening educational opportunities and equipping young Nigerians with the technological resources needed to excel in today’s increasingly digital society.

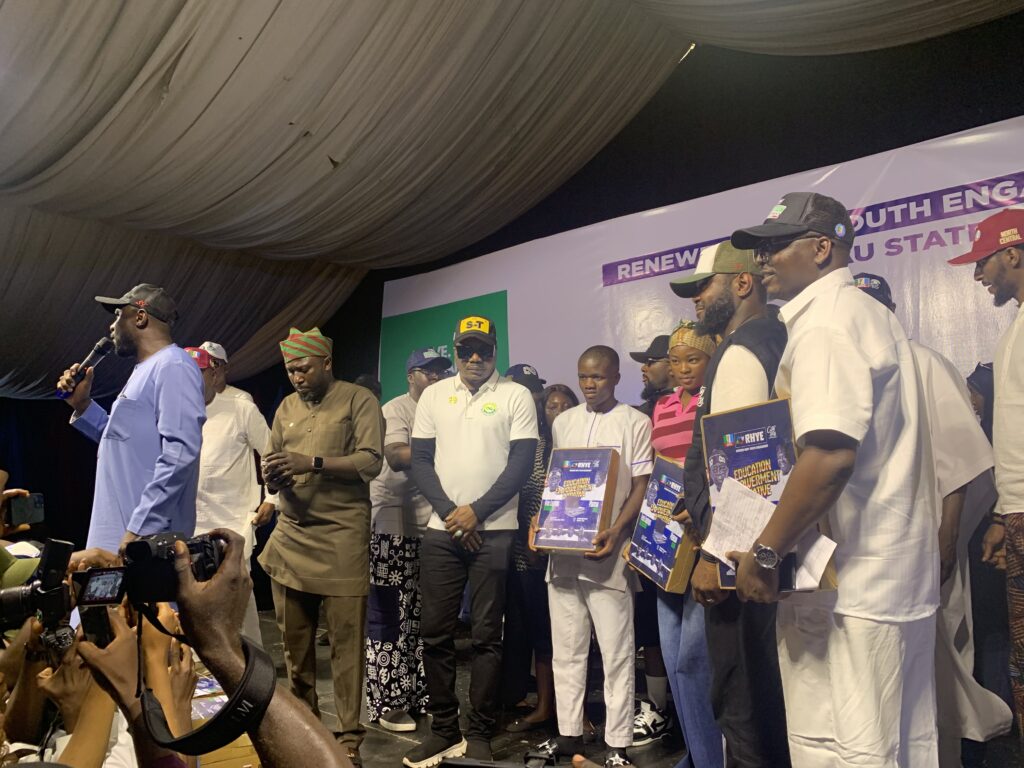
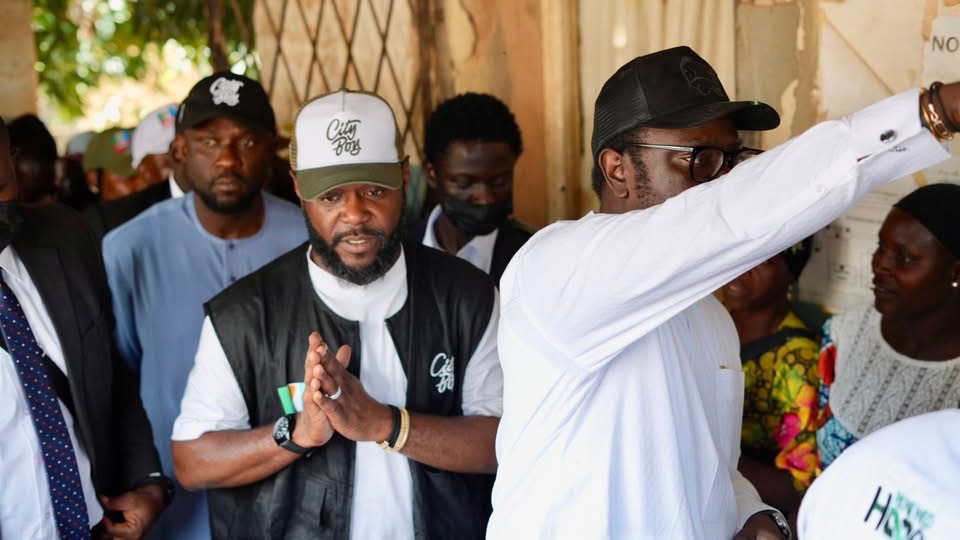
The event featured the presence of the Grand Patron of the Renewed Hope Youth Engagement initiative, Barr. Seyi Tinubu, who was accompanied by the Honourable Minister of Youth Development, Comrade Ayodele Olawande Wisdom.
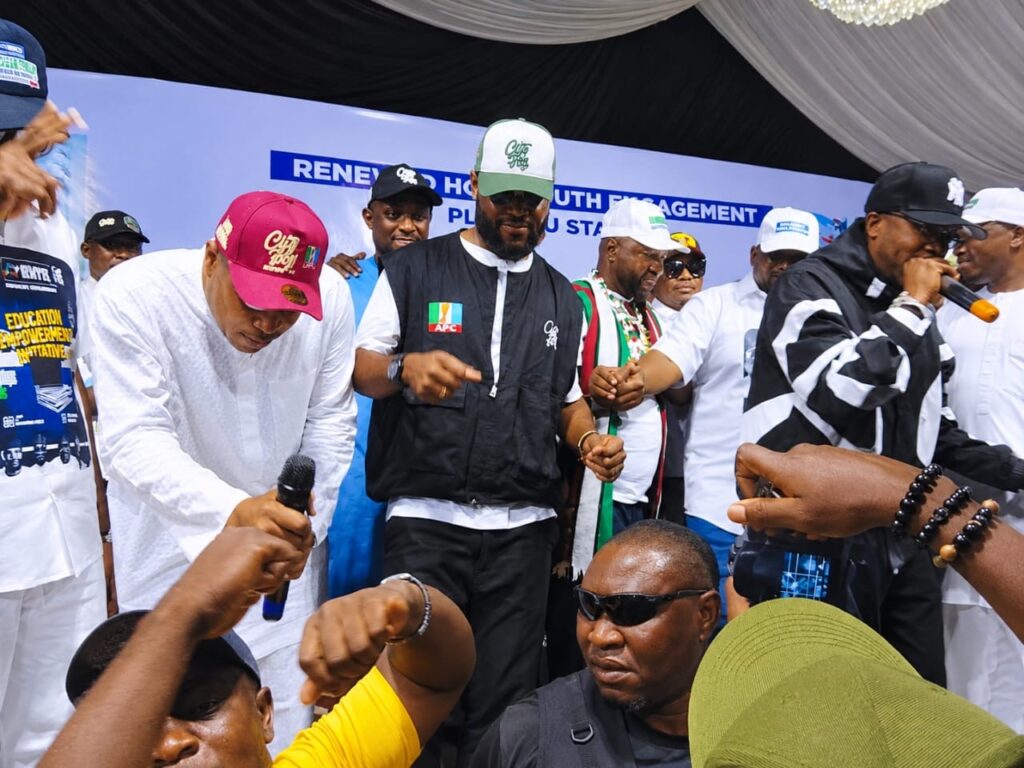
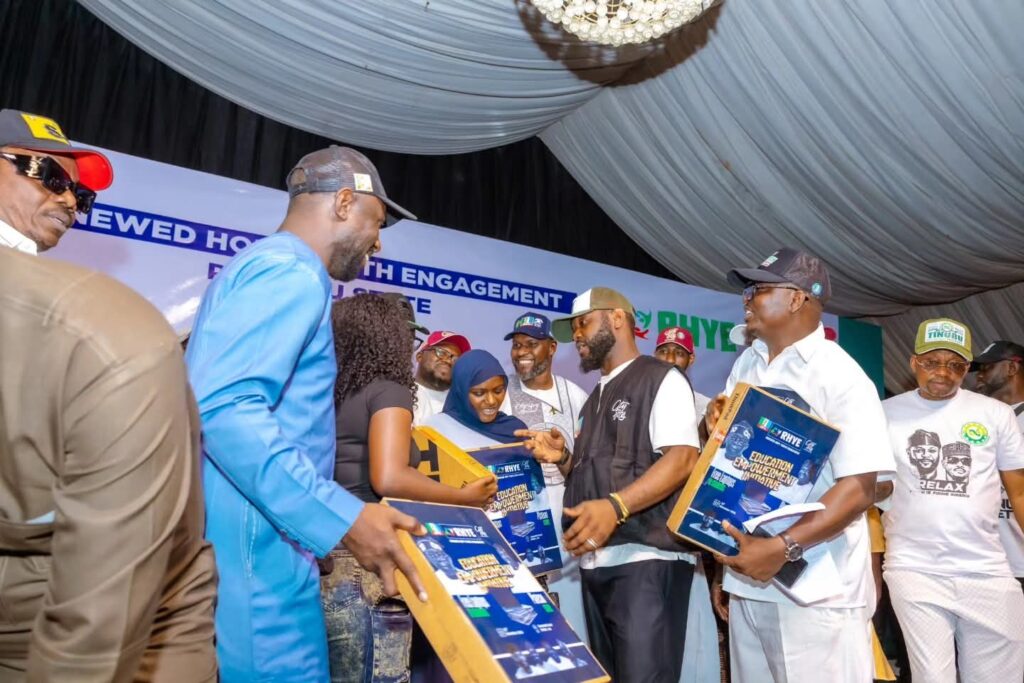
Other notable dignitaries included the Plateau State Commissioner for Youth and Sports Development, Hon. Prince Miaphen; the Plateau State Coordinator of the City Boy Movement, Prince David Daser; the State Coordinator of Renewed Hope Youth Engagement, Mr. Manji Wilson; alongside other government officials, youth leaders, political stakeholders and students.

500 LAPTOPS TARGETED, 50 STUDENTS BENEFIT IN FIRST PHASE

A major highlight of the programme was the announcement of plans to distribute 500 laptops to deserving tertiary institution students across Plateau State.

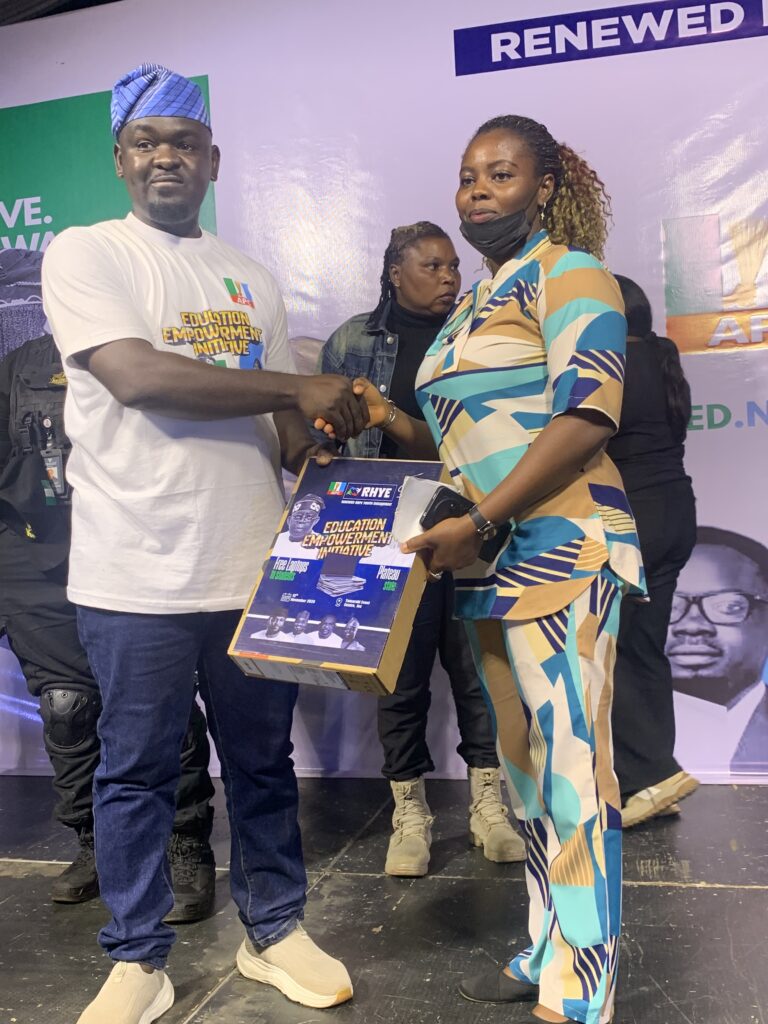
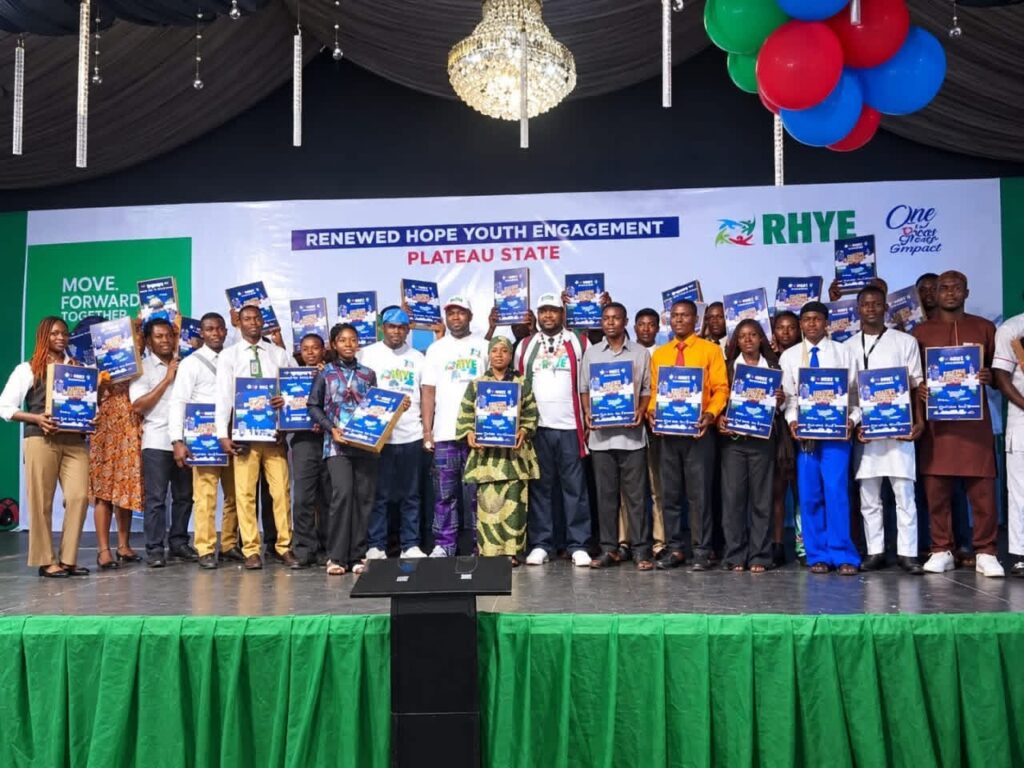
Under the first phase of the initiative, 50 students drawn from various institutions received brand-new laptops to support their academic activities and digital learning.
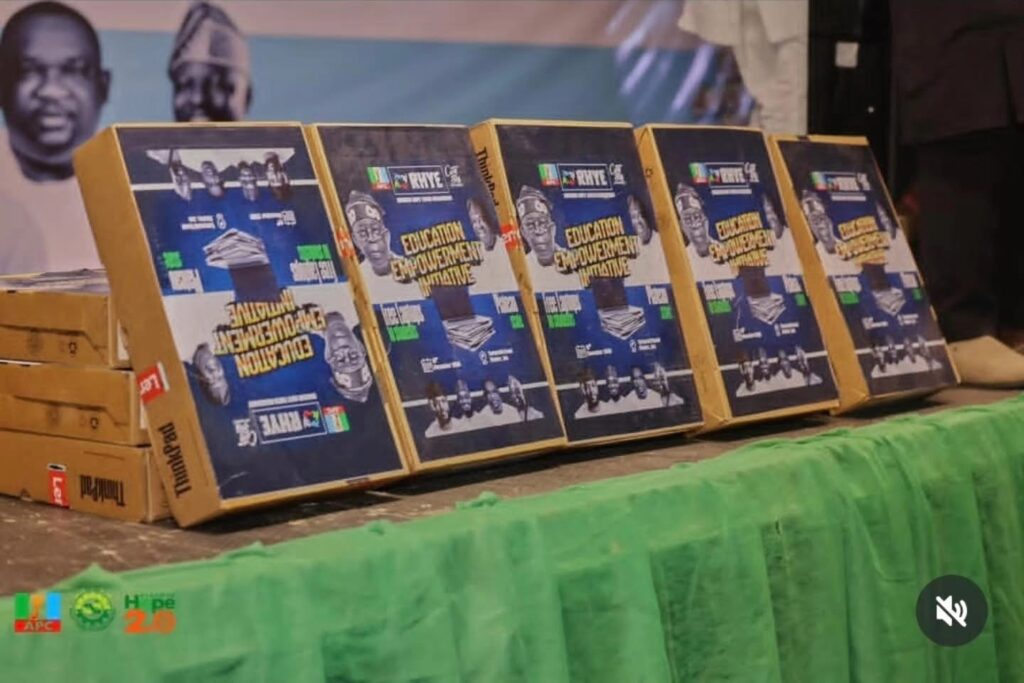
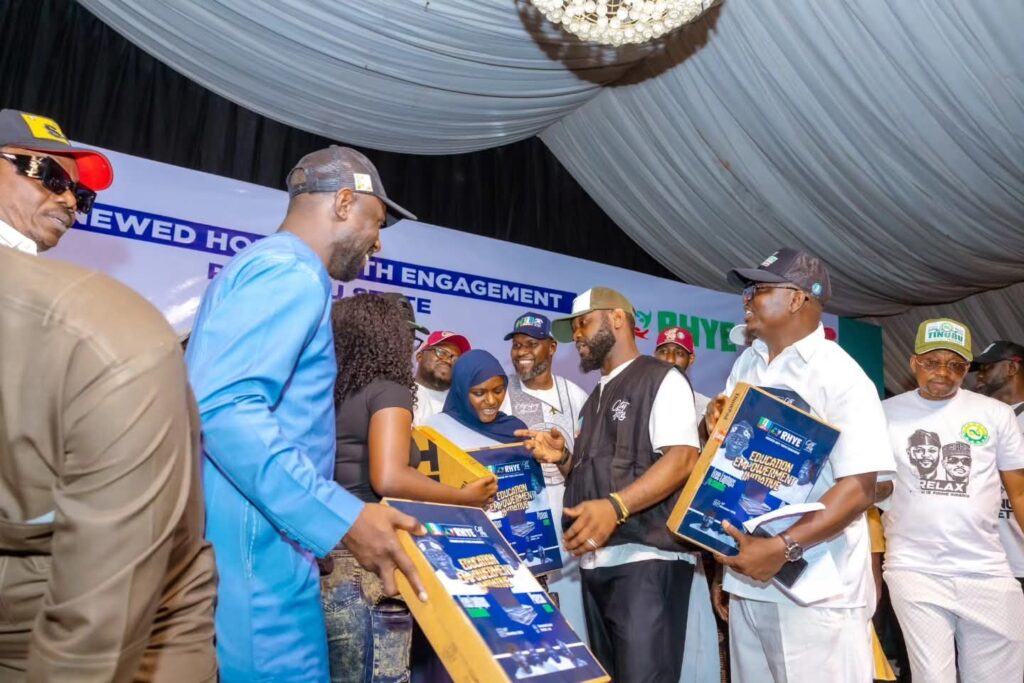
Among the institutions represented were the University of Jos (UNIJOS), Plateau State University (PLASU), Plateau State Polytechnic (PLAPOLY), College of Health Technology, Zawan, College of Health Technology, Pankshin, and other institutions.

According to the organisers, the beneficiaries were selected based on academic merit, particularly their Cumulative Grade Point Average (CGPA), through a process facilitated by their respective institutions.

The laptops are expected to enhance students’ access to digital learning resources, academic research, assignments, online educational platforms and the acquisition of essential technological skills.

SEYI TINUBU VISITS GOVERNOR MUTFWANG, BARKIN LADI MEDICAL OUTREACH

Beyond the educational empowerment programme, Barr. Seyi Tinubu’s visit to Plateau State also featured other engagements.
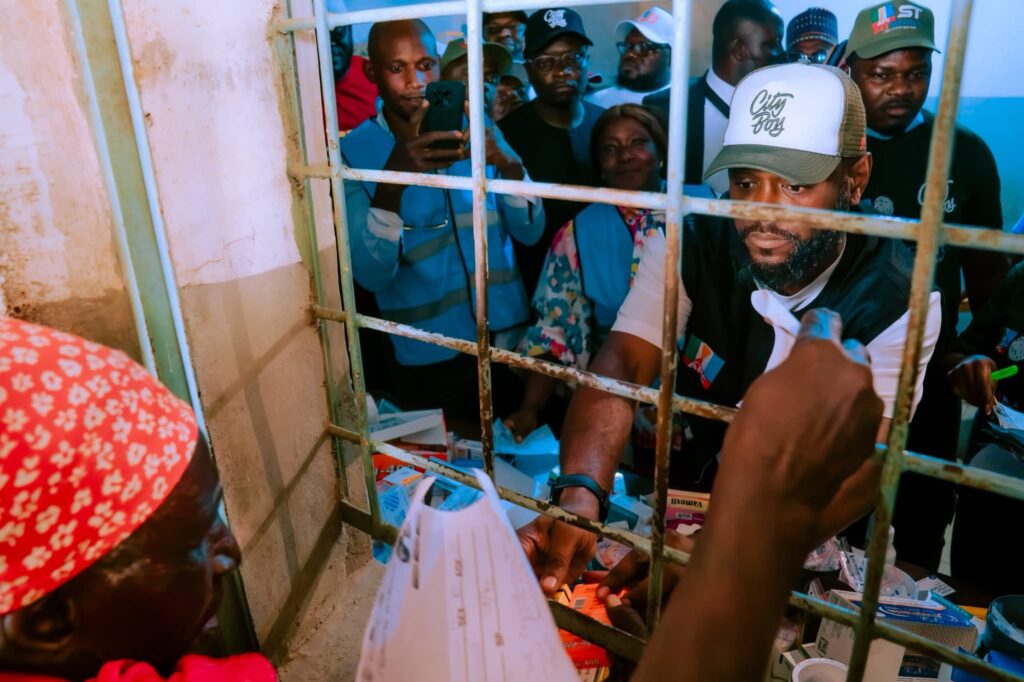
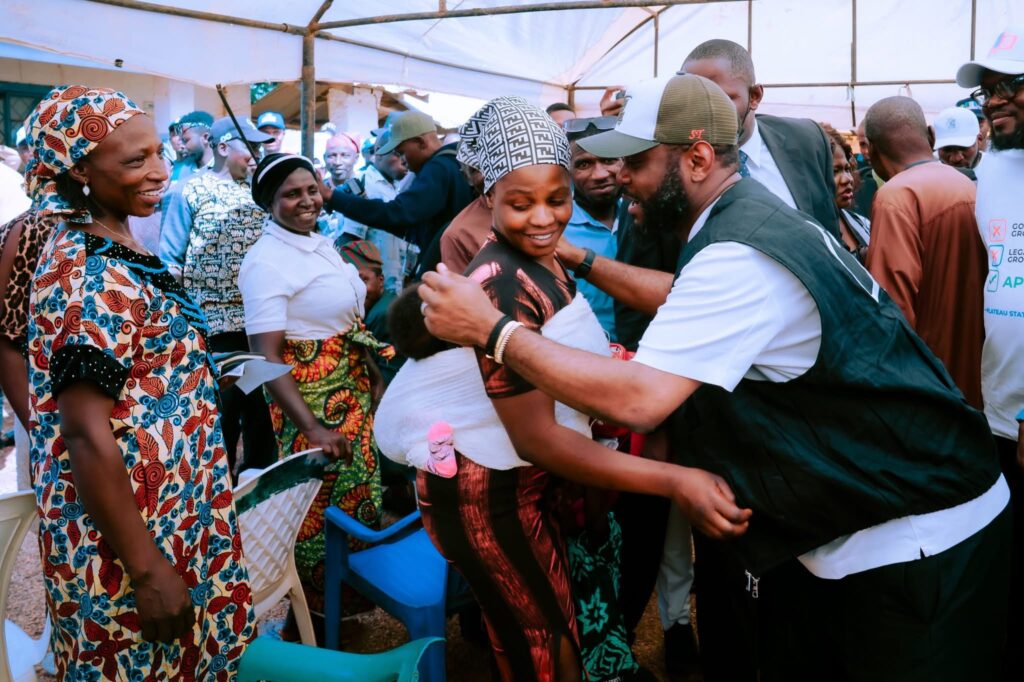
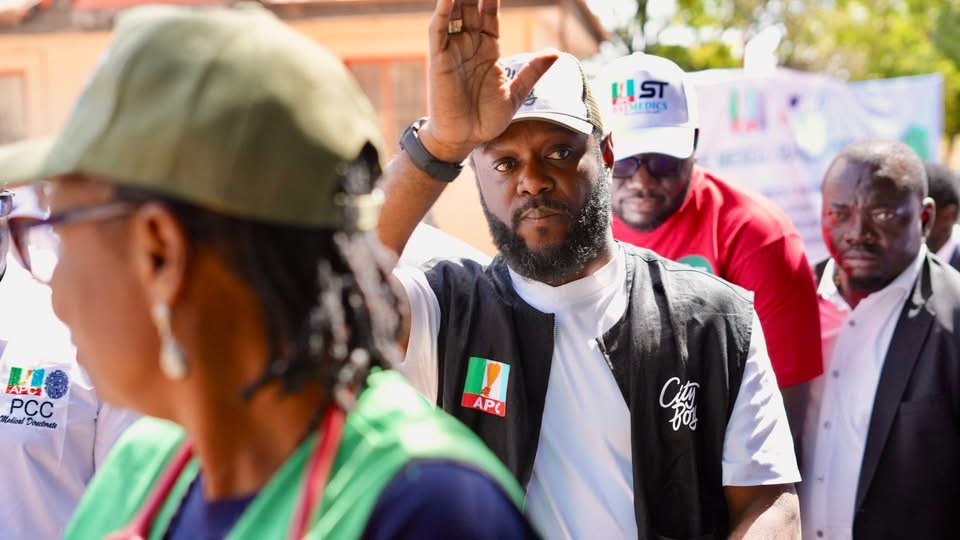
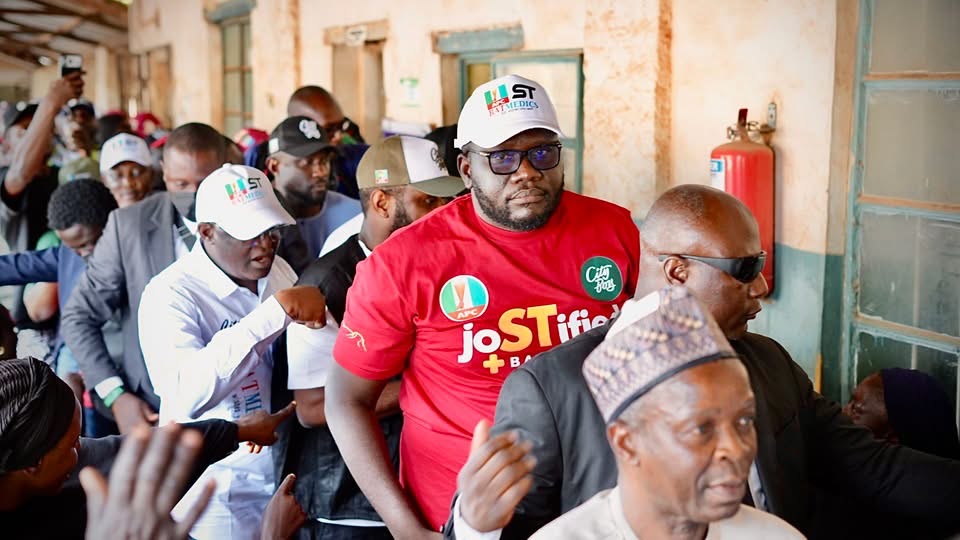
Prior to the event in Jos, he visited a free medical outreach organised by the City Boy Movement in Barkin Ladi, where residents benefited from healthcare services.

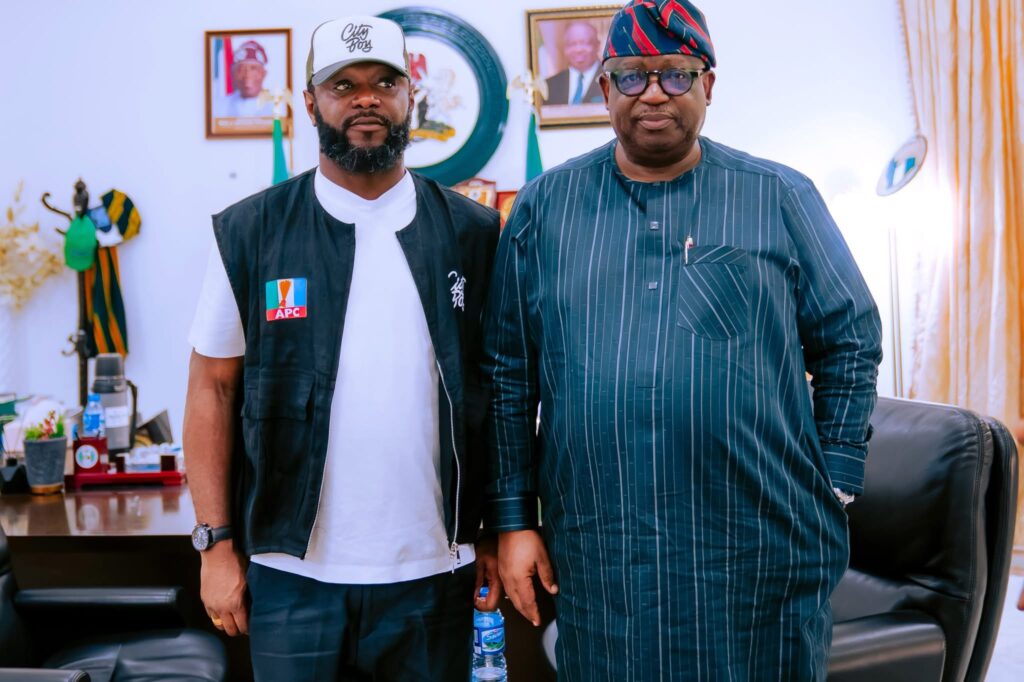
He also paid a courtesy visit to the Executive Governor of Plateau State, His Excellency, Barr. Caleb Manasseh Mutfwang, at the Government House, Jos.
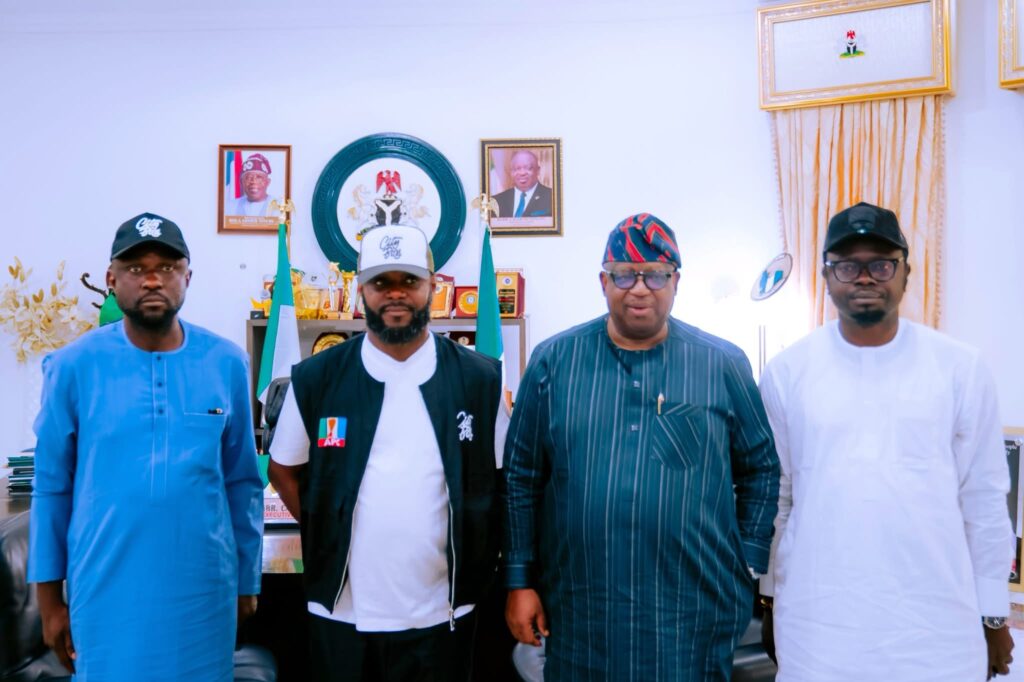
The organisers expressed appreciation to the Plateau State Government and the TIME IS NOW administration for their support and cooperation towards the successful hosting of the programme.

JOS ENTERTAINMENT STARS ADD COLOUR TO THE EVENT

The programme also featured entertainment and musical performances, making the occasion a celebration of youth, education and talent.

Popular Nigerian rapper Ice Prince Zamani, alongside Jos-based entertainers including Classic and Seemo Da Black Czar, thrilled guests and participants with live performances.
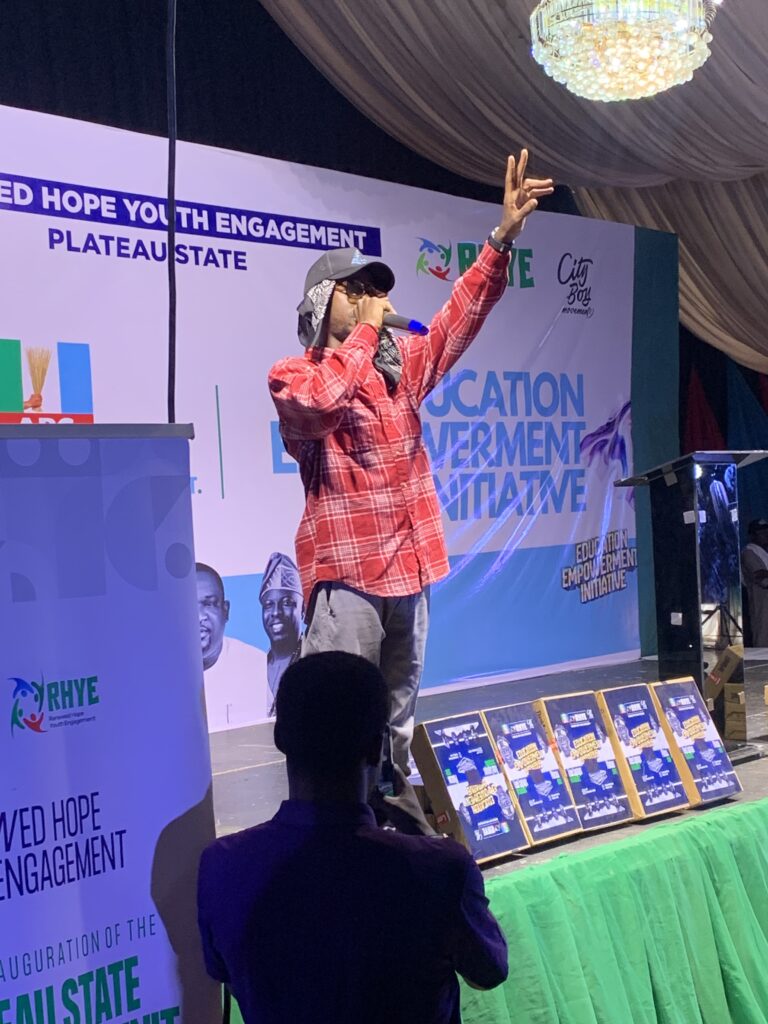
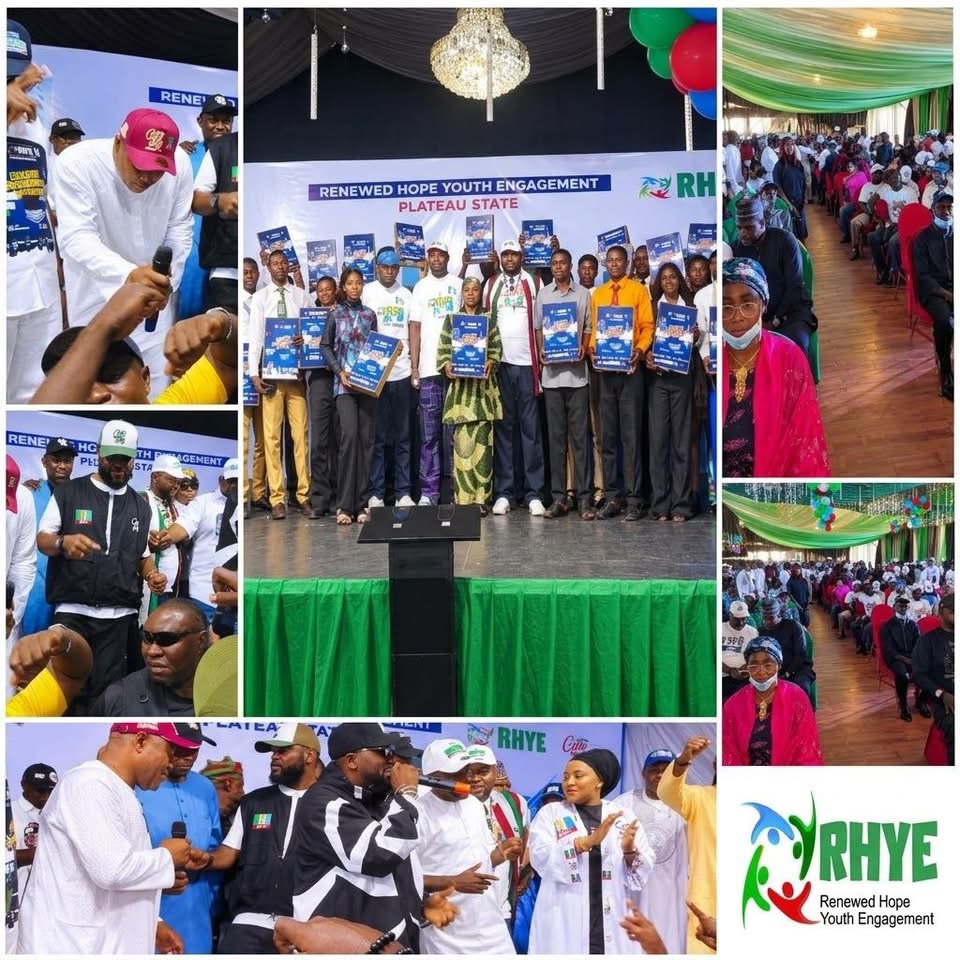
The entertainment segment added excitement to the gathering, bringing together education, youth engagement and the creative industry on one platform.

AN INVESTMENT IN THE FUTURE OF YOUNG PEOPLE

Speaking on the significance of the initiative, the organisers emphasised that the laptop distribution goes beyond the provision of electronic devices, describing it as an investment in the future of young Nigerians.

For the beneficiaries, the laptops represent valuable tools that will improve their learning experiences, expand access to educational opportunities, encourage digital innovation and prepare them for a technology-driven world.

The event which was well coordinated by Renewed Hope Youth Engagement further highlights the importance of youth-focused initiatives in promoting education, innovation, digital inclusion and sustainable development.

With a target of reaching 500 students, the initiative is expected to extend its impact to more deserving students across Plateau State as subsequent phases of the programme unfold.

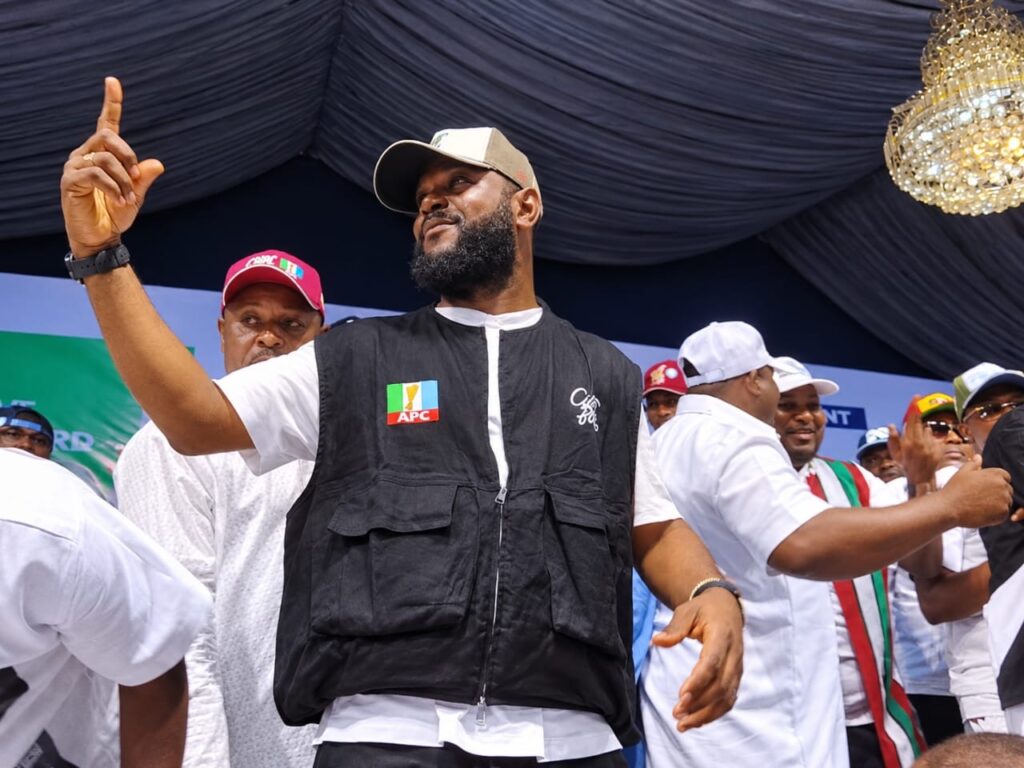
The November 13 engagement marks another major youth-focused activity in Plateau State, bringing together government, youth organisations, educational institutions and the creative community in support of the development and empowerment of young people.
Continue Reading

News

2027: Peter Obi can't run typical Nigerian political organisation – Sam Amadi

info

Published

on

A political analyst, Sam Amadi, has said presidential candidate of the Nigeria Democratic Congress, NDC, Peter Obi, cannot effectively run a typical Nigerian political organisation because of his minimalist political approach and reluctance to distribute money.

Amadi said Obi's style of politics was fundamentally different from Nigeria's prevailing political culture, where politicians expect financial rewards and other benefits from their political associations.

He argued that some politicians who left Obi's camp were partly driven by what they expected from him but did not get.

Speaking on Arise Television's Prime Time programme on Friday, Amadi said Nigeria's political environment was unstable, with politicians frequently moving between political platforms in pursuit of personal interests.

According to him, some politicians who left Obi's camp had approached him to explain their grievances.

Amadi said their complaints reflected a fundamental disagreement between Obi's political philosophy and the expectations of politicians operating within Nigeria's political system.

The former Director-General of the Nigerian Electricity Regulatory Commission, NERC, maintained that Obi understood his limitations in managing the country's conventional political structure.

He also described Obi as a minimalist who prefers a less elaborate approach to politics, arguing that the former Anambra State governor would rather pursue a straightforward path to political success than engage in the extensive political mobilisation associated with conventional Nigerian politics.

Amadi said: "Peter Obi represents a different kind of politician. Everything about him is often also exaggerated.

"Atiku ran for election with him as vice. The first thing he did after the election was to jump.

"First, Nigeria has a political market that's unstable. Yes. Most of these guys who left, they've come to me, and I talk to them, and they bring issues of grievance. And I say to these guys, look, I've served as Senate president. I've served Jonathan. I disagree with these people, but it's part of it.

"There's a political career. These guys want to move on. Secondly, they also want to have some things Peter cannot offer. That's a deep dissonance between Peter and Nigerian politics. People forget that. Yes, he doesn't give money.

"So Peter is not capable; Peter cannot run a typical Nigerian political organization. He knows that.

"Again, Peter is a minimalist, but it's business. He likes to, if he can, just sneak through this. He doesn't have to open the whole place."

2027: Peter Obi can’t run typical Nigerian political organisation – Sam Amadi

Continue Reading

Trending