Connect with us

Business

FULL LIST: NIIRA 2025: NAICOM Eyes Liquidation for Non-Compliant Operators

info

Published

on

BY NKECHI NAECHE-ESEZOBOR—The National Insurance Commission,((NAICOM),  on Monday said only eight insurance companies are yet to be verified by the commission.

The commission disclosed this today while releasing the 43 insurance firms that met the new minimum capital requirements set up by NIIRA

According to NAICOM “The eight insurance companies submitted evidence of compliance shortly before the statutory deadline are currently undergoing final verification and regulatory review.

This, the commission said would be concluded within fourteen days.

Insurance companies not listed among the 43 verified firms include those currently undergoing final regulatory review, as well as unverified operators at risk of liquidation—such as NICON Insurance Plc; Goldlink Insurance Plc Nigerian Reinsurance; Nigerian Agricultural Insurance Corporation ; Royal Exchange Prudential Life Plc;  Tangerine Life Insurance Limited; Sovereign Trust Insurance Plc; African Alliance Insurance Plc; Guinea Insurance Plc; Regency Alliance Insurance Plc; Staco Insurance Plc; Alliance & General Insurance; Universal Insurance Plc; emPle General Insurance Company Nigeria Limited and emPle Life Assurance Limited.

NAICOM had announced the successful completion of the twelve-month insurance sector recapitalization exercise undertaken pursuant to Section 15 and other relevant provisions of the Nigerian Insurance Industry Reform Act (NIIRA) 2025, signed into law on 31 July 2025 by His Excellency, President Bola Ahmed Tinubu, as part of his administration’s financial sector transformation agenda towards the attainment of a US$1 trillion economy by 2030.

The successful conclusion of the exercise marks a defining milestone in the transformation of Nigeria’s insurance industry and signals the beginning of a new era for insurance in the country.

Following the enactment of NIIRA 2025, the Commission commenced a structured implementation process to provide strategic oversight, ensure transparency, support operators throughout the transition, and facilitate the effective implementation of the new minimum capital requirements within the statutory compliance period.

To ensure an orderly, transparent, credible, and verifiable process, the Commission issued the Guidelines on the Implementation of Minimum Capital Requirements (MCR) for Insurance and Reinsurance Companies in Nigeria.

The Guidelines provided detailed guidance on the statutory minimum capital requirements under NIIRA 2025, eligible and ineligible capital instruments, admissible and non-admissible assets, verification and validation procedures, regulatory timelines, reporting obligations, and supervisory expectations throughout the implementation period.

The post FULL LIST: NIIRA 2025: NAICOM Eyes Liquidation for Non-Compliant Operators appeared first on Business Today NG.
Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business

FCCPC Seals Peachville Platinum Estate Offices Over N140m Undelivered Abuja Property

info

Published

on

The Federal Competition and Consumer Protection Commission (FCCPC) has taken enforcement action against Peachville Platinum Estate Limited after the company failed to comply with a Compliance Notice issued in connection with a consumer complaint over the alleged non-delivery of a N140 million property in Abuja.

During the enforcement exercise conducted on Thursday, a team from the Commission, led by Marvin Nadah, sealed the company’s headquarters located along Airport Road, alongside its management office situated at Peachville Gardens, opposite Games Village.

The complaint concerns a four bedroom detached duplex with boys’ quarters at Peach Ville Estate, Phase II, Kukwaba District, Abuja. The complainant told the Commission that they paid the full purchase price in August 2025 after the company assured them that it would hand over the property upon completion of payment. According to the complainant, the property remained unfinished and was never handed over.

The Commission investigated the complaint and gave both parties an opportunity to present their accounts. The company said the parties had agreed, at a meeting at the Federal Capital Territory Administration, that it would hand over the property by August 2026. The company did not provide documents to support its account of the agreement.

The Commission convened further proceedings and summoned the company to provide additional information. The company’s responses failed to satisfactorily address the issues the Commission raised. Its representatives also declined to sign the witness statements required to conclude the hearing.

The Commission issued a Compliance Notice on 17 August 2026 under section 150 of the Federal Competition and Consumer Protection Act, 2018. The company received the notice on 19 August 2026. After confirming that the company had failed to comply within the stipulated period, the Commission took enforcement action under section 150(4)(a) of the Act.

Commenting on the action, the Executive Vice Chairman and Chief Executive Officer of the FCCPC, Mr. Tunji Bello, said, “For many Nigerians, buying a home involves years of savings. When a developer accepts payment and commits to a handover date, the buyer is entitled to rely on that commitment. If delays arise, the developer should explain them promptly and give the buyer a realistic timetable.

“The Commission gave both parties an opportunity to be heard. Once the Commission issues a Compliance Notice, the business is required to take the steps set out in it within the specified period. Where a business fails to comply, the Commission will take the enforcement action provided for by law.”

The post FCCPC Seals Peachville Platinum Estate Offices Over N140m Undelivered Abuja Property appeared first on Business Today NG.

Continue Reading

Business

Finance must break developing countries from ‘debt and disaster’ loop – UN climate chief

info

Published

on

WhatsApp Image 2026 11 13 at 21.43.24.jpeg

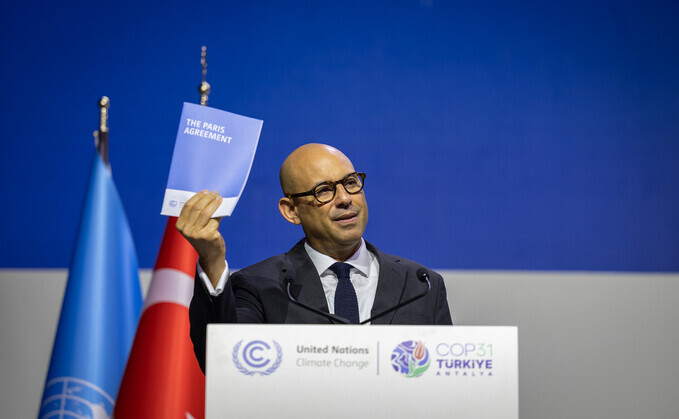
The executive secretary of UN Climate Change, Simon Stiell, told the ministers at COP31 that climate finance must be redesigned to lift developing countries out of a cycle of debt and disaster, adding that meeting a headline figure will not do it.

“Meeting a financial target does not always meet countries’ needs. To do that, we need to look at how finance is delivered,” Mr Stiell said on Friday at the opening of a high-level ministerial dialogue on climate finance in Antalya, Turkey.

Countries agreed at COP29 that developed nations would lead in providing $300 billion a year by 2035, as part of a wider effort to raise $1.3 trillion annually from all sources.

Mr Stiell said the roadmap for reaching those sums “must become reality”, but that the terms of the money mattered as much as the amount.

“Many developing countries are trapped in a downward loop of debt, disaster, and devastating capital costs,” he said. “The threat of floods, fires, storms and droughts hangs over them, pushing up the price of borrowing even before disaster strikes.”

He stated that the terms of finance should reflect each country’s debt position.

PT WHATSAPP CHANNEL
Dangote Refinery AD

“Private finance, loans and guarantees are essential to achieving our collective goals. But grant-based and highly concessional finance will remain critical, particularly for Least Developed Countries, Small Island Developing States and other very vulnerable economies,” he said.

According to him, broader action on debt is also needed to prevent countries from being forced to choose between repayments and resilience.

International climate finance for developing countries reached about $137 billion in 2024, and almost 70 per cent of it came in the form of loans, according to a UN Women flagship report released on Tuesday in Antalya.

Countries in sub-Saharan Africa paid more than twice as much in external debt service between 2021 and 2023 as they received in climate finance, according to an analysis published by the Heinrich Böll Foundation.

The analysis found that interest payments consumed more than 10 per cent of government revenue in 27 African countries in 2024.

The chair of the African Group of Negotiators, Nana Antwi-Boasiako Amoah, has said that a transition could not be called just if poorer countries have to “mortgage their futures” to pay for it.

The group lost a bid on Monday for a separate agenda item on tripling adaptation finance. It now wants the target prioritised in the summit’s cover decision.

Nigeria is not on the UN’s list of least developed countries, which places it among the states the UN climate chief expects to rely more on loans, guarantees and private capital.

It needs about $337 billion between 2026 and 2035 to implement its climate commitments, according to the National Council on Climate Change.

Omotenioye Majekodunmi, the agency’s director-general, said more than 80 per cent of that will have to come from private investment, commercial debt, and international carbon finance.

About $2.5 billion a year went to climate action in Nigeria in 2021 and 2022, counting domestic and international sources, according to the Climate Policy Initiative’s tracking.

The dialogue was the last in a series that began in 2013, and its conclusions will go to COP32 in Ethiopia next year, Mr Stiell said.


Discover more from Premium Times Nigeria

Subscribe to get the latest posts sent to your email.

Continue Reading

Trending