News
IMF: Nigeria ranks among Africa’s biggest potential AI beneficiaries – Technology Times

Nigeria is among the five Sub-Saharan African countries best positioned to benefit from the growing adoption of artificial intelligence (AI), according to a new report by the International Monetary Fund (IMF), which says the country has greater potential than most of the region to translate AI into productivity and economic growth.
The IMF, in its report titled Unlocking the Potential: AI in Sub-Saharan Africa, identifies Nigeria alongside South Africa, Mauritius, Botswana and Namibia as the economies expected to record the largest AI-driven productivity gains under current conditions. South Africa is projected to lead the region, followed by Mauritius, with Nigeria ranking among the top performers.
Despite Nigeria’s favourable position, the IMF cautions that the projected gains remain modest compared with advanced economies because of low AI adoption, infrastructure deficits and limited digital preparedness across the region.
“These estimates should be interpreted as a current-conditions diagnostic rather than a forecast of AI’s technological potential. They reflect today’s low adoption, infrastructure gaps, and sectoral structure; they do not capture the full range of gains that could arise from faster diffusion, structural transformation, public sector applications, or AI-enabled innovation,” the report says.

“These estimates should be interpreted as a current-conditions diagnostic rather than a forecast of AI’s technological potential. They reflect today’s low adoption, infrastructure gaps, and sectoral structure; they do not capture the full range of gains that could arise from faster diffusion, structural transformation, public sector applications, or AI-enabled innovation,” the report says.
Nigeria among Africa’s AI frontrunners
The IMF attributes Nigeria’s relatively strong outlook to the structure of its economy, which has a larger share of sectors such as information and communication technology (ICT), finance and professional services than many other Sub-Saharan African countries.
These sectors are considered more exposed to AI because they rely heavily on knowledge-intensive and information-processing tasks that can be enhanced or automated using AI technologies.
While agriculture and informal services continue to dominate employment across much of the region, the report notes that job composition in Botswana, Mauritius, Namibia, Nigeria, Seychelles and South Africa more closely resembles that of emerging market economies, placing them in a stronger position to benefit from AI adoption.
According to the IMF, three factors will determine the scale of AI’s economic impact: the proportion of tasks exposed to AI, the rate at which businesses and workers adopt the technology, and the productivity improvements generated through its use.
Productivity gains remain limited
Although Nigeria ranks among the continent’s strongest performers, the IMF projects that productivity gains across Sub-Saharan Africa will remain significantly below those of advanced economies unless governments address critical barriers to AI adoption.
The report estimates that AI will increase productivity across Sub-Saharan Africa by only 0.2% cumulatively over the next decade under current conditions, compared with around 1% in Europe and the Western Hemisphere. When additional AI-related investment is factored in, the technology could contribute an overall cumulative GDP growth effect of about 0.4% over the same period.
The IMF says these projections reflect today’s realities rather than AI’s long-term capabilities.
Infrastructure challenges remain
The report identifies unreliable electricity, limited broadband connectivity, inadequate data centre capacity, shortages of AI skills and constrained investment as the principal obstacles preventing countries from unlocking AI’s full economic potential.
It notes that AI adoption across Sub-Saharan Africa remains below 10%, about two to three times lower than in Europe and the Western Hemisphere, while internet usage and access to reliable electricity also lag global averages.
Human capital also remains a challenge. According to the report, fewer than one-quarter of higher education students in Sub-Saharan Africa study science, technology, engineering and mathematics (STEM) disciplines, while only about 5% of the continent’s AI researchers have reliable access to the high-performance computing needed for advanced AI research.
Greater gains possible
Despite the current constraints, the IMF says the region has significant room to improve if governments accelerate AI adoption and strengthen enabling infrastructure.
“The barriers to AI adoption in Sub-Saharan Africa are real and represent binding constraints at present. But they are barriers, not boundaries features of the current moment. Relax those assumptions, and the numbers could change substantially,” the report says.
The IMF adds that raising AI adoption rates to levels seen in other emerging and advanced economies could more than double the region’s productivity gains over the next decade.
“If current adoption rates were lifted to levels observed in other emerging and advanced economies, productivity gains could more than double, increasing by an additional 0.8 percent over the next decade,” the report says.
Opportunity for Nigeria
For Nigeria, the findings reinforce the country’s growing position as one of Africa’s emerging AI hubs. The report highlights the country’s expanding technology ecosystem and references the Federal Government’s Three Million Technical Talent (3MTT) programme as an important initiative aimed at strengthening digital and technical skills. However, it says investments in electricity, broadband infrastructure, computing capacity and AI talent will be essential for the country to fully capitalise on the technology.
The IMF concludes that while Nigeria is among Africa’s biggest potential AI beneficiaries, translating that potential into measurable economic gains will depend on sustained investments in digital infrastructure, supportive policies and wider adoption of AI across both the public and private sectors.




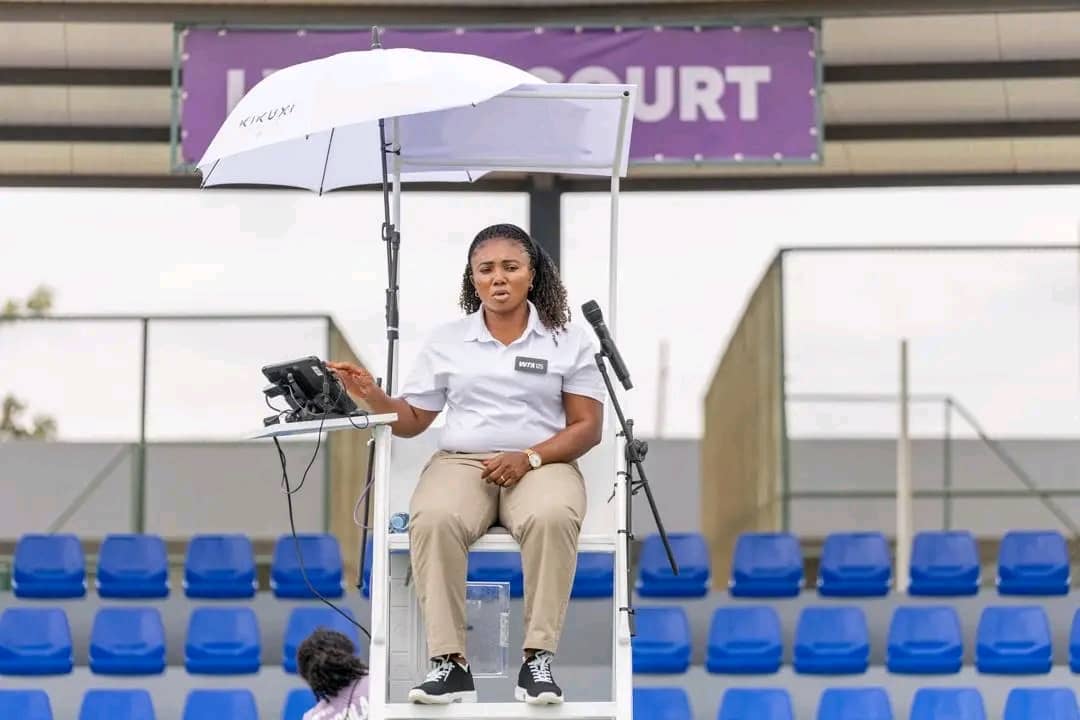
Nigerian female tennis umpire, Rose Onoja Abu, has earned recognition after officiating at the WTA 125 tournament in Luanda, Angola, marking a significant milestone in her professional career and another proud moment for Nigerian tennis.
Sports247 reports that the tournament made history as the first-ever WTA 125 event to be staged on African soil, bringing an important international women’s tennis competition to the continent. Abu’s involvement as an official at the landmark event further highlights Nigeria’s growing presence beyond the playing court in international tennis.
Her appointment and participation represent an encouraging achievement for Nigerian sports officiating, particularly for women working to establish themselves in the highly competitive world of international tennis administration.
Officiating at a tournament of this level requires professionalism, consistency, sound judgement and a strong understanding of the rules of the game. Abu’s presence at the Luanda event reflects the value of dedication and sustained commitment to developing a career in sports officiating.
The achievement also provides inspiration for aspiring Nigerian umpires and other sports professionals, demonstrating that opportunities at the highest levels can emerge through discipline, diligence and continuous improvement.
For Nigerian tennis, milestones such as this are important in showcasing the contributions of officials who help drive the sport forward, often away from the spotlight enjoyed by players.
While the WTA 125 assignment represents a significant step in Abu’s journey, it could also serve as a platform for greater opportunities on the international stage.
With consistency and continued dedication, the ambition of seeing a Nigerian umpire officiate at a Grand Slam tournament remains a possibility worth pursuing.
Congratulations to Rose Onoja Abu on this remarkable achievement. The journey continues, and a Grand Slam appearance could be the next milestone.
SanlamAllianz Life Insurance Nigeria Limited has launched Esusu, an innovative savings initiative designed to encourage a consistent savings culture, promote financial discipline and help Nigerians take practical steps towards achieving their financial goals.
Inspired by the traditional Nigerian Esusu savings system, the initiative combines the familiarity of regular savings practices with the added benefits of a structured insurance-backed savings arrangement. It provides individuals with an opportunity to build their savings through flexible daily contributions, with the option to make additional contributions as their financial capacity allows.
Through Esusu, customers can make regular contributions towards their savings goals and receive a maturity benefit based on their accumulated contributions, less applicable withdrawals, in line with the policy terms and conditions. The initiative also incorporates death cover, providing an additional layer of financial protection for beneficiaries in the event of an unfortunate occurrence, subject to applicable policy provisions.
Speaking at the launch, Tunde Mimiko, Managing Director/Chief Executive Officer, SanlamAllianz Life Insurance Limited, said: “At SanlamAllianz, we recognise that achieving financial confidence begins with the right financial habits. Saving should not be an overwhelming responsibility; it should be a consistent practice that individuals can incorporate into their everyday lives. With Esusu, we are bringing a familiar savings culture into a structured financial solution that encourages consistency while providing additional protection. Our goal is to empower more Nigerians to take charge of their financial future, one contribution at a time.”
The initiative reflects SanlamAllianz’s commitment to developing customer-focused solutions that respond to the evolving financial needs of Nigerians. By encouraging small, consistent contributions, Esusu seeks to demonstrate that building financial security does not necessarily require having large sums of money available at once. The product is available to eligible individuals between the ages of 18 and 80, subject to the applicable policy requirements and conditions.
Shedding more light on the product, Chris Ekwonwa, Group Head, Strategy, Marketing and Customer Relations, SanlamAllianz Nigeria, said: “Beyond providing a savings opportunity, Esusu reinforces the importance of financial literacy and long-term planning. It encourages individuals to become more intentional about managing their finances, preparing for future responsibilities and building a stronger financial foundation using a financial instrument they are very familiar with. With the campaign message “Esusu – Savings Wey Confam!”, SanlamAllianz is taking a relatable approach to financial empowerment, connecting with Nigerians through a savings concept deeply rooted in local culture while providing the structure and additional protection of an insurance solution.”
Industry watchers have long called for a retail driven product for the underserved markets, the launch of SanlamAllianz Esusu clearly is a stab at that target audience and expectations are rife as to the potential impact of the product.
SanlamAllianz Nigeria is no stranger to taking bold initiatives in the market space. With its first-of-its-kind SanlamAllianz Campus Takeover with Ayo Maff kicking off this weekend at the iconic OAU Amphitheatre at Ife, there are progressive signs that the brand is not paying lip service to its oft-stated quest to drive insurance penetration and financial inclusion in the Nigerian insurance market.
ABOUT SANLAMALLIANZ
SanlamAllianz is a Pan-African financial services joint venture between Sanlam, Africa’s largest non-banking financial services group, and Allianz, a global financial services and insurance leader.
In Nigeria, SanlamAllianz operates through its Life and General Insurance businesses, providing a range of insurance and financial solutions designed to protect individuals, families and businesses while supporting their financial aspirations.
The post SanlamAllianz Launches Esusu to Promote Savings Culture Among Nigerians appeared first on Business Today NG.
-

 News1 day ago
Troops Arrest Suspected Gunrunner, Neutralise Two Terrorists in Plateau
-
News2 days ago
Makinde Visits COCIN Headquarters in Jos, Urges Christians to Shape Nigeria’s Political Future
-
News4 days ago
Presidency seeks AI safeguards ahead of 2027 elections – Technology Times
-
News3 days ago
Sequoia shutting down its Scouts program marks the end of an era