Business
Oyedele seeks lasting rules to safeguard Nigeria’s economic reforms

The federal government is considering legislation to prevent successive administrations from reversing key economic reforms, as it seeks to establish a national policy framework to guide decisions on taxation, subsidies, trade and industrial development.
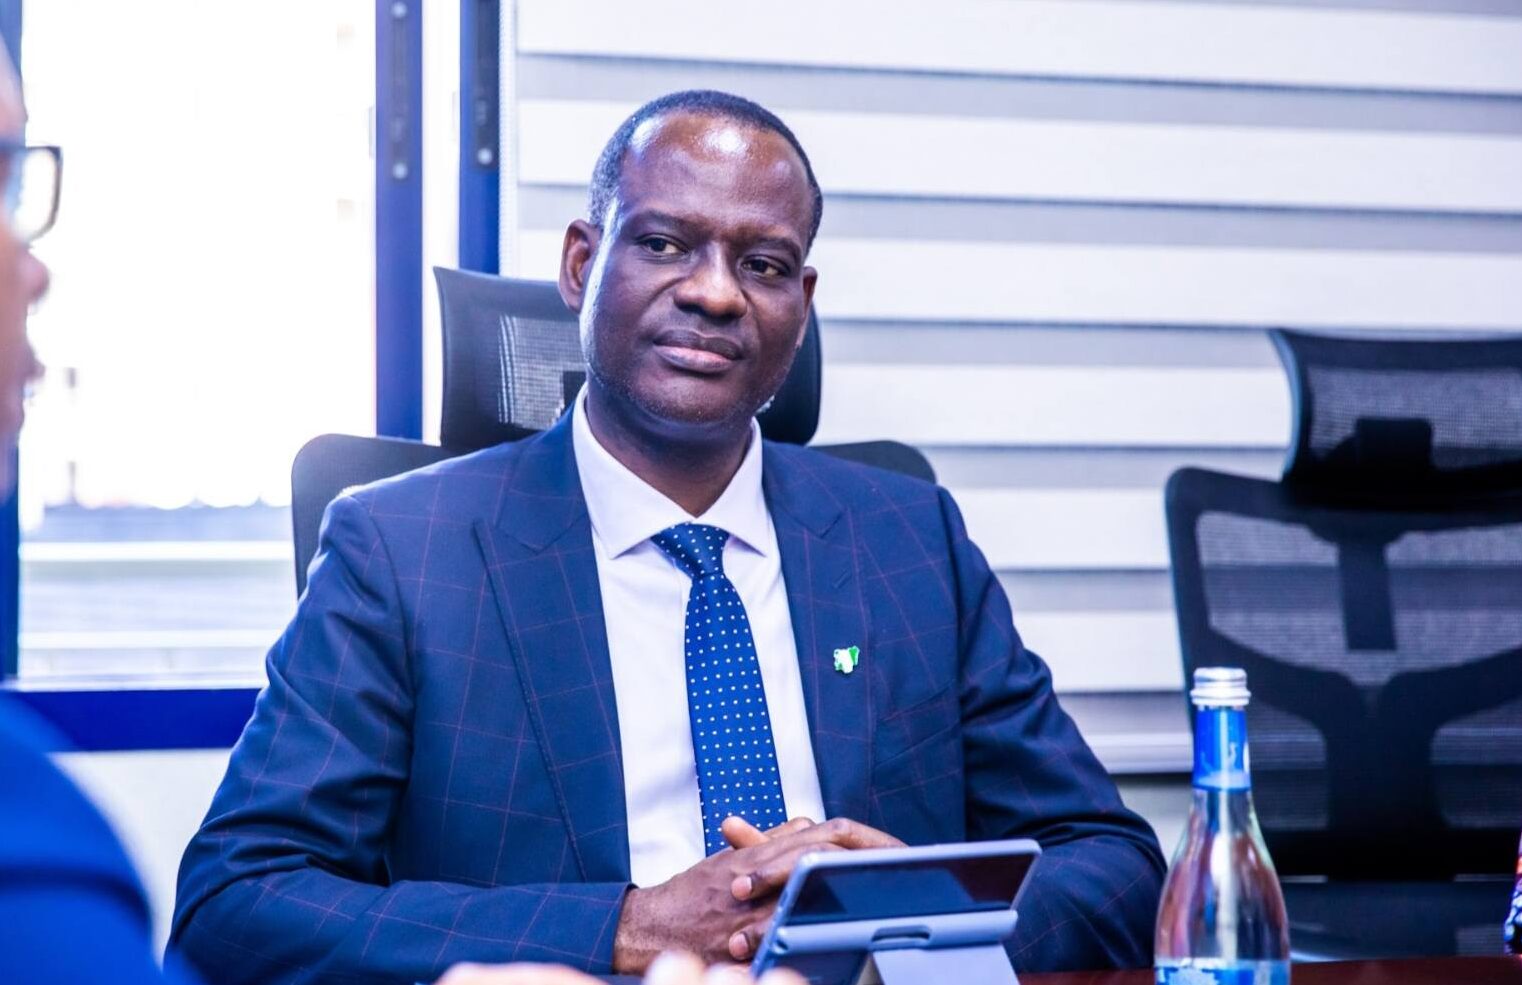
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, said the proposed framework would establish economic principles to guide successive governments, regardless of changes in political leadership.
He spoke on Monday at the 32nd Nigerian Economic Summit in Abuja, where he presented the draft of Nigeria Economic Policy Framework for public consultation.
“We now need to lock it in, in institutions, in law, as well as policy framework, so that it can be enduring,” he said during a panel session.
The proposal comes as President Bola Tinubu’s administration continues to defend its economic reforms, including the removal of petrol subsidies and changes to the foreign exchange system.
The government says the reforms are necessary to address economic distortions and improve long-term stability. However, their effects on household purchasing power and business costs have remained a subject of public debate.

Mr Oyedele said inconsistent economic policies had discouraged investment and undermined previous reforms, arguing that Nigeria needed a lasting approach to economic decision-making.
“Policy uncertainty is an invisible tax on enterprise. And unlike most taxes, it generates no revenue for government; it only destroys value and discourages investment,” he said.
He said the government was considering whether key provisions of the proposed framework should be backed by law, stressing that the document remained a draft and had not been approved as government policy.
Public consultation
According to Mr Oyedele, the consultation process will run until 27 November, after which the framework is expected to proceed to the Federal Executive Council for approval and the National Economic Council for endorsement.
The draft is built around stability, productivity, enterprise, capital, people, markets and institutions. It proposes common principles to guide economic decisions across government.
One of its key proposals is to require Policy Impact Assessments before major economic interventions. These assessments would set out the problem a proposed measure seeks to address, the evidence supporting it, its likely costs and beneficiaries, and the conditions under which it should end.
The assessments would cover interventions such as tax changes, tariff adjustments, regulatory restrictions and incentives.
The framework also proposes an annual National Economic Scorecard to measure whether economic growth is improving living conditions. Suggested indicators include real wages, productive employment and poverty levels.
The government says these measures would make economic decisions more transparent and allow Nigerians to assess policies by their outcomes rather than announcements alone.
The Ministry of Finance has published the consultation document on its website and invited businesses, professional groups, researchers and other stakeholders to submit recommendations.
No return to fuel subsidy
Mr Oyedele defended the removal of petrol subsidies, saying the artificial suppression of prices had distorted the economy and created costs that became increasingly difficult to manage.
He argued that government policy should focus on raising household incomes rather than keeping prices below levels that could be sustained by the market.
“Let’s not suppress prices. Let’s focus on raising income,” he said.
The minister also questioned Nigeria’s industrial protection policies, citing locally assembled vehicles that he said contained only about five per cent local content despite benefiting from tariffs and levies of up to 60 per cent.
He argued that protection for domestic industries should be temporary and tied to measurable performance, rather than shielding businesses indefinitely from competition. He also called for improvements in electricity supply, logistics and other infrastructure to lower production costs.
Mr Oyedele said the government was targeting inflation in the low single digits before the end of 2027, with the aim of creating conditions for single-digit interest rates. He did not provide a specific timeline for achieving lower borrowing costs.
He also cited student loans, pension payments, wage adjustments and subsidised credit for small businesses as interventions under the government’s broader economic programme.
He urged wealthy Nigerians to meet their tax obligations, warning that inadequate government revenue could worsen inflation, borrowing costs and pressure on the naira.
Tinubu administration defends reforms
The Minister of Budget and Economic Planning, Abubakar Bagudu, backed the call for policy consistency, saying President Tinubu had directed government officials to sustain the reforms despite concerns about their immediate effects on households.
“There will be no return to subsidy. There will be no return to those distortions,” Mr Bagudu said.
He said the Federal Government had reached agreements with state governments on better coordination of fiscal and monetary policies, infrastructure development, security and domestic production.
Mr Bagudu also said more than $6 billion had been mobilised from the World Bank and other development partners to support household resilience and economic opportunities.
Anambra State Governor, Charles Soludo, cautioned against abandoning macroeconomic stability, saying sustained policy discipline was necessary to achieve meaningful growth.
“The macroeconomic framework, the stability that is back, must never be taken for granted,” he said.
However, Mr Soludo argued that economic growth of about four per cent remained insufficient to deliver rapid poverty reduction and create enough jobs, calling for higher investment and faster expansion.
Calls for stronger productivity
Oxford University Professor of Economic Policy, Stefan Dercon, stressed the importance of controlling inflation and improving electricity supply, logistics and port operations to support economic growth.
He cautioned against indefinite protection for domestic industries.
“You can’t keep on protecting in the same way,” he said.
Chema Triki, co-founder and managing director of Growth Teams, said Nigeria needed to develop new productive capabilities and diversify exports rather than depend excessively on its domestic market.
She pointed to the country’s limited export diversification as a reason for strengthening industrial competitiveness.
READ ALSO: What African countries, others can learn from Nigeria’s economic reforms – Minister
Omoboyede Olusanya, group managing director of Flour Mills of Nigeria, called for lower interest rates, reliable infrastructure and improved agricultural productivity to reduce manufacturing costs.
He said expensive financing discouraged long-term investment, while poor logistics and unstable supplies of agricultural commodities weakened domestic industries.
Lagos State Governor, Babajide Sanwo-Olu, highlighted investments in ports, transport corridors, rail infrastructure and food logistics as measures to improve productivity and reduce the cost of doing business.
The Chairman of the Nigerian Economic Summit Group, Olaniyi Yusuf, urged the government to ensure that economic reforms translated into affordable living costs, productive employment and measurable improvements in household welfare.
The Minister of State for Budget and Economic Planning, Doris Uzoka-Anite, said the National Development Plan 2026–2030 would prioritise industrialisation, infrastructure, investment mobilisation, human capital development and stronger institutions.
She said the plan aimed to accelerate economic growth, create jobs and reduce poverty through better coordination of government policies, budgets and investment programmes.
The proposed Nigeria Economic Policy Framework is expected to undergo further consultation before formal consideration by the relevant government institutions.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.




Business
NGX Group buys 10% ownership in Nairobi Securities Exchange to extend East African presence
The Nigerian Exchange Group (NGX Group) has completed the purchase of a 10 per cent shareholding in the Nairobi Securities Exchange, East Africa’s largest stock exchange, to widen its reach in the region, where it already holds a similar equity interest in a bourse in Ethiopia.
The strategic stake supports its pan-African expansion ambition to grow its investment portfolio at scale as it continues to pursue regional leadership across West and East African markets, the company announced in a statement on Monday.
NGX Group said it sees the move as a key entry point into “one of East Africa’s most established capital markets,” helping enlarge its “investment portfolio beyond Nigeria and positioning the group to benefit from the long-term growth of the region’s capital markets.”
“It also reflects NGX Group’s disciplined approach to capital allocation, balancing strategic growth opportunities with its commitment to sustainable shareholder returns,” it added.
The group established its footprint in the region in April 2024 when it acquired a stake in the Ethiopian Securities Exchange without disclosing the size of the acquisition.
At the time, the Government of Ethiopia held 25 per cent in the bourse, with the remaining 75 per cent variously owned by private sector players.
“Through these investments, NGX Group continues to pursue opportunities that enhance its regional participation, diversify its sources of investment returns and support the development of more connected and competitive African capital markets,” NGX Group CEO Temi Popoola said.
Taking an equity position in security exchanges in Kenya and Ethiopia mirrors the group’s drive to take its partnership with other exchanges on the continent beyond cross-border market collaborations.
The broader push involves harnessing the value and investment prospects that African economies hold through their capital market operations.
READ ALSO: Hold your elected leaders accountable, INECs ex-commissioner urges Nigerians
NGX Group is optimistic that its investment in the Nairobi Securities Exchange will advance its objectives of stronger regional integration, portfolio diversification and shareholder value.
“African capital markets are at an inflexion point, where integration is moving from aspiration to architecture,” Umaru Kwairanga, chair of NGX Group, said.
“Exchange groups that commit patient capital to market infrastructure will help shape how capital flows across the continent,” he added.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.
-

 News3 days ago
Every ₦1 spent on advertising generates ₦16.50 in Nigeria’s GDP, ARCON says – Technology Times
-
News3 days ago
Tinubu (APC) in Jos: Promises to restore peace in the State and Nigeria
-
News3 days ago
Heavy Security as Tinubu Takes Campaign to Jos
-
News3 days ago
Yari Defends Tinubu on Insecurity, Says Opposition Failed to Tackle Crisis for Over 20 Years