Business
‘No retiree will be forgotten’ — Tinubu promises pension reforms

President Bola Tinubu has pledged to implement a long-delayed minimum pension guarantee and expand healthcare support for retirees, saying his administration is determined to ensure that Nigerians who served the country are not abandoned after retirement.
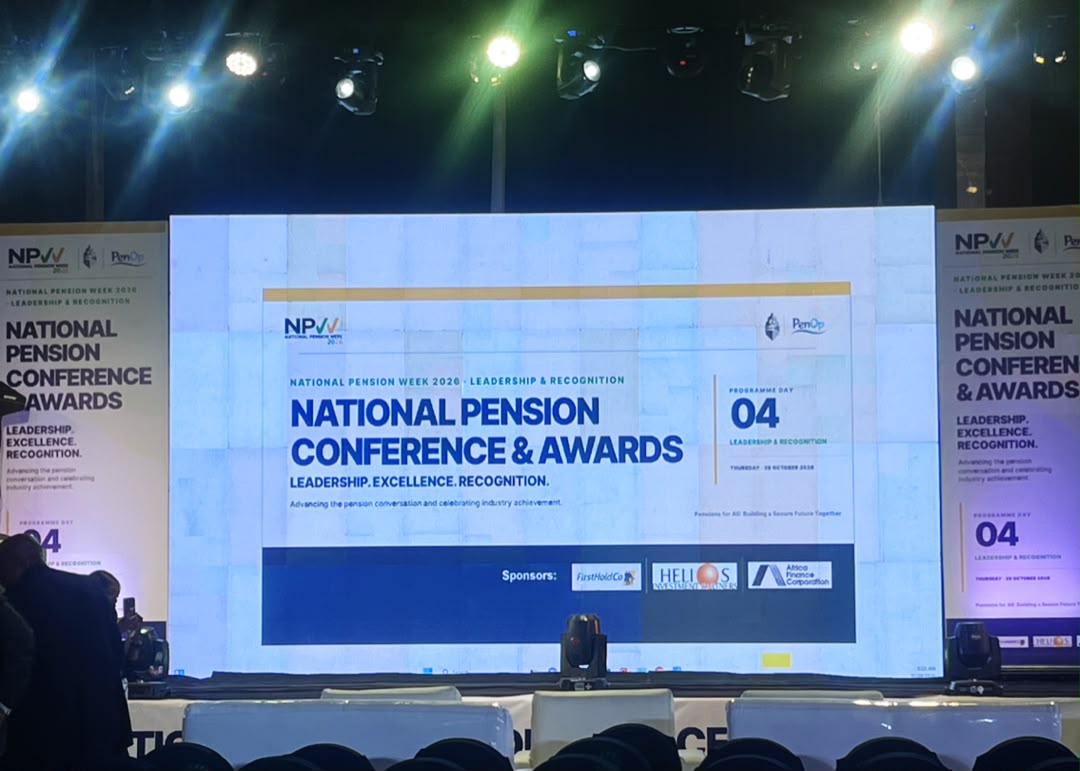
Mr Tinubu made the commitment on Thursday at the National Pension Conference and Awards, held at Transcorp Hilton, Abuja, as part of the maiden National Pension Week 2026.
Represented by the Secretary to the Government of the Federation, George Akume, the president said pension security was a national obligation and that his administration was determined to improve the welfare of retirees.
“A pension is not a favour granted by Government. It is a wage earned, deferred and held in trust. It is a promise. And this Administration has resolved that the promise will be kept,” he said.
He said his administration was working to address outstanding pension obligations and improve retirees’ welfare through measures intended to strengthen the Contributory Pension Scheme.
 The measures include implementing the Minimum Pension Guarantee under the Pension Reform Act 2014 and expanding PenCare, a healthcare support programme for eligible retirees.

“Since enactment, that promise has never been honoured. Under President Tinubu, it will be,” Mr Akume said, conveying the president’s commitment to implementing the minimum guarantee.
The president also reiterated his administration’s commitment to the N758 billion Federal Government Pension Bond, which was approved to settle outstanding accrued pension rights and strengthen the Pension Protection Fund.
“That was not an accounting exercise. It was an act of restitution to Nigerians who served their country and were made to wait for what they had earned,” Mr Akume said on behalf of the president.
The president said pension security should be treated as a government responsibility rather than a discretionary benefit for retired workers.
“Above all, no Nigerian who has served this nation will be forgotten in retirement. Nigeria will keep faith with those who kept faith with Nigeria.”
Minimum pension guarantee, healthcare support
The proposed Minimum Pension Guarantee is intended to provide a safety net for eligible retirees under the Contributory Pension Scheme whose retirement income is inadequate.
Although the Pension Reform Act 2014 provides for the guarantee, the minimum amount payable and the detailed implementation arrangements will depend on the relevant guidelines from the National Pension Commission (PenCom).
The president also highlighted PenCare, a healthcare support programme intended to improve access to essential medical services for low-income retirees.
The initiative is designed to extend retirement support beyond pension payments by helping eligible beneficiaries access healthcare services.
PenCom has begun rolling out PenCare, with an initial phase targeting 30,000 retirees. The programme is funded jointly by the commission and participating pension fund operators.
According to the president, the initiative reflected a broader approach to retirement welfare, judging the pension system not only by the savings contributors accumulate but also by the security and dignity those savings provide in retirement.
He urged relevant institutions to ensure that the measures produced tangible improvements in pensioners’ lives.
Pension assets rise, but concerns persist
The Director-General of PenCom, Omolola Oloworaran, said Nigeria’s pension assets rose from N20.79 trillion in July 2024 to N31.8 trillion in August 2026.
The N11.01 trillion increase represents about a 53 per cent growth over the period.
However, she said the expansion of pension assets had not translated into adequate retirement income for many contributors, particularly private-sector workers.
“Almost 70 per cent of private sector employees earn below the national minimum wage in retirement. More than 55 per cent of all retirees whose pensions fall below the minimum wage come from the private sector,” she said.
Ms Oloworaran attributed the problem partly to employers calculating pension contributions on limited portions of workers’ earnings rather than their full remuneration.
She said the statutory combined pension contribution of 18 per cent comprises 10 per cent from employers and eight per cent from employees, warning that inadequate pensionable earnings could weaken retirement benefits.
“Our private sector workers are retiring into poverty. This must change,” she said.
The PenCom chief urged private employers to contribute to the Pension Protection Fund alongside the Federal Government and pension industry operators.
She also challenged pension fund administrators to generate returns that exceed inflation, which continues to erode the purchasing power of retirement savings.
“Beating inflation is not an aspiration. It is your job,” she said.
Ms Oloworaran disclosed that the commission had secured commitments from pension industry operators to establish three million additional funded, active Retirement Savings Accounts within the next year. The target is intended to extend coverage to workers currently excluded from formal pension arrangements.
She also announced that President Tinubu would launch the Pension Security Initiative on 10 November, incorporating PenCare and the minimum pension guarantee.
The commission further directed pension fund administrators and custodians to complete their recapitalisation by 30 June 2027.
“Every pension fund administrator and custodian must complete recapitalisation by 30th June 2027. We are not changing our minds,” she said.
Highlighting recent improvements, Ms Oloworaran said some federal retirees had received pension increases ranging from 67 to 120 per cent, while certain Nigeria Social Insurance Trust Fund pensioners recorded increases exceeding 1,000 per cent.
She added that retired professors could now receive pensions equivalent to their final salaries, while some retirement benefits were being processed within 48 hours.
The commission also announced an exit benefit scheme for retirees from treasury-funded federal ministries, departments and agencies, with symbolic cheques presented at the event.
Tinubu warns against risky investments
President Tinubu warned pension fund administrators and custodians against exposing workers’ retirement savings to reckless investments, insisting that the pursuit of higher returns or national development must not compromise contributors’ financial security.
He said pension assets must be managed with transparency, accountability and strict risk-management standards.
Although pension savings could support infrastructure development and economic growth, he said investment decisions must prioritise the interests of the workers whose contributions make up the funds.
“National development must never come at the expense of pensioners. Every investment must stand on its own merits, pass rigorous tests of risk and return, and serve the best interests of contributors,” he said.
The president warned that inflation was weakening the purchasing power of retirement savings, making it necessary for pension operators to deliver sustainable returns without compromising capital preservation.
“Preservation without growth is a slow erosion. Retirement savings that fail to keep pace with inflation quietly betray the very people who saved them,” he said.
He urged pension fund administrators and custodians to strengthen their investment expertise, diversify portfolios responsibly, reduce operating costs and improve accountability.
According to him, the pension industry’s performance should be measured by the financial security it delivers to retirees rather than the volume of assets under management.
The president also called on PenCom to enforce pension regulations firmly and fairly, while urging public and private-sector employers to remit pension contributions fully and promptly.
He described the deduction of workers’ pension contributions without transferring the money to their Retirement Savings Accounts as a breach of trust.
The president further called on state governments, organised labour and other stakeholders to expand pension coverage, including among traders, artisans, farmers, transport operators and other self-employed Nigerians.
He said the government would promote the Personal Pension Plan and new distribution channels to make retirement savings more accessible to people outside conventional salaried employment.
“Pensions for All must mean exactly that: all,” he said.
He urged stakeholders to ensure the summit produced measurable commitments, including increased enrolment, faster benefit payments, improved investment performance and clearer disclosure of pension fund activities.
National Assembly reviews pension laws
Meanwhile, the Chairman of the House of Representatives Committee on Pensions, Jallo Mohammed, said the National Assembly was reviewing the Pension Reform Act 2014 and other pension-related legislation.
He said proposed amendments, including legislation concerning intelligence and military pensions, were progressing through legislative consideration ahead of public hearings.
Mr Mohammed also disclosed ongoing engagement with NNPC Pension Fund Limited over compliance with PenCom directives following years of regulatory concerns.
He pledged continued legislative oversight to improve pension administration, strengthen regulatory compliance and protect contributors’ retirement savings.
“Our shared objective must be to build a pension industry that not only protects the savings of today’s workers, but also guarantees greater financial security and dignity for future generations of retirees,” he said.
Background
Nigeria’s Contributory Pension Scheme was established under the Pension Reform Act 2004 and subsequently governed by the Pension Reform Act 2014. The framework requires employers and employees in covered employment to contribute towards retirement savings, with pension fund operators managing the accumulated funds under regulatory oversight.
The scheme was introduced to address weaknesses associated with previous pension arrangements, including delays in benefit payments and the accumulation of unfunded liabilities.
READ ALSO: PenCom urges SMEs to remit workers’ pensions, plan for retirement
However, some retirees have continued to face inadequate pension payments, delays in receiving accrued rights and difficulties meeting healthcare costs after leaving employment.
In October, PenCom announced that the Federal Government’s pension intervention had been used to clear inherited accrued pension liabilities dating back to 2007, with the commission reporting that 957,045 beneficiaries had been covered.
The commission has also identified the Minimum Pension Guarantee and PenCare as measures intended to improve the financial security and welfare of retirees.
President Tinubu said the success of the reforms should ultimately be measured by their effect on pensioners’ lives.
“The true measure of our success will not be how much money the system holds. It will be how much security, and how much dignity, it delivers,” he said.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.




Nigeria is among more than 50 countries planning to develop nuclear power or expressing interest in building new reactors, as global nuclear electricity generation reached a record high in 2025, according to a new report by the International Energy Agency (IEA).
The report, World Energy Outlook 2026, published on Thursday amid contentious negotiations over fossil fuel phase-out and electrification at the 31st session of the United Nations Climate Change Conference (COP31) in Türkiye, provides an assessment of global energy trends and prospects across regions.
The 564-page report said global nuclear power generation reached a record high in 2025 and is expected to continue rising, with more than 420 gigawatts (GW) of nuclear capacity currently operational across over 30 countries.
As of July 2026, the report said nearly 90 GW of additional nuclear capacity was under construction worldwide, the highest level in more than 35 years. The projects are spread across 17 countries, largely China, India, South Korea, Russia, Egypt and Türkiye.
The report said the ongoing construction includes small modular reactors (SMRs) in Argentina, Canada, China and Russia. Construction began on eight nuclear reactors in the first half of 2026, marking one of the highest levels recorded in four decades.
According to the IEA, more than 50 countries now have plans or targets for nuclear power or have expressed interest in developing new reactors.
These countries include African countries such as Egypt, Kenya and Nigeria; European countries including Italy, Poland and Türkiye; Middle Eastern countries such as Jordan and Saudi Arabia; and Southeast Asian nations, including Indonesia, the Philippines, Thailand and Vietnam.
Many of these countries are particularly interested in small modular reactors (SMRs), the report noted.
It said China continues to operate one of the world’s largest nuclear construction programmes, while the United States has approved lifetime extensions for several reactors, allowing them to operate for up to 80 years.
In the European Union, the IEA said nuclear power is increasingly viewed as critical to achieving energy security and climate goals, while Japan is gradually restarting reactors.
Nuclear development is also advancing in countries entering the sector for the first time. Bangladesh, Egypt and Türkiye have projects at advanced stages of construction, Uzbekistan is beginning work on its first nuclear power plant, and Vietnam is progressing with plans for its first reactor.
International support for nuclear energy has also strengthened, with multilateral development banks increasingly involved in financing the sector. As of August 2026, 38 countries had endorsed a pledge to triple global nuclear capacity by 2050.
The IEA said the prevailing geopolitical and energy security landscape could further accelerate nuclear development, as countries seek to diversify their energy mix, reduce exposure to market volatility and ensure reliable electricity supply amid growing electrification.
The agency said the 2026 energy crisis had prompted several countries to reinforce or confirm nuclear power plans, extend the operating lifetimes of existing reactors and reconsider restrictions on nuclear development.
READ ALSO: IEA says Nigeria’s energy investment could double in five years
Emerging electricity demand from electrification, artificial intelligence (AI) and data centres is also strengthening the case for reliable, dispatchable energy sources such as nuclear power.
However, the report noted that electricity generation trends vary across regions, reflecting differences in energy resources, security priorities and existing infrastructure.
While renewable energy is expanding across most regions and nuclear power is gaining ground in an increasing number of markets, the pace and composition of the transition differ considerably.
China, India and Southeast Asia are expected to retain coal-heavy electricity systems through 2035, although their energy mixes are projected to diversify as electricity demand grows faster than in most other regions.
Coal is expected to remain the dominant source of electricity in these regions, but wind, solar, nuclear and natural gas are also projected to expand, gradually creating more diversified energy sources.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.
-

 Business1 day ago
Elon Musk Launches X Money, Bringing Banking and Payments to Social Media Platform
-
News4 days ago
79% of local providers ready for Nigeria’s sovereign cloud, NITDA finds – Technology Times
-
News4 days ago
JOGAMA Announces November 20 Date for 16th Edition, Voting Closes November 17
-
Health1 day ago
JUTH Student Nurse Anaesthetist Dies After Collapsing During Football Match in Jos