Business
Nigeria’s Financial Exclusion Falls to 21% — Report

A new report by Enhancing Financial Inclusion and Advancement (EFInA) has found that Nigeria’s financial exclusion rate has fallen to 21 per cent. However, the remaining gap is increasingly concentrated among people with fewer economic resources.
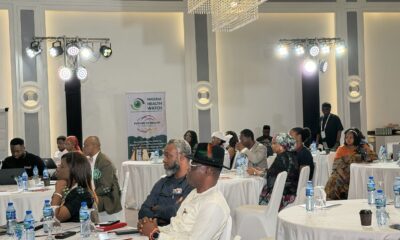
The finding is contained in the 2026 Access to Financial Services in Nigeria (A2F) Survey launched by EFInA in Abuja on Wednesday.
According to the report, 53 per cent of adults in the poorest wealth quintile remained financially excluded, compared with just 1 per cent in the richest quintile.
It said almost half of financially excluded Nigerians were in the poorest 20 per cent of the population, highlighting the growing link between poverty and exclusion from formal financial services.
EFInA said the findings showed that although more Nigerians were entering and using the formal financial system, greater participation was not translating into improved financial outcomes at the same pace.
The 2026 survey examined financial inclusion beyond access, focusing on financial health, resilience, consumer experience, economic activity and Nigerians’ ability to manage financial shocks.

The A2F Survey has been conducted biennially since 2008 and is one of Nigeria’s major sources of demand-side data on financial inclusion. It tracks how Nigerians use formal and informal financial services to meet daily needs, plan for emergencies, protect their futures and cope with financial pressures.
According to EFInA, the 2026 edition follows previous rounds conducted in 2008, 2010, 2012, 2014, 2016, 2018, 2020 and 2023, providing more than 17 years of longitudinal data.
The organisation said the survey captures financial and non-financial data that have served as a source of information for financial service providers, development organisations, policymakers, and regulators, including the Central Bank of Nigeria (CBN), the National Insurance Commission (NAICOM), and the National Pension Commission.
Methodology
During her presentation of the report findings on Wednesday, Foyinsolami Akinjayeju, Chief Executive Officer of EFInA, said that for the 2026 survey, they had the support of the National Bureau of Statistics in designing it.
She explained that, for the most part, the sampling of respondents was based on equal representation across states.
“Most states have the same sample size, for the most part. In some cases, we adjusted it slightly to account for design effects. This allows for headline indicators to be available at the state, regional and national levels,” she said
Mrs Akinjayeju said they surveyed adults aged 18 years and above and achieved a 98 per cent response rate.
“Our target was 18,950 respondents, and we were able to interview 18,679. So, that’s about a 98 per cent response rate,” she noted, explaining that the results show what is currently obtainable because the listing and data collection were done between April and June, with supervision from the National Bureau of Statistics.
She said the questionnaire was in English but had been translated into the major languages in Nigeria and into Pidgin English.
Digital finance expands
The survey found a significant increase in the use of digital financial services, with digital finance usage rising from about 47 per cent in 2023 to 64 per cent in 2026.
Mobile money use also more than tripled, rising from 12 per cent in 2023 to 38 per cent in 2026.
EFInA said Nigerians were increasingly using mobile money for everyday transactions, including bill payments, purchases and receiving money, in addition to transfers.
However, cash and financial agents remained important, while access to smartphones, connectivity and digital skills continued to vary across population groups.
For instance, 92 per cent of agricultural workers reported that they still received their payments in cash.
EFInA said the findings suggested that a completely digital-only approach to financial inclusion would be premature.
Savings rise, but credit and insurance lag
The survey also showed that formal savings increased from 38 per cent in 2023 to 53 per cent in 2026.
However, formal credit remained at 10 per cent, while insurance penetration stood at five per cent and pension participation at about nine per cent.
EFInA said the figures pointed to a financial system that was helping Nigerians move and store money more effectively than it was helping them finance livelihoods or transfer risks.
“This matters because financial inclusion is increasingly about what people can achieve with financial services, not simply whether they have access to them,” EFInA said.
The survey also highlighted persistent weaknesses in financial resilience. According to the findings, 61 per cent of Nigerian adults remained in severe liquidity distress, while debt stress increased.
Among adults who experienced financial shocks, 71.6 per cent relied on fragile or erosive coping mechanisms, compared with only 13.8 per cent who used protective or adaptive coping mechanisms.
EFInA said fragile coping mechanisms could include responses that help households survive immediate emergencies but weaken their ability to withstand future shocks.
The findings, therefore, raise questions about whether financial services are helping Nigerians recover from shocks without leaving them more vulnerable.
Farmers face financial vulnerability
The survey found that 51.2 per cent of farmers experienced a financial or economic shock.
Among farmers who experienced shocks, 52.2 per cent relied on erosive coping mechanisms, while 76 per cent experienced residual distress.
EFInA said the findings connected agricultural finance more directly with savings, credit, insurance, climate adaptation and the protection of livelihoods.
The survey also examined financial inclusion among women, business owners and young Nigerians.
Formal financial inclusion among women business owners increased from 67.5 per cent to 76.3 per cent, while inclusion among women farmers rose from 42.7 per cent to 53.6 per cent.
However, exclusion among dependent women increased to 52.2 per cent.
EFInA said the findings demonstrated why women should not be treated as a single homogeneous group when designing financial inclusion policies and products.
Consumer experience remains a concern
The survey also examined the quality of consumers’ experiences with financial service providers, including communication, customer support, service timeliness and fraud education.
According to EFInA, the findings showed that greater financial participation did not automatically guarantee an equitable customer experience.
EFInA’s boss said demand-side evidence was critical to understanding how Nigerians interact with the financial system.
“Demand-side evidence at this scale is national economic infrastructure. Nine rounds have given Nigeria a continuous record of how households behave through reform, shock and recovery,” Ms Akinjayeju said.
She said the latest survey went further by examining what financial inclusion was delivering in economic terms.
“I expect regulators, providers and partners to hold their own targets against what it shows,” she said.
EFInA said the A2F 2026 Survey was intended to shift the financial inclusion conversation from simply measuring access to examining what access enables Nigerians to achieve.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.




Tony Elumelu played a supreme role in getting investment bank Afrinvest back on track in 2011 after the global financial meltdown pushed the investment bank to the brink, its chief executive recalled in a letter to the tycoon seen by PREMIUM TIMES.
The multisectoral magnate, who is the top shareholder of United Bank for Africa, the Transcorp Group, and Seplat Energy, granted a soft loan of $1 million to Ike Chioke, the CEO of the financial institution, as a mark of urgent support when the firm direly needed the cash to recapitalise, the latter said.
“Fifteen years ago, Afrinvest was navigating one of the most challenging periods in its history, as we struggled to rebuild and recapitalise the business in the aftermath of the global financial crisis,” Mr Chioke said.
“At that critical juncture, when the future was far from certain, you made the remarkable decision to lend me US$1 million of your personal funds. You placed your confidence not simply in the prospects of a business but in me as an individual, my integrity, my determination and my conviction that Afrinvest could emerge stronger from adversity.”
This June, Mr Chioke eventually completed the repayment of the credit, according to the letter, describing the gesture as an extraordinary act of friendship, generosity and trust.
READ ALSO: Afrinvest repays undocumented $1 million from Elumelu with interest
Mr Elumelu, whose economic vision is anchored on what he calls “Africapitalism” – an investment philosophy that prioritises the private sector’s role in democratising the wealth Africa needs to power large-scale growth, has been involved in active philanthropic initiatives on the continent.
In March, his foremost charity project, the Tony Elumelu Foundation, turned sixteen, and he said the initiative had disbursed over $100 million in seed capital to 24,000 entrepreneurs in Africa and created more than 1.5 million jobs over the period.
The foundation expects to fund an additional 3,200 entrepreneurs this year, it said in September.
Mr Chioke applauded the profound impact Mr Elumelu’s financial assistance has had on Afrinvest, notably transforming it into a diversified regional financial services group with an expanding universe of clients and operations in asset management, investment banking, research & consulting, and securities trading.
Discover more from Premium Times Nigeria
Subscribe to get the latest posts sent to your email.
-

 News4 days ago
Plateau APC 2027 Campaign Council inaugurated today in Jos
-
News4 days ago
Nigerians’ data appetite drives MTN Nigeria revenue to ₦2.68tn – Technology Times
-
News3 days ago
Plateau Ndigbo Crown Chief Johnson Nwosu as New Igwe
-
News2 days ago
Anthropic is working on a system to prove AI models’ identity