Connect with us

Business

Dr. Lucas Durojaiye Leads Nigerian Delegation in 3-Day Working Visit to ECOWAS Insurance Secretariat

info

Published

on

The Chairman of the Nigerian National Bureau and Managing Director/CEO of Sovereign Trust Insurance PLC, Dr. Lucas Durojaiye, has led a high-powered Nigerian delegation on a three-day working visit to the Permanent Secretariat of the ECOWAS Brown Card Insurance Scheme.

The visit provided a platform for high-level discussions aimed at strengthening the regional motor insurance framework, accelerating digital transformation, and optimizing claims management to facilitate the seamless movement of people, goods, and services across West Africa.

During the engagement, delegates focused on key strategic priorities to enhance the Scheme’s overall efficiency:

 Digital Transformation & Operations: Modernizing the claims management system and leveraging technology to boost operational speed and transparency.

 Institutional Cooperation: Deepening relations between individual Member Bureaux and the Permanent Secretariat to ensure unified execution across member states.

 Regional Integration: Aligning insurance frameworks to directly support the free movement of citizens and cross-border trade throughout the ECOWAS community.

The Permanent Secretariat commended Dr. Durojaiye and the Nigerian delegation for their proactive leadership and unwavering commitment to the Scheme’s institutional goals. Both parties reaffirmed the necessity of regular consultation among Member Bureaux as the framework undergoes its ongoing modernizing push.

About the ECOWAS Brown Card Insurance Scheme

The ECOWAS Brown Card Insurance Scheme serves as the official regional motor vehicle insurance coverage framework across West Africa, facilitating safe, legal, and seamlessly insured cross-border travel for motorists within member states.

The post Dr. Lucas Durojaiye Leads Nigerian Delegation in 3-Day Working Visit to ECOWAS Insurance Secretariat appeared first on Business Today NG.

Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

Business

NCC seek stronger cyber resilience as AI intensifies cyber threats

info

Published

on

The Nigerian Communications Commission (NCC) has called for stronger collaboration, improved digital security infrastructure and effective policies to address emerging cyber threats driven by Artificial Intelligence (AI).

Dr Aminu Maida, Executive Vice-Chairman of the NCC, made the call at the second edition of the International Cybersecurity Conference (ICSC), held on Tuesday in Abuja.

The theme of the conference was, “Cyber Resilience in the Age of AI: Defending Minds, Networks and Nation”.

Maida said AI had significantly increased the sophistication, speed and scale of cyberattacks, making cybersecurity a national imperative.

He said telecommunications infrastructure had become central to Nigeria’s digital economy, supporting financial transactions, communications, public services and business operations, thereby making its protection critical to national security.

He said cyber resilience went beyond preventing attacks to developing the capacity to anticipate, withstand and recover from disruptions while ensuring the continuity of essential services and economic activities.

According to him, emerging threats include AI-driven phishing, automated credential attacks, deepfakes designed to bypass authentication systems and malware capable of modifying itself to evade detection.

“The recent international cybersecurity incidents involving attacks on supermarket refrigeration systems in France and spyware targeting journalists and media personnel in the Middle East underscore the need for stronger digital defences.

“Section 4 of the Nigerian Communications Act, 2003, mandates the commission to protect consumer rights, safeguard national interests and promote the safety and efficiency of communications infrastructure.

“We have established the NCC Computer Security Incident Response Team (NCC-CSIRT) to monitor threats, facilitate intelligence sharing and coordinate responses to cybersecurity incidents across the telecommunications sector,” he said.

Maida said that the commission’s cyber resilience framework for the Nigerian communications sector provided common security standards for licensed operators and strengthened coordination with the national Computer Emergency Response Team, (ngCERT).

“There are three critical areas for strengthening cyber resilience. They include protecting human minds through cybersecurity awareness.

“There is also securing networks through robust security architecture, and defending the nation through collaboration among regulators, telecommunications operators, financial institutions and security agencies,” he said.

He urged telecommunications operators to adopt Zero Trust Architecture, which requires continuous verification of users and systems, while ensuring that AI models integrated into network operations were regularly assessed for vulnerabilities.

The National Security Adviser (NSA), Malam Nuhu Ribadu, said that digital development and national security could no longer be treated as separate priorities.

Ribadu was represented by Prof. Gerald Ilukwe from the Office of the National Security Adviser (ONSA) .

He said that AI presented opportunities for strengthening cyber defences but could also enable criminals to develop sophisticated scams, clone voices and spread false information.

He urged Nigerians to verify identities and authenticate suspicious requests before taking action.

“There is a need to secure digital supply chains, including AI models, data services and third-party technology providers.

“Vulnerabilities within one organisation can compromise other institutions and critical national infrastructure.

Ribadu said that the ONSA, through the National Cyber Security Coordination Centre, was strengthening coordination among relevant institutions and providing tools, laboratories and cyber ranges to analyse threats, investigate incidents and test response capabilities.

He said that a review of the National Cybersecurity Policy and Strategy, last updated in 2021, was underway to address emerging challenges, including AI-enabled fraud, supply-chain vulnerabilities, workforce development and international cooperation

“Recommendations from the conference will contribute to the ongoing review. The revised strategy will establish measurable priorities, promote accountability and strengthen the country’s capacity to respond to cyber incidents,” he said.

Rep. Ayodeji Stanley, Chairman, House of Representatives Committee on ICT and Cybersecurity, described cybersecurity as a moving target that required continuous innovation, adaptable legislation and international cooperation.

Stanley drew on his experience working on complex information technology systems in the United States.

He said the transition from traditional computing to cloud technologies had introduced new security challenges, requiring continuous improvements in protection mechanisms.

He urged policymakers, security experts and technology practitioners to develop forward-looking solutions that would protect critical systems across sectors, including food security.

Stanley said that cyberattacks could have consequences beyond the disruption of digital services.

He called for a collective global response to cyber threats, saying countries must work together to develop effective policies and innovative approaches capable of addressing the rapidly changing cybersecurity landscape.

(NAN)

The post NCC seek stronger cyber resilience as AI intensifies cyber threats appeared first on Business Today NG.

Continue Reading

Business

Fidelity Bank Plc redeems $400m eurobond at maturity

info

Published

on

1750329669604 e1778532147144.jpg

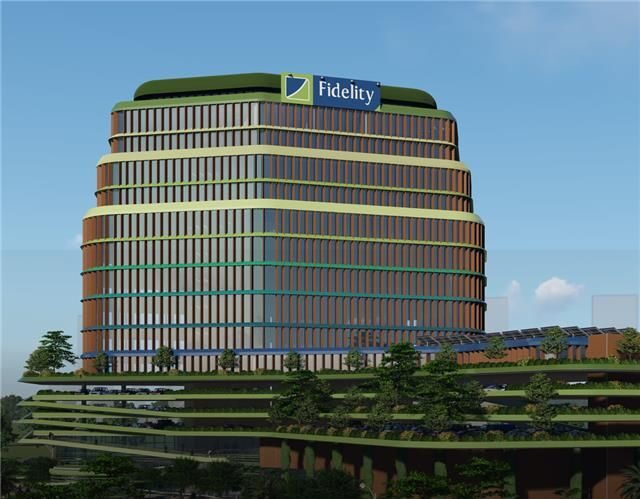
Fidelity Bank Plc has redeemed its 5-year $400 million Senior Unsecured Notes at maturity, reaffirming its commitment to meeting investor obligations and reinforcing its track record in the international debt capital markets.

Issued on 28 October 2021, the 5-year Eurobond matured on 28 October 2026 and carried an annual coupon of 7.625 per cent, payable semi-annually. Fidelity Bank met all scheduled coupon payments throughout the life of the instrument and has now fulfilled its final repayment obligation in full, covering both principal and accrued interest.

The redemption was funded from internally generated liquidity as part of the bank’s forward-looking liquidity management strategy. Through a dedicated sinking fund, Fidelity Bank progressively provided for the maturing obligation, enabling the bank to meet its commitment while maintaining business-as-usual operations and compliance with applicable regulatory liquidity requirements.

Commenting on the development, Fidelity Bank Plc’s Managing Director and Chief Executive Officer, Nneka Onyeali-Ikpe, said the successful redemption reflected the bank’s disciplined approach to financial management and its commitment to delivering on its obligations.

“This successful redemption demonstrates the strength of our franchise, the discipline of our balance sheet management and our commitment to honouring our obligations to investors and other stakeholders. We anticipated this maturity from the outset and planned accordingly, which reflects our commitment to responsible financial management,” Mrs Onyeali-Ikpe said.

The redemption further strengthens Fidelity Bank’s record in the international debt capital markets. The 2021 issuance marked the bank’s third Eurobond transaction, following earlier issuances in 2013 and 2017, in which the bank raised $300 million and $400 million, respectively. The 2021 offer attracted investor orders exceeding US$700 million, reflecting strong demand for the bank’s international debt offering.

PT WHATSAPP CHANNEL
Dangote Refinery AD

READ ALSO: World Bank projects 23% rise in global commodity prices in 2026

The successful Eurobond redemption follows the completion of Fidelity Bank’s recapitalisation programme ahead of the regulatory deadline. The bank’s capital-raising efforts increased its eligible regulatory capital to approximately N533 billion, exceeding the N500 billion minimum capital requirement for banks with international authorisation.

The completion of these milestones underscores Fidelity Bank’s strong capital position, prudent liquidity management and disciplined approach to financial execution. It also reinforces the Bank’s capacity to meet its financial obligations while pursuing its strategic growth objectives across domestic and international markets.


Discover more from Premium Times Nigeria

Subscribe to get the latest posts sent to your email.

Continue Reading

Trending